For millions of American households, holding roughly twelve to twenty-four months of cash reserves outside invested assets transforms the anxiety of career exhaustion into an intentional choice rather than a financial emergency.
A burned-out professional in their late fifties or sixties secretly exhausts themselves daily while wondering if they can walk away from decades of routine.
Financial independence and emotional burnout intersect to create a definitive tipping point for retirement.
You have enough saved and planned to finally walk away from your career.
Determine your exact readiness to retire through concrete financial, physical, and emotional milestones.
Quick Tips Before You Start
Run Portfolio Math
Calculate your total liquid assets against a strict four percent withdrawal rule.
Check Healthcare Gaps
Account for private insurance premiums if you plan to retire before age sixty-five.
Test Your Routine
Take a two-week staycation to test whether your daily habits align with full-time freedom.
1. Your portfolio hits your target safe withdrawal number
Reaching a $1.25 million portfolio target means your accumulated savings can finally support a 4 percent safe withdrawal rate, matching directly against a $60,000 annual spending baseline.
The trade-off is that market volatility hitting right before your planned exit can temporarily upend the math, requiring you to pause withdrawals or rely on a cash buffer until prices recover.
Crossing this threshold means acknowledging that even when the numbers on the screen finally align with your exit date, external market drops demand patience and a willingness to adapt your timeline.
💡 Tip: Review your portfolio balance quarterly rather than daily to avoid emotional trading decisions.
| Sign | Financial Indicator | Emotional Indicator |
|---|---|---|
| 1. Portfolio Target | $1.25M portfolio at 4% withdrawal | Confidence in passive income |
| 2. Monday Dread | Income covers $60,000 baseline | Chronic professional exhaustion |
| 3. Zero Debt | Paid-off mortgage and car loans | Relief from monthly obligations |
| 4. Passive Streams | Pensions or dividends cover expenses | Independence from active labor |
| 5. Clear Vision | Budget supports new lifestyle | Running toward purpose |
💡 PRO TIP
The Four Percent Rule Reality
A four percent withdrawal rate is a historical baseline, not a strict guarantee. Build a flexible spending floor so you can pull back during market downturns.
2. You dread Monday mornings more than you enjoy your paychecks
Persistent emotional exhaustion often signals that continuing to show up at a job costs your health and well-being far more than any additional paycheck yields.
Normal workplace stress comes and goes with project deadlines, but chronic professional dread wears down your resilience until every Sunday evening feels like an impending sentence.
Evaluating the true cost of staying in a soul-crushing career involves weighing the extra financial margin you gain against the emotional toll of trading your remaining healthy years for a salary you no longer need.
Before you hand in your permanent resignation over a temporary rough patch, consider taking an extended sabbatical to test whether a complete break restores your energy or if you truly are ready to leave the workforce behind for good.
Giving yourself permission to step back temporarily or permanently acknowledges that human endurance has a hard ceiling, and no spreadsheet balance is worth sacrificing your mental health.
💡 Tip: Track your daily energy levels for two weeks to see if burnout is situational or systemic.
Burnout vs. Readiness — At a Glance
🔋 Energy Drain
Constant
📅 Recovery Time
None over weekend
🎯 Primary Focus
Immediate escape
⚖️ Financial Cost
High stress vs margin
Key Takeaway
Chronic dread indicates your career has run its course.
3. Your primary mortgage and all consumer debts are fully paid off
Pay off your primary mortgage and all remaining consumer debts before you officially submit your retirement paperwork.
Eliminating fixed monthly debt drastically lowers the total income your household needs to survive, changing your baseline survival number from a stressful ceiling down to a manageable baseline.
Carrying car loans or high-interest credit card balances into your post-work years creates dangerous fixed obligations that drain your cash flow when you no longer have a steady paycheck coming in every two weeks.
A zero-mortgage budget optimizes your monthly cash flow, though carrying a low-interest fixed loan under specific, calculated conditions can sometimes represent a manageable exception if your liquid reserves remain robust.
💡 Tip: Keep your housing payment at zero by finishing your mortgage payoff at least six months before retirement.
Post-Retirement Monthly Budget
4. Passive income streams cover your baseline fixed expenses
The worry that a portfolio cannot completely support daily survival without active labor is entirely normal to carry.
Reviewing your independent cash streams means tracking whether stable dividends, reliable rental income, or traditional pensions consistently cover your baseline living expenses of $55,000 to $65,000 annually without touching your principal.
Covering those fixed costs with passive inflows drastically reduces portfolio drawdown risk during market downturns, and anyone lacking guaranteed independent streams should wait for higher coverage before stepping away.
Check your bank statements at tax time to verify what percentage of your baseline living costs is truly paid by non-work sources rather than active savings.
💡 Tip: Set up automatic dividend reinvestment until you officially cross your retirement date.
Active Salary vs. Passive Streams
Active Salary
- Requires daily time and physical presence
- Subject to corporate layoffs and restructuring
- High stress levels and commute burdens
- Tied to rigid workplace schedules
Passive Streams
- Generated independently of your labor
- Provides steady cash flow during market dips
- Flexibility over your daily schedule
- Reduces overall portfolio drawdown risk
5. You have a clear vision for your time instead of just escaping work
Many assume that simply escaping a stressful job automatically creates a peaceful and satisfying retirement.
Leaving the workforce requires running toward a genuinely fulfilling lifestyle rather than just running away from an exhausting career.
The psychological risk of losing your professional identity is real when weekdays stretch out completely blank, which is why deliberate routines matter so much.
Test an ideal retirement schedule during a vacation week before official resignation to see how your daily energy actually holds up.
Automate your weekday mornings by scheduling specific volunteer work, hobbies, or exercise blocks ahead of time to keep your routine grounded.
💡 Tip: Draft a weekly schedule before you retire so you never wake up wondering what to do.
Retirement Lifestyle Myths
6. Healthcare costs are fully accounted for in your pre-Medicare budget
The thought of paying private health insurance premiums out of pocket before qualifying for Medicare feels terrifying.
Bridging the healthcare gap from age 62 to 65 requires dedicated savings built directly into your annual budget for private Marketplace health insurance premiums.
Compare your current employer-sponsored health coverage expenses against private individual plan estimates, and remember that individuals lacking these specific funds must delay retirement until hitting age 65.
💡 Tip: Shop private health insurance options six months prior to quitting to avoid coverage surprises.
Healthcare Planning Essentials
7. Your cash buffer protects you from immediate market downturns
Holding one to two years of cash prevents you from selling investments during a sudden stock market crash.
A twelve to twenty-four-month cash cushion strategy operates entirely outside your invested equity assets.
These cash reserves prevent sequence of returns risk from gutting your portfolio during your first few retirement years.
Individuals with volatile spending habits must build larger emergency funds before pulling the retirement trigger.
Keep your cash buffer in a separate high-yield savings account.
💡 Tip: Keep exactly twenty-four months of living expenses in cash so you never sell stocks during a bear market.
8. Your spouse or partner is fully aligned with your exit timeline
Shared expectations prevent severe marital friction when household lifestyle changes and active incomes stop.
Joint retirement expectations and shared spending goals must be discussed openly over several kitchen table conversations.
Mismatched retirement timelines can strain relationship dynamics if one partner feels rushed into stopping work.
Use a structured compromise framework to align on an official exit date that satisfies both partners.
Schedule a monthly money date to review your shared retirement vision.
💡 Tip: Ensure both partners agree on the post-retirement budget before submitting your resignation letter.
9. You find yourself constantly planning hobbies instead of projects
Mental bandwidth permanently shifting to personal passions indicates your career has naturally run its course.
Your mental focus changes when you are checked out of office politics and fixated on weekend creative pursuits.
Side projects or hobbies can be evaluated for potential modest income generation during your early retirement years.
Individuals lacking a solid fallback interest should stick out one more year to pad their savings cushion.
Dedicate your evenings to testing out your favorite creative hobbies.
💡 Tip: Turn one weekend hobby into a consistent daily practice before leaving your job.
10. Your emergency savings can handle a major unexpected home or medical repair
People assume that once your monthly salary stops, your regular savings account automatically covers whatever life throws at you.
That is a dangerous mistake when a sudden roof leak or unexpected hospital bill can easily cost $8,000 to $15,000 out of pocket.
Shifting your mental focus toward personal projects requires ensuring that extra liquidity exists outside your core investments to handle major crises without derailing your entire fixed-income structure.
Unexpected home maintenance and vehicle repairs must be factored directly into your post-work budget rather than treated as surprises.
Drawing down your primary investment portfolio during a sudden market dip to pay for an emergency carries severe long-term consequences that standard working emergency funds are specifically designed to prevent.
💡 Tip: Maintain a separate emergency fund specifically for home repairs so you never touch your investment portfolio.
11. The thought of working five more years fills you with absolute dread
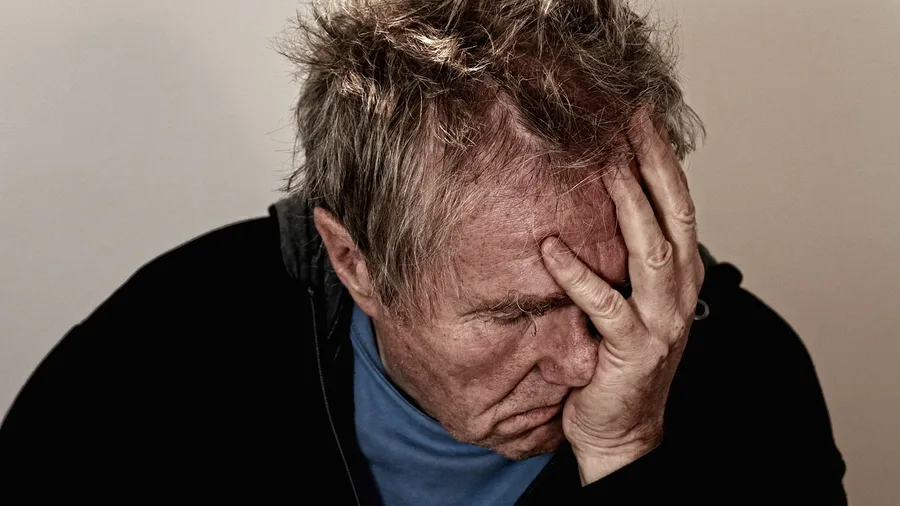
Staring at the ceiling on a Sunday night while feeling a heavy physical weight in your chest is a clear signal that emotional intolerance for another medium-term stint is a valid psychological indicator to pivot.
A common mistake is treating retirement math as a pure spreadsheet exercise while completely ignoring qualitative life satisfaction and the real health costs of pushing past your absolute mental limit.
When quantitative financial readiness aligns with overwhelming burnout, sitting down with a fee-only fiduciary helps validate your gut feeling alongside the hard portfolio metrics.
💡 Tip: Consult a fee-only fiduciary to run a final stress test on your portfolio before you resign.
Frequently Asked Questions
Is it too late to start investing at 40?
It is never too late to start building your portfolio. Focus on increasing your savings rate and maximizing employer matching programs immediately.
How much should I have in my emergency fund?
Aim for twelve to twenty-four months of living expenses in cash once you retire, or three to six months while you are still working.
Should I pay off debt or save first?
Wipe out high-interest consumer debt before retiring, but low-interest fixed mortgages can sometimes be carried if your cash flow supports them.
Is it okay to pause my retirement contributions for a while?
Pausing contributions hurts long-term compounding, but short pauses during personal financial emergencies are sometimes necessary to survive.
How much should I save before quitting my job?
Target a portfolio that supports a safe four percent withdrawal rate covering your annual living expenses comfortably.
Finalizing Your Exit Strategy and Taking Your Life Back
Weigh your portfolio readiness against your emotional fatigue to make a final exit plan.
A burned-out professional in their late fifties or sixties secretly exhausted by their career can finally walk away, trusting a safe withdrawal rate and cash buffer to handle market drops.
Take your life back with absolute financial and emotional security by scheduling your first portfolio review this week.
Ready to Review Your Numbers?
Check your portfolio withdrawal rate against your baseline expenses today and map out your exit timeline.