Everyone in your social circle makes moving down the street from their grandchildren sound like pure devotion, yet your hesitation feels like an unspoken betrayal.
It is not a character flaw; it is basic balance sheet literacy. For households holding between $4,000,000 and $12,000,000 in net worth, relocating cross-state into high-cost suburban markets routinely triggers six-figure tax liabilities, real estate transaction drag, and an unexpected loss of personal autonomy.
Allocating $35,000 to $60,000 each year toward first-class travel and shared vacation homes builds far deeper multi-generational memories without sacrificing your established tax domicile or personal freedom.
A clear evaluation of residency rules, embedded capital gains, and lifestyle infrastructure reveals that staying put often delivers the greatest long-term value for the entire family.
Staying Put vs. Relocating — The Core Metrics
Relocating Can Trigger Heavy State Estate Taxes
Moving across state lines can instantly slice six figures off an inheritance.
Families with estates between $4,000,000 and $12,000,000 often build their wealth in places like Florida or Texas, where state estate tax rates sit at zero. Establishing a new legal domicile in Massachusetts with its $2,000,000 exemption cap, or Oregon with a $1,000,000 limit, immediately pulls millions of previously protected assets into the state tax net.
The resulting estate liability is substantial.
On an $8,000,000 balance sheet, that shift in legal residency exposes taxable brokerage and liquid holdings to state estate tax bills between $600,000 and $800,000.
Estates safely below state statutory exemption caps avoid this exposure entirely, but larger portfolios face steep wealth erosion simply by changing an address.
Preserving your primary legal domicile in a tax-friendly jurisdiction keeps your wealth transfer plan intact. It insulates family capital from regional revenue departments, allowing you to pass full balances down to grandchildren rather than forfeiting a massive cut to state coffers.
The Hidden Balance Sheet Costs of Relocating
Financial friction points on a typical $8,000,000 family estate
Selling Long-Held Real Estate Triggers Large Gains
Liquidating your primary home to follow family generates an immediate tax bill that permanently erodes family balance sheet capital.
Consider a home purchased 25 years ago for $350,000 that now appraises at $1,850,000. That sale realizes a $1,500,000 gain, but federal Section 121 rules cap the married exclusion at $500,000. The remaining $1,000,000 sits exposed to federal capital gains rates, the 3.8% net investment income tax, and state taxes.
Transaction friction quickly consumes another sizable chunk.
Broker commissions, title fees, and transfer taxes eat 6% to 8% of that $1,850,000 transaction. Rolling what remains into a $2,200,000 suburban property near the kids introduces new closing costs alongside an ongoing $28,000 annual property tax bill that continues every single year.
Staying put changes the math entirely. Holding the original real estate until it passes through probate grants heirs a full step-up in basis to fair market value, wiping out the embedded gain.
That tax bill disappears for the next generation.
Relocation Math — Strategic Decision Thresholds
📉 Immediate Portfolio Depletion
Requires $650,000+ new cash injection
⚖️ Carrying Cost Trade-Off
$28,000 tax covers 6 months luxury rent
✈️ Optimal Cash Flow Strategy
Fund $35k-$60k visits from asset yield
⚠️ Primary Execution Risk
Forfeiting stepped-up basis is irreversible
🗓️ Re-Evaluation Cadence
Audit local equity and health every 3 years
🚫 Skip Relocation If
Grandchildren are within 6 years of college
Core Guideline
Preserve full estate basis protections while using annual portfolio cash flow for high-end seasonal travel.
Destination Homes Attract Visits Better Than Suburbia
Grandchildren visit far more reliably when your property functions as an appealing vacation destination rather than an ordinary house down the street.
A long-held residence in a coastal, mountain, or resort setting naturally draws adult children and grandchildren for extended holiday breaks. Trading that environment for a $2,200,000 house in an adult child's suburb reduces exciting family getaways to routine weeknight drop-ins and neighborhood traffic, quietly diminishing the special magic of visiting grandparents.
The travel alternative is vastly cheaper.
Allocating $35,000 to $60,000 each year toward first-class airfare, luxury rental villas near family, and covering all ground expenses costs far less over a decade than real estate carry costs. That annual budget lets you pamper visiting relatives with dedicated guest suites and fully funded flights while keeping your capital compounding undisturbed.
You provide an effortless vacation experience for busy working adult children without sacrificing your financial foundation. It turns every family gathering into an intentional, anticipated event rather than a rushed chore between workdays.
Great memories thrive on anticipation, not proximity.
💡 PRO TIP
Fund the Trip, Skip the Friction
Send round-trip business class tickets directly to your adult children for school holidays. Removing their financial and logistical burden creates eager, stress-free visitors.
Adult Children Often Move Away for Career Growth
Corporate promotions and regional industry shifts routinely pull mid-career professionals into new metro areas every three to five years.
Buying a $2,200,000 single-family home to share a neighborhood with your adult children leaves you completely exposed when a new corporate transfer arrives. If they accept a promotion two states away, you are suddenly stranded in a high-cost suburb with no independent roots, no peer network, and an oversized property.
Rapid real estate turnover quickly destroys liquid capital.
Transaction friction from broker commissions, transfer taxes, and physical moving bills absorbs roughly 8% to 10% of a home value on each round trip. Absorbing those frictional losses twice within four or five years erodes principal that should remain invested and compounding in your taxable brokerage accounts.
Establish a firm five-year career-stability requirement in the child's current market before considering any permanent purchase, ensuring their geographic roots are truly set before committing your balance sheet.
Relocating Next Door vs. Maintaining Strategic Distance
Relocating to Suburbia
- Becomes default emergency childcare provider
- Risk of child relocating 3 years later
- Loss of long-term medical specialists
- Exposure to high state estate and property taxes
Holding Primary Domicile
- Preserves tax-favored residency status
- Retains step-up in basis on primary home
- Funds focused, premium family getaways
- Protects established peer network and lifestyle
Living Next Door Invites Default Childcare Demands
Residing five minutes away inevitably shifts the grandparent relationship from intentional, festive visits into default logistics, emergency sick-day coverage, and daily after-school carpools.
When you live around the corner, setting boundaries around your personal schedule feels uncomfortably close to rejection for busy working parents. Saying no to a last-minute afternoon pickup feels personal, generating quiet resentment and interpersonal friction that slowly poisons the relationship you moved to cultivate.
Preserving family goodwill often means funding solutions instead.
Affluent families protect their retirement independence and preserve domestic harmony by gifting the cost of a private full-time nanny or au pair directly. Paying for outsourced professional help solves the adult children's childcare crunch without drafting you into daily domestic labor or sacrificing the schedule you spent forty years building.
Physical distance keeps your time with grandchildren special, focused, and free from the administrative exhaustion of running a second household's daily school and sports schedules.
The Daily Reality: Proximity vs. Distance
Rebuilding Top Medical Networks Takes Years
Relocating across state lines immediately disrupts decades of clinical continuity, severing established ties with trusted concierge physicians, cardiologists, and specialized surgical teams.
Retirees holding $4,000,000 to $12,000,000 in net worth have spent years assembling responsive healthcare networks that understand their baseline health. Starting over in a competitive metropolitan suburb means joining six-month waitlists for premier specialists, delaying routine screenings, and managing the friction of transferring complex medical charts between hospital systems.
Gaps in preventive care carry compounding health risks.
Transferring ongoing treatment protocols, specialized prescriptions, and chronic care management to unfamiliar practitioners frequently leads to miscommunications and fragmented treatment plans. The administrative burden of re-establishing that level of care often takes two to three years of sustained effort.
A geographic move for healthcare is justified only when an aging parent develops acute physical needs requiring direct, daily proximity to specialized academic medical centers or dedicated memory-care facilities.
⚠️ COMMON MISTAKE
The Specialist Waitlist Trap
Never relocate assuming you will immediately book elite specialists. Premium healthcare markets in major metro areas often have six-month intake delays for non-emergency patients.
Local Social Circles Protect Longevity and Health
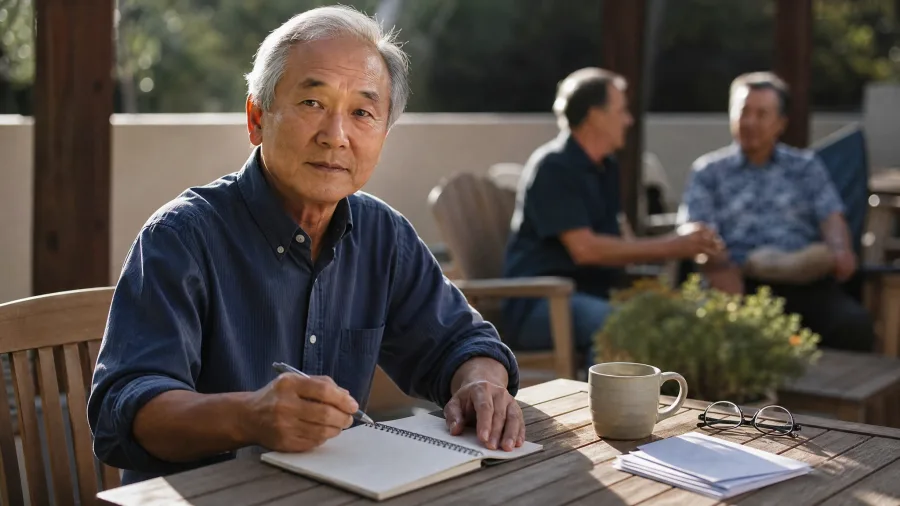
Uprooting your daily life to sit five minutes from family often replaces a vibrant peer community with long, empty weekdays alone.
Adult children work demanding corporate schedules and grandchildren spend full days in classrooms and sports practices, leaving relocating parents isolated from Monday through Friday. Decades spent building influence on local non-profit boards, standing weekly tennis games, and deep civic ties cannot be duplicated quickly in an unfamiliar, youth-dominated commuter town.
Social capital takes decades to accumulate.
Regular intellectual stimulation among peers and active community involvement directly support cognitive resilience and long-term vitality in retirement. When retirees abandon their own social infrastructure to orbit an adult child's household, they surrender the very peer interactions that protect them against late-life isolation and depression.
Keeping an autonomous personal identity outside the family tree preserves emotional strength and purpose, especially during years when physical mobility begins to slow down.
🧭 The Strategic Grandparenting Blueprint
Audit Domicile and Estate Impact
Confirm the state-level death tax and property tax differences before exploring any geographic move.
Calculate Real Estate Friction
Weigh the loss of Section 121 exclusions and basis step-ups against buying an overpriced suburban home.
Establish an Annual Travel Fund
Allocate $35,000 to $60,000 per year exclusively for flights, private vacation rentals, and family retreats.
Subsidize Third-Party Support
Pay directly for au pairs, private tutoring, and camp fees to support adult kids without sacrificing autonomy.
Gifting Travel Creates Stronger Memories Than Moving
Underwriting curated annual family getaways builds far deeper, lasting relationships with grandchildren than showing up for rushed weekday carpools in a suburban cul-de-sac.
Directing an annual travel budget of $35,000 to $60,000 toward private villa rentals or multi-generational resort stays creates uninterrupted, memorable time together. Dedicated trips remove the chore-heavy friction of ordinary domestic life, allowing grandparents to connect with family in an environment where everyone is rested and present.
Capital spent on shared experiences outperforms real estate transactions.
Pairing these trips with targeted financial support – such as funding 529 college savings plans, paying for specialized tutoring, or covering summer camps – delivers immense relief to adult children. This targeted deployment of balance-sheet strength provides substantial multi-generational support while protecting your legal domicile, long-held real estate basis, and everyday personal autonomy.
You establish a reputation for generosity and create lifelong memories with grandchildren without surrendering your home, your social world, or your financial independence.
Frequently Asked Questions
What if my adult children genuinely need financial help with childcare?
The most effective move is paying the childcare provider or nanny agency directly from your cash flow. Direct payments solve their practical stress immediately, keep your personal calendar open, and do not trigger federal gift tax reporting when structured cleanly.
How does keeping my original home help my heirs with taxes?
When you retain an appreciated primary residence until death, your heirs receive a step-up in basis to the current fair market value. This completely wipes out the embedded capital gains tax on decades of appreciation, saving hundreds of thousands of dollars in taxes.
Is a $35,000 to $60,000 annual travel budget really cheaper than moving?
Yes. Real estate sale commissions, transfer taxes, capital gains hits, and $28,000 annual suburban property taxes on a $2,200,000 replacement home easily exceed several hundred thousand dollars over a decade. Travel gives you total flexibility without liquidating capital.
What if our health declines and we need family support nearby?
If severe health challenges arise, hire top-tier private home health aides in your current community where your medical specialists are already established. Physical relocation should only occur when continuous acute clinical care or specialized memory care dictates it.
Evaluating Domicile Taxes and Travel Funding Before Moving
Keep your legal domicile and long-held real estate intact whenever state estate tax thresholds and capital gains liabilities exceed the utility of physical proximity. A permanent geographic move is warranted when personal care requirements outstrip independent living, never as an unstated convenience for daily family logistics.
Deploy an annual $35,000 to $60,000 travel budget to fund intentional, memorable visits instead. You protect your medical network, your community, and your compounding wealth while resisting social comparison and giving your family your very best presence.
Audit Your Estate's Cross-State Tax Exposure
Review Section 1 and run your assets against your children's state exemption limits before considering a real estate listing.