I nearly burned through two years of travel savings covering a lease my adult child could not sustain, learning the hard way that retirement money does not recover. When your income drops to replacing 70% to 80% of former earnings and Medicare Part B premiums come straight off the top of Social Security, spare cash evaporates quickly.
Your retirement capital is not an emergency fund for grown children.
Whether facing a request for a $5,000 to $25,000 debt bailout or uncontracted housing, saying yes without limits destroys your solvency. You do not have working years left to rebuild depleted balances. Drawing five clear financial boundaries keeps your nest egg safe, offers healthy alternatives, and hands you an exact script to protect your independence without guilt.
Quick Tips Before You Start
Separate Love from Money
Saying no to debt obligations is an act of long-term protection for the whole family.
Put Everything in Writing
Define household contributions and move-out target dates before anyone moves boxes into your spare room.
Lock Down Your Nest Egg
Never liquidate tax-advantaged retirement accounts to clear an adult child's consumer debt.
Use Official Designations
Rely on durable power of attorney and payable-on-death beneficiaries instead of joint account ownership.
1. Co-Signing Any Loan Puts Fixed Incomes at Risk
Sitting across a dealership desk to co-sign an auto loan feels like harmless support, but the signature binds your fixed income to 100% of that balance without giving you the vehicle title.
When a missed payment hits, creditors pursue your retirement income directly and sink your credit score overnight. That extra liability inflates your debt-to-income ratio, locking you out of personal borrowing when unexpected roof repairs or medical bills strike your own household.
You are allowed to say no to legal liability while offering a modest, one-time cash gift of $300 from your annual discretionary budget instead.
💡 Tip: Offer to pay for a professional session with an accredited credit counselor rather than putting your name on the loan application.
2. Open-Ended Housing Without Shared Costs Drains Cash
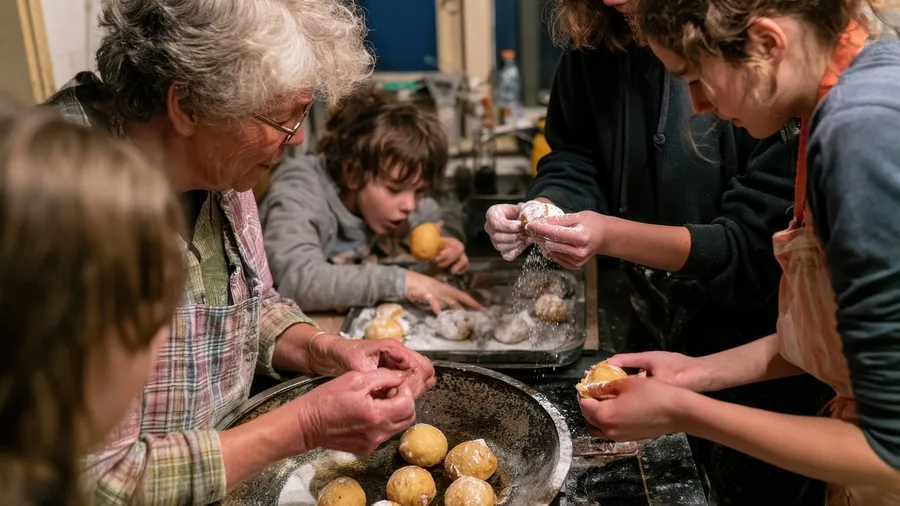
Opening your door to a child in trouble is an act of love, not a parenting failure. But absorbing another adult into your home without a clear timeline can quietly wreck a fixed retirement budget.
What begins as a two-week reset frequently stretches into a six to eighteen month stay. During that time, daily grocery spending jumps, utility meters run constantly with extra laundry and heating, and household overhead expands fast enough to swallow whatever cushion your monthly pension or Social Security provides.
An open-ended welcome creates a lingering financial drain.
Protect your cash flow by putting terms on paper before the moving boxes arrive. Draft a straightforward household agreement that sets a firm six- to twelve-month move-out date, alongside a set monthly contribution of $150 to $300 toward utilities and food. Setting the deadline immediately prevents months of drift.
Paying for every meal and bill does not protect your child; it stops them from building their own emergency cash reserve. Structure keeps their independence on track while keeping your grocery bill intact.
Boomerang Housing Ground Rules
Unspoken Assumptions (The Risk)
- Payment timing: Vague 'as-needed' cash help that rarely materializes
- Incidental costs: Parent absorbs phone plans, auto insurance, and subscription tabs
- Space boundaries: Household common areas and garage filled without limits
- Stalled progress: Missed apartment search goals carry zero clear consequences
Operational Contract (The Guardrail)
- Payment timing: Automated cost-share transfer scheduled on the 1st of the month
- Incidental costs: Child maintains separate auto coverage, phone bills, and loan payments
- Space boundaries: Defined private room limits with off-site storage for excess belongings
- Stalled progress: Scheduled 90-day savings reviews paired with a written 30-day notice clause
3. Retirement Account Withdrawals for Bailouts Cause Irreversible Damage
Watching your child carry crushing credit card balances brings an unbearable urge to fix the problem instantly. You have savings parked in a retirement fund, and writing one rescue check feels like pure parental mercy.
Pulling $5,000 to $25,000 from a traditional IRA or 401(k) triggers severe structural consequences. That withdrawal is taxed as ordinary income, which can push you into a higher tax bracket and spark steep surcharges on your monthly Medicare Part B premiums. Even worse, that withdrawn principal permanently loses all future market growth.
You cannot replace those tax-advantaged funds without earned income.
If you want to offer relief, start with a tiny, zero-risk gesture rather than raiding your nest egg. Pay $50 directly toward their credit counseling consultation, or gift $100 toward a single monthly minimum payment from your existing checking buffer. That small start offers real support without risking your long-term security.
Never compromise your own basic retirement solvency to wipe away someone else's short-term consumer debt. Your nest egg must fund your living expenses for the rest of your life.
💡 Tip: A one-time emergency gift should never exceed 2% of your total liquid cash reserves outside of dedicated retirement funds.
The True Cost of a $20,000 Retirement Bailout
4. Unpaid Daily Childcare Turns Retirement into Unfunded Labor
Forty hours a week of infant care is not babysitting.
Taking on structural childcare to save an adult child $1,200 to $2,500 every month in commercial daycare quietly turns your retirement into an uncompensated second career. What starts as a short-term favor rapidly becomes a rigid schedule that eliminates personal flexibility, blocks long-planned travel, and places continuous physical strain on aging joints.
Unpaid care also introduces invisible cash drains. Preparing daily meals, driving to activities, and paying park admissions easily adds $200 to $400 in unbudgeted monthly costs to a fixed Social Security income.
Daily child-rearing costs belong entirely on the parent's ledger.
Take willpower out of the equation by setting an automated, non-negotiable schedule before care begins. Limit your availability to one or two fixed days each week, such as Tuesdays and Thursdays from 9 a.m. to 1 p.m., leaving the remaining weekdays strictly closed so the parents maintain their own primary childcare systems.
Require parents to provide all physical supplies in advance. Every box of diapers, container of formula, meal ingredient, and activity fee must be purchased directly by them before drop-off.
Never use your fixed income to fund their household supplies.
Putting these boundaries on a clear, unchanging calendar protects your physical stamina and stops quiet spending leaks. It keeps your relationship with your grandchildren warm and voluntary, rather than turning your retirement into an unpaid daycare center that drains the finite financial cushion you spent decades building for your own later years.
💡 PRO TIP
The Care Schedule Formula
Commit only to fixed hours that leave at least three full weekdays entirely free for your own medical appointments, fitness routines, and personal rest.
5. Adding Children to Deeds or Bank Accounts Creates Legal Exposure
Putting an adult child on your property deed or checking account exposes 100% of those assets to their personal liabilities. If they face a divorce, unpaid tax lien, or personal bankruptcy, your money becomes fair game for their creditors.
Deeding your home to a child during your lifetime also forfeits the step-up in basis tax rule, landing them with massive capital gains taxes when the house is eventually sold. Instead, implement a clean two-part system: set up payable-on-death designations at your bank for immediate asset transfer, and establish a durable financial power of attorney to manage bills if you become incapacitated.
This system protects your ownership while bypassing probate without tax penalties.
⚖️ Step-by-Step Asset Protection Framework
Name Payable-on-Death Beneficiaries
Register designated beneficiaries on all bank and brokerage accounts to bypass probate instantly.
Execute Durable Power of Attorney
Grant a trusted child legal authority to pay bills during medical incapacitation without co-mingling funds.
Retain Sole Real Estate Ownership
Keep property deeds in your name to preserve the full step-up in tax basis for your heirs.
Review Estate Plans Annually
Verify beneficiary designations with an estate planning attorney whenever major family life changes occur.
Frequently Asked Questions
What should I say when my child asks me to co-sign an auto loan?
Tell them calmly that your fixed retirement budget does not permit taking on contingent debt obligations. Explain that lenders view co-signing as an active liability on your credit report, which blocks your ability to handle personal home or medical emergencies.
How much can I safely gift my adult child each year?
Gifts must come entirely out of your annual discretionary budget, not principal investments. As long as you stay within the federal annual gift tax exclusion limit, you owe no gift taxes, but you should never give cash that compromises your emergency reserves.
Why is a payable-on-death designation better than a joint bank account?
A payable-on-death designation transfers the account balance to your beneficiary only after death, keeping the funds 100% shielded from your child's creditors, lawsuits, and divorce proceedings during your lifetime.
How do I transition full-time grandchild daycare back to the parents?
Give them a firm 30-day notice explaining that the physical and daily demands are no longer sustainable for your health. Offer a reduced, fixed schedule of one day per week to help bridge the transition while they secure commercial daycare.
What if my child truly faces eviction or a financial emergency?
If you choose to help, pay the landlord or utility company directly as a one-time gift rather than handing over unrestricted cash. Make it clear in writing that this is a single occurrence and connect them with local credit counseling resources.
Delivering Firm Boundaries With Empathy and Clarity
When a child asks for a rescue, use a clear three-step response. Validate their stress, state the boundary plainly ('My fixed retirement income cannot absorb loans, withdrawals, or co-signing'), and redirect them to outside help by offering to fund a session with an accredited non-profit credit counselor.
Your budget is calibrated to replace 70% to 80% of former earnings; eroding that foundation risks your basic living stability. Protecting your nest egg is not abandonment. Refusing that lease bailout or co-signature today is what guarantees you will never become a financial burden to your children tomorrow.
Audit Your Account Beneficiaries Today
Review your bank and brokerage accounts this afternoon to confirm payable-on-death designations are active and up to date.