I spent years assuming a modest home and a small pension disqualified my family from Medicare premium assistance, letting thousands of dollars slip away. You might be making that exact same assumption right now.
Surging property assessments, prescription copays, and seasonal utility spikes routinely crush fixed retirement budgets, while billions in public funds sit untouched every year. These statutory programs are not reserved solely for severe poverty – specialized senior rules permit generous medical expense deductions and protect home equity, opening qualification to middle-income households.
Knowing the precise statutory mechanics lets you halt improper monthly deductions and lock in recurring cost reductions. You do not need to apply for everything today to win back breathing room.
Quick Tips Before You Start
Gather Documentation
Keep recent tax returns, bank statements, utility bills, and out-of-pocket medical receipts in one folder.
Exclude Your Primary Home
Most assistance programs do not count your primary residence or one vehicle toward liquid asset caps.
Track Medical Receipts
Unreimbursed medical expenses over $35 monthly can deduct directly from gross income on several applications.
Apply in Priority Sequence
Tackle monthly recurring deductions like Medicare Part B first before moving to seasonal or one-time grants.
Healthcare and Prescription Savings
Healthcare overhead represents the largest unpredictable cost center in retirement. Standard Medicare coverage leaves substantial gaps in monthly cash flow through premiums, deductibles, and tiered drug copayments.
Federal statutory programs exist specifically to absorb these costs for seniors with moderate incomes, returning hundreds of dollars directly to monthly Social Security disbursements.
1. Medicare Savings Programs Pay Your Part B Premiums
Exactly $174.70 vanishes from the standard monthly Social Security payment before it ever reaches your checking account.
State Medicaid offices run four distinct Medicare Savings Programs – QMB, SLMB, QI, and QDWI – that stop that bleed. The Qualified Medicare Beneficiary track pays your Part A and B premiums while picking up all deductibles and copays, while SLMB and QI specifically cover the base Part B charge to hand back $2,096.40 every year.
Check your annual Social Security award letter every January. If that Part B line is still deducted, submit an application directly to your state social services office so they can order Social Security to stop taking the money.
💡 Tip: Audit your Social Security benefit statement annually each January to verify the Part B deduction has stopped once approved.
| Benefit Program | Primary Value Provided | Key Eligibility Trigger | Where to Apply |
|---|---|---|---|
| Medicare Savings Programs | Pays $174.70/mo Part B premium plus copays | Income near or below 135% federal poverty level | State Medicaid / Social Services Department |
| Extra Help (Part D Subsidy) | Caps drug copays at $4.50 generic, $11.20 brand | Income up to 150% FPL; asset limits apply | Social Security Administration (SSA.gov) |
| State Pharma Programs (SPAP) | Wraps Part D coverage for non-formulary drugs | State-specific income limits above Medicaid | State Department of Health or Aging |
| VA Aid and Attendance | Monthly tax-free cash add-on to VA pension | Wartime service plus daily living assistance need | VA.gov or accredited Veterans Service Officer |
| Senior Property Tax Relief | Freezes home assessment or exempts valuation | Age 62-65+ owning primary residence | County Tax Assessor / Municipal Appraisal Office |
| USDA Section 504 Grants | Up to $10,000 grant for health/safety repairs | Age 62+, rural area, income below 50% AMI | USDA Rural Development local office |
| LIHEAP Energy Assistance | Direct utility bill credits for heating/cooling | Household income up to 150% FPL or 60% SMI | Local Community Action Agency |
| Weatherization Assistance | Free home insulation, air sealing, furnace repair | Income below 200% FPL or SSI/LIHEAP receipt | Regional Community Action Agency |
| Senior SNAP Rules | Monthly grocery funds loaded on EBT card | Age 60+ deducting medical costs over $35/mo | State SNAP / Social Services office |
| Senior Farmers Market (SFMNP) | Free seasonal produce coupons ($20-$50) | Age 60+ with income below 185% FPL | Local Senior Center or Area Agency on Aging |
| Lifeline Program | Monthly discount of $9.25 on phone/internet | Income below 135% FPL or Medicaid/SNAP enrollment | CheckLifeline.org (National Verifier) |
| Area Agencies on Aging | Free rides, respite care, home-delivered meals | Age 60+ with social or economic need | Eldercare Locator (1-800-677-1116) |
| SCSEP Training Program | Paid part-time community training at minimum wage | Age 55+, unemployed, income below 125% FPL | Department of Labor SCSEP grantee |
| America the Beautiful Pass | Lifetime entry to 2,000+ federal recreation sites | Age 62+ US citizen or permanent resident | Store.usgs.gov or in person at federal parks |
2. Extra Help Slashes Prescription Drug Copays
I watched a neighbor skip daily medication over an $85 copay.
Outpatient doctor visits are only half the battle when prescription costs quietly drain your checking account each month. The Social Security Administration runs the Extra Help program, officially known as the Part D Low-Income Subsidy, designed to eliminate standard plan deductibles, remove late enrollment penalties, and close the dangerous coverage gap entirely.
Skipping necessary doses is never a personal budgeting failure.
Under this benefit, your out-of-pocket prescription prices drop dramatically to no more than $4.50 for generic medications and $11.20 for covered brand-name drugs at the pharmacy counter. The program also pays your baseline monthly Part D plan premium, freeing up cash flow that would otherwise disappear into recurring insurance overhead.
Federal qualification guidelines extend up to 150% of the federal poverty line. Total asset caps reach $17,220 for individuals and $34,360 for married couples, leaving retirement homes and primary vehicles completely protected from the calculation.
You do not need to finish everything in one sitting.
If digging through years of bank statements feels exhausting this week, give yourself permission to take just one small step. You can submit Form SSA-1020 directly by mail or complete a simplified online screen at SSA.gov, and you will never need to switch your current doctors or insurance carriers to qualify.
Filing that single document establishes an official application date, allowing you to secure immediate pharmacy savings without forcing yourself to resolve every administrative headache at once.
💡 PRO TIP
Keep Current Part D Coverage Intact
Applying for Extra Help or State Pharmaceutical Assistance Programs does not require changing your private insurance carrier or re-enrolling in a new drug plan.
3. State Pharmaceutical Assistance Programs Fill Formulary Gaps
Many retirees assume that once Medicare Part D denies a specialized prescription, paying full retail price out of pocket is their only remaining option.
That costly assumption leaves valuable assistance untouched.
When standard coverage leaves high-tier drugs unfunded, State Pharmaceutical Assistance Programs step in. Operating across roughly two dozen states, these secondary wrap-around plans pay remaining coinsurance, copayments, and excluded maintenance medications that would otherwise drain monthly checking accounts or force seniors to ration critical daily pills.
The common mistake is assuming you earn too much. State legislatures set their own financial thresholds independently, creating income limits substantially higher than restrictive federal Medicaid rules to protect middle-income retirees.
To claim this coverage, submit your financial documentation directly to your state department of health or department of aging. Once approved, the state program integrates behind your Part D plan to absorb out-of-pocket charges before you ever reach the pharmacy cash register.
4. VA Aid and Attendance Pays Monthly In-Home Care Stipends
The VA Aid and Attendance benefit adds tax-free cash directly to your monthly pension.
Qualifying requires 90 days of active duty with at least one wartime day, an honorable discharge, and clinical proof of needing help with bathing, dressing, or prosthetics. You do not need low starting income: unreimbursed care expenses are subtracted directly from your gross pension during eligibility calculations.
Start simply by gathering your discharge papers and one doctor verification note. Accredited Veterans Service Officers or VA.gov file the entire claim for free, so avoid fee-charging consultants.
💡 Tip: Never pay a commercial service to file a VA pension claim; accredited VSOs provide free, legally protected assistance.
Retiree Benefit Terms Decoded
Housing and Utility Relief
Escalating residential assessments and energy utility rate hikes place intense pressure on fixed retirement income. Owning a home clear of a mortgage does not protect you from sharp increases in local municipal taxes or heating costs.
Statutory protections exist to cap property taxes, fund essential structural renovations, and offset seasonal energy bills without placing liens on your home.
5. Senior Property Tax Freezes Halt Assessment Increases
Few things cause sharper monthly anxiety on a fixed income than watching property taxes rise on a home you already spent thirty years paying off.
Local tax jurisdictions offer three primary relief structures: valuation freezes, homestead percentage exemptions, and property tax deferrals. An assessment freeze locks your home's taxable value at a baseline year, stopping real estate market surges from triggering higher tax bills. Deferrals postpone payments entirely until property sale, protecting your liquid cash.
The trade-off involves local paperwork and eventual liens.
Qualification requires primary homeownership, an age threshold starting at 62 or 65, and strict county income caps. Deferrals accumulate interest that your estate settles later, while freezes require tracking down documentation and submitting applications directly to your county tax assessor or appraisal district rather than state revenue departments.
Enduring that bureaucratic filing process protects your financial independence. Freezing your taxable assessment locks in manageable housing costs, keeping local property tax hikes from slowly pricing you out of your community.
6. USDA Section 504 Grants Fund Urgent Home Repairs
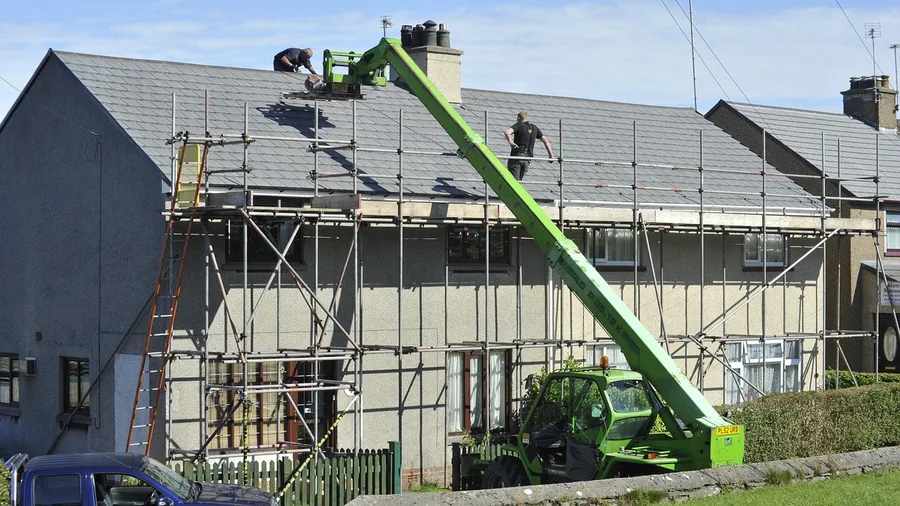
A leaking roof or failing furnace does not mean you must sell your home or drain your remaining emergency savings.
The USDA Section 504 Home Repair system provides outright grants up to $10,000 to eliminate physical hazards. Homeowners aged 62 and older qualify by living in designated rural towns under 35,000 residents with household income below 50% of the area median. Funds cover roof replacements, heating systems, and wheelchair ramps.
The process follows three clear steps: check your property on the USDA map, collect licensed contractor estimates, and apply. The award requires zero repayment unless you transfer ownership within three years.
7. LIHEAP Offsets Heating and Cooling Energy Bills
Stop treating surging seasonal utility bills as an unavoidable fixed cost of keeping your home livable when summer heat waves or freezing winter cold snaps roll through.
A common misconception among older adults is that drawing a steady pension or owning a home outright disqualifies them from public utility relief. In truth, the federally funded Low-Income Home Energy Assistance Program (LIHEAP) issues direct payments to utility companies, crediting your electric, natural gas, heating oil, or propane account to erase unpaid balances.
Seniors receive first access to these state funds.
Most state agencies establish prioritized early-intake windows every autumn specifically for households with members aged 60 and older, weeks before the general public can apply. That head start prevents missed deadlines. For urgent emergencies, dedicated crisis intervention grants provide rapid payments during deep freezes or extreme summer spikes to stop disconnections or restore shut-off power.
Call your local social services office or community action agency before winter begins, and have your utility billing history and proof of income ready to claim your prioritized household allocation.
💡 Tip: Contact your local Community Action Agency during autumn early-intake windows to submit heating assistance paperwork before general public deadlines.
8. Weatherization Assistance Makes Homes More Energy Efficient
The federal government pays to upgrade the physical energy efficiency of older homes at zero cost to qualifying low-income seniors.
While temporary bill credits help clear immediate utility balances, drafty windows and uninsulated attics drain fixed retirement budgets year after year. The Department of Energy funds the Weatherization Assistance Program (WAP) to permanently fix these structural problems by funding complete residential efficiency retrofits for eligible homeowners as well as qualifying renters.
Application waitlists grow significantly longer every winter.
Submitting your paperwork now locks in your position before seasonal demand stretches local contractor schedules out for several months. Certified technicians begin the retrofit process by conducting a diagnostic blower-door energy audit to locate exact air leaks, measuring thermal loss through ceilings, wall cavities, floorboards, and loose exterior door frames throughout the entire structure.
Contractors then install dense wall insulation, add weatherstripping, seal drafty ductwork, and tune or replace aging furnaces that no longer heat the home safely or efficiently.
Existing benefit enrollment skips the income verification step entirely.
If anyone in your household receives Supplemental Security Income (SSI) or qualified for LIHEAP energy aid, you are automatically income-qualified for the weatherization program. That automatic qualification allows you to bypass redundant financial paperwork and enter the project queue without collecting prior tax returns or extensive bank statements.
Regional Community Action Agencies manage enrollment and supervise construction crews locally, so calling your county office this week starts the process before severe temperatures drive up next season's utility costs.
WAP Standards — Guidelines & Limits
📋 Income Ceiling
At or below 200% federal poverty line
📝 Renter Rule
Landlord written consent required
📉 Average Savings
$372/year reduction on utility costs
📁 Standard Filing
Deed or lease plus 12 months of energy bills
Service Limitation
Homes improved through the program within the last 15 years cannot receive a second federally funded retrofit.
Food Security and Daily Living
Nutritional support and communication infrastructure form the foundation of independent living in retirement. High food prices force many seniors to sacrifice fresh produce and balanced meals.
Specialized statutory rules for older adults relax asset tests and allow broad medical expense deductions, making food and connectivity benefits widely accessible.
9. Senior SNAP Uses Relaxed Medical Deduction Rules
Do not let the fear of being turned down keep you from applying for grocery assistance, even if your gross monthly income seems slightly too high on standard state charts.
The Supplemental Nutrition Assistance Program (SNAP) uses special budgeting rules for households with adults aged 60 and older, allowing you to deduct out-of-pocket medical costs over $35 a month – like Medicare premiums, prescription copays, and dental bills – directly from your gross income. In most states, your primary home, car, and retirement savings do not count toward asset caps.
Approved grocery funds load automatically each month onto a discreet Electronic Benefits Transfer (EBT) card, which swipes just like a regular debit card at supermarket checkout registers.
10. Senior Farmers Market Programs Provide Fresh Produce Vouchers
Between May and October each year, federal and state programs distribute coupon booklets worth $25 to $50 in direct purchasing power to qualifying adults aged 60 and older.
The Senior Farmers' Market Nutrition Program issues these vouchers to buy fresh fruits, vegetables, culinary herbs, and honey directly from authorized roadside stands, community-supported agriculture programs, and local farmers' markets. Because this assistance runs completely separately from monthly SNAP grocery funds, using these seasonal coupons will never reduce or alter your standard food benefits.
It is entirely separate food money.
Because local program allocations are limited, booklets are handed out on a first-come basis through neighborhood senior centers, congregate meal sites, and Area Agencies on Aging. Call your local senior center coordinator or county aging office to verify regional income cutoffs and find the exact dates distribution starts near you.
A ten-minute phone call with an agency intake specialist confirms your paperwork and gets your name on the distribution list before county allotments run out for the summer.
Nutrition Benefit Comparison
Senior SNAP Benefits
- Year-round monthly electronic deposits
- Deducts medical costs exceeding $35/month
- Accepted at supermarkets and grocery stores
- Allows ownership of primary home and vehicle
Senior Farmers Market (SFMNP)
- Seasonal coupon distribution (May to October)
- Income threshold up to 185% poverty level
- Exclusively redeemable at certified farm stands
- Operates alongside SNAP without offsetting funds
11. Lifeline Discounts Reduce Monthly Cell and Broadband Bills
The federal Lifeline program applies a recurring discount directly to your existing landline, mobile phone, or home broadband internet bill.
Approved households receive a monthly subsidy of up to $9.25, which increases to $34.25 for residents on federally recognized Tribal lands. If you already receive Medicaid, SNAP, Supplemental Security Income, Federal Public Housing Assistance, or a Veterans Pension, you qualify automatically without submitting pay stubs or tax forms.
Complete the one-time registration at CheckLifeline.org or mail a paper form to the Universal Service Administrative Company, and your carrier applies the credit to every future bill.
12. Area Agencies on Aging Fund Respite and Free Transportation
Many retirees assume local supportive aid requires poverty-level income, Medicaid enrollment, or the complete spend-down of personal savings before help becomes available for daily needs.
In reality, the Older Americans Act funds a nationwide network of local Area Agencies on Aging that deliver direct community support to adults aged 60 and older without strict means-testing. Because these programs focus on functional independence rather than rigid asset caps, owning a home or receiving a pension will not disqualify you from local relief.
Support is based on daily need, not your net worth.
Core agency programs provide free rides to non-emergency medical visits, home-delivered food through Meals on Wheels, minor household chore support, and adult day care respite hours for family caregivers. Enrolling in these local services removes hundreds of dollars in recurring monthly transit, grocery, and caregiving overhead from a fixed budget.
Visit the federal Eldercare Locator at eldercare.acl.gov or call 1-800-677-1116 this week to connect directly with your regional agency specialist and schedule your free intake screening.
Supplemental Income and Recreation
Maintaining social engagement and professional skills provides significant cognitive and financial benefits throughout retirement.
Federal initiatives support older adults who want to re-enter the workforce part-time or explore national public lands at heavily discounted rates.
13. SCSEP Pays Seniors for Part-Time Community Job Training
Stepping back into the workforce after years away feels deeply intimidating.
When recurring bills outpace a fixed income, taking on an exhausting forty-hour workweek is rarely realistic or desirable. You do not have to jump into high-stress roles just to generate practical financial breathing room.
The federal Senior Community Service Employment Program finances paid, part-time training assignments for unemployed adults aged 55 and older inside local non-profits, public schools, and community hospitals. Participants train roughly 20 hours weekly earning the highest applicable minimum wage, with eligibility set at 125% of the federal poverty level and priority designated for veterans.
A light schedule builds momentum without overwhelming your weekly routine.
Host organizations deliver structured computer literacy instruction, individualized resume polishing, and interview coaching during your regular paid hours. That practical framework provides a clear bridge to permanent, unsubsidized jobs, allowing you to modernize your workplace capabilities and collect steady supplemental pay without sacrificing all your free time or running yourself ragged.
🗺️ Four Steps to Claim Your Retiree Benefits
Audit Monthly Healthcare Outflows
Check your Social Security statement for Part B deductions and review yearly prescription drug copays.
Screen via BenefitsCheckUp
Run your household finances through the National Council on Aging's confidential online screening tool.
Contact Regional Agencies
Reach out to your local Area Agency on Aging and Community Action Agency for direct enrollment support.
File Applications in Priority Order
Submit paperwork for Medicare Savings Programs and property tax freezes before seasonal grant deadlines.
14. Lifetime Senior National Park Passes Cut Travel Costs
You build your outdoor recreation around the America the Beautiful Senior Pass instead of paying retail gate admissions at every regional destination. This single federal credential grants permanent entry to more than 2,000 public recreation sites managed by the National Park Service, US Forest Service, Fish and Wildlife Service, and Bureau of Land Management nationwide.
Any US citizen or permanent resident aged 62 or older can purchase an annual pass for $20 or lock in a lifetime pass for a single, one-time fee of $80.
Treat the pass as a whole-car discount system whenever you plan driving routes with family or friends. At standard gate checkpoints charging per-vehicle entry, the pass admits you and every passenger in your non-commercial vehicle, while per-person fee areas admit the cardholder alongside up to three accompanying adults at zero additional cost.
Visiting two major parks covers the entire lifetime fee.
The secondary tier of the pass cuts overnight travel expenses even further. Cardholders receive a direct 50 percent discount on selected expanded amenity fees, slicing standard charges in half for federal campsite reservations, boat launch facilities, and designated guided tours, which turns extended seasonal camping trips into remarkably cheap vacations.
Purchasing the pass in person at a participating federal recreation site avoids the extra $10 mail-processing charge, keeping your total cash outlay at flat face value for decades of travel.
Highest-Impact Relief Programs Ranked
Frequently Asked Questions
Will claiming these benefits reduce my monthly Social Security payments?
No. Claiming public assistance programs, property tax freezes, or energy grants will never reduce your earned Social Security retirement benefits. In fact, Medicare Savings Programs increase your monthly net check by eliminating the standard Part B deduction.
Does owning a home disqualify me from assistance programs?
For almost all of these programs, your primary residence and one personal vehicle are completely exempt from asset determinations. Programs like USDA Section 504 and municipal property tax freezes specifically require primary homeownership to qualify.
How do medical expenses help me qualify for food assistance?
Under specialized senior SNAP budgeting rules for adults aged 60 and older, unreimbursed out-of-pocket medical costs exceeding $35 per month deduct directly from your gross income, significantly lowering your countable income to meet eligibility limits.
Can I receive both SNAP and Senior Farmers Market coupons?
Yes. The Senior Farmers Market Nutrition Program operates entirely independently of SNAP. Enrolling in SFMNP provides additional produce vouchers without reducing or offsetting your monthly food stamp balance.
Where can I get free, unbiased help applying for these programs?
Contact your local Area Agency on Aging through the federal Eldercare Locator at 1-800-677-1116. Regional agencies provide certified benefits counselors who assist with application paperwork at zero charge.
Claiming Your Unclaimed Retiree Benefits Today
These programs are legal entitlements built through decades of tax contributions, not charitable favors. Walking away from them only leaves your own hard-earned money in government accounts.
Run your financial details through the National Council on Aging's free tool at BenefitsCheckUp.org or contact your regional Area Agency on Aging. Submitting paperwork for Medicare Part B relief and local property tax freezes first guarantees your next monthly statement reflects the savings you earned.
Check Your Benefit Eligibility Today
Review our summary table above to identify the highest-value programs for your household, then contact your regional Area Agency on Aging to start your applications.