You probably believe that building wealth requires a massive executive salary, picking winning stocks, or waiting until you make enough to finally start saving.
I lived that trap for an entire decade. I carried $12,000 in revolving credit card debt while buying a new car every three years on an escalating income, convinced each raise would magically fix my cash deficits. It never did; rising earnings only expanded my baseline overhead.
True financial security comes from capturing the gap between your income and spending early, keeping a liquid cash cushion, and quietly funneling automated contributions into broad-market index funds.
Decide on three moves right now: capture your next raise before lifestyle absorbs it, automate one index fund contribution, and eliminate predatory interest.
Quick Tips Before You Start
Pause Big Purchases
Apply a strict 48-hour cooling-off rule on every non-essential purchase over $100.
Separate Your Cash
Keep your emergency savings at a different bank so you never spend it impulsively.
Automate Payday
Schedule investment transfers for the morning your paycheck arrives, not the month end.
Slash Account Fees
Audit workplace retirement holdings to pick index funds with expense ratios below 0.10%.
Earning and Spending Truths
Your earning power means nothing if your lifestyle inflates at the exact same pace. The first battle in personal finance is capturing the gap between what lands in your bank account and what leaves it every single month.
1. Income growth fails when spending expands to match it
Feeling squeezed after getting a raise does not mean you failed; it just means fixed overhead expanded before you noticed.
When my pay climbed from $45,000 to $90,000 before age thirty-five, every extra dollar vanished into pricier apartment leases, streaming bundles, and newer car loans, leaving my net accumulation at zero. If your baseline obligations rise dollar-for-dollar with your paycheck, higher earnings buy zero long-term security.
Run a quick check-in whenever your compensation changes: divert a minimum of 50 percent of that net raise directly into savings and investment accounts before adjusting your monthly living expenses.
Pay Raise Allocation Priority
- Direct 50% into automated index investments and debt payoff — Lock in long-term compounding before lifestyle inflation takes hold.
- Assign 25% to core baseline cost adjustments — Absorb real inflation on groceries and utilities without lifestyle creep.
- Absorb 100% of the raise into new recurring car loans and leases — Guarantees your net worth stays flat regardless of career success.
2. Buying things to impress peers is your costliest mistake
We instinctively treat visible possessions as proof of prosperity, but luxury vehicles and designer goods simply trap your cash in rapidly depreciating assets. I made that exact mistake, financing three consecutive new vehicles in nine years to match the office parking lot, pushing my retirement contributions all the way back to age thirty-eight.
Status symbols rarely equal genuine balance sheet strength.
Lasting security is invisible: paid-off balances, unencumbered assets, and liquid runway that peers never see. To take willpower out of the equation and stop comparison spending, automate a friction rule. Program a mandatory 48-hour cooling-off waiting period for any non-essential purchase over $100 by locking shopping apps or delaying card entry.
Walk away from the checkout screen for two full days. That brief buffer reliably dismantles the social urge, helping your money buy long-term autonomy instead of fleeting approval from people who are not paying your bills.
⚠️ COMMON MISTAKE
The Upgraded Commute Trap
Trading in a reliable car for a $600 monthly auto loan destroys your cash margin. A five-year car payment invested in a basic market index fund instead historically builds tens of thousands in net worth.
3. A reliable cash cushion prevents predatory borrowing
An unexpected $1,500 car repair without cash behind it will quickly turn into years of double-digit credit card interest or high-fee personal loans.
That is why my personal benchmark is a target emergency fund of six months of bare-bones living expenses – exactly $18,000 parked in a dedicated high-yield savings account. Liquid cash is not meant to make you wealthy through investment yields; its true job is pure risk insulation and debt prevention.
Build toward three to six months of basic survival costs, keeping the funds separate from daily checking so unexpected emergencies never derail your stability.
The Cash Cushion — Operating Rules
🏁 Phase 1 Milestone
Bank a $1,000 Starter Floor First
⚠️ Qualifying Trigger
Income Loss or Critical Health Needs
🔄 Replenishment Protocol
Pause Extra Investing Until Refilled
📈 When to Scale Up
Extend to 9 Months if Freelance or Commission
Failure Mode
Treating routine annual costs like vehicle registration as surprises drains the buffer prematurely.
Investing and Wealth Building
Building wealth does not require complex market timing or trading apps. The real engine of financial security is mechanical consistency, low expenses, and giving broad market index funds decades to compound.
4. Boring automated investing beats chasing market trends
At age thirty-eight, I finally closed out my speculative trading accounts after watching another hyped stock drop thirty percent in two weeks, wiping out months of hard-earned gains I could not afford to lose.
With my living expenses fully shielded by a dedicated cash reserve, I redirected that monthly surplus into an automatic transfer of $400 on every single payday directly into low-cost, broad-market index funds, tuning out every alarming headline about impending market crashes or economic recessions.
The transfer cleared every payday without my intervention.
My current net worth grew from that boring schedule alongside a paid-off primary residence, not from chasing individual tech stocks or attempting to outsmart market swings at the kitchen table.
Holding cash on the sidelines while waiting for the next market dip burns irreplaceable compounding days you cannot recover later. Securing real autonomy over twenty or more years requires owning the whole market through low-cost funds, letting broad economic growth do the heavy lifting while you leave the automated system alone.
⚙️ Automating Your Monthly Investment Engine
Direct Paycheck Split
Route your fixed monthly savings amount to clear into your account on payday morning.
Automate Account Transfer
Schedule an automatic pull from checking to your investment account for the following day.
Select Broad Index Funds
Set automatic purchase instructions into low-cost total stock or whole market funds.
Review Annually
Increase the monthly contribution percentage once a year when your salary adjusts.
5. Time in the market dwarfs starting contribution sizes
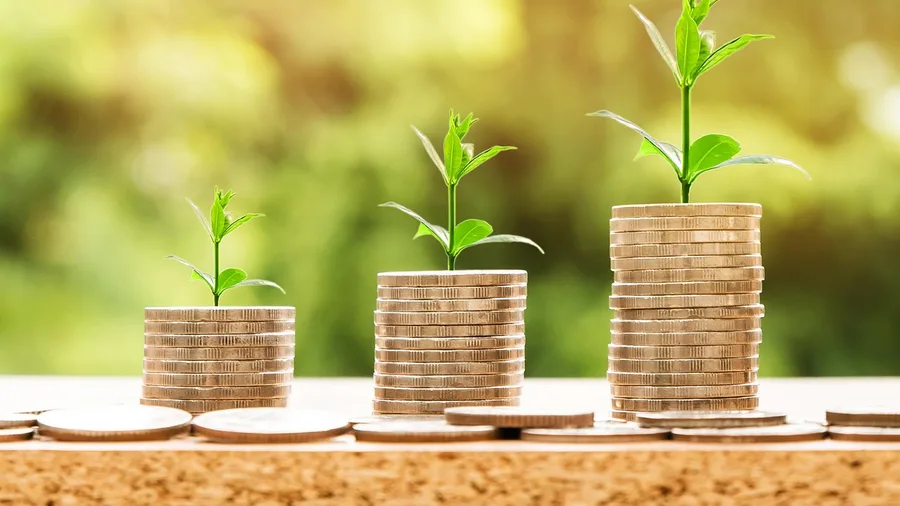
It is completely normal to look at an extra $50 remaining in your checking account and assume it is simply too small to make a meaningful difference.
The common mistake is waiting for a major salary bump or a perfect surplus before you begin investing, convinced that modest contributions are not worth the effort.
That delay costs more than anything else.
Putting a small sum into the market every month across thirty continuous years builds a larger final cushion than contributing twice as much money starting a decade later. The relentless mathematics of time and reinvested dividends do far more heavy lifting than the raw dollar size of any single paycheck deposit.
I discovered that penalty the hard way.
Starting my retirement investments at age thirty-eight meant I missed out on the easiest compounding years of my career, forcing me to jack up my savings rate north of 20 percent to compress the lost timeline. That required aggressive spending cuts that an earlier, tiny start would have prevented entirely.
Automating an immediate $50 monthly transfer creates the exact mechanical pipeline you need, embedding the habit into your cash flow before lifestyle creep claims the cash.
You do not need ideal conditions, deep market knowledge, or thousands of dollars to claim your share of economic growth. Commencing with fifty dollars right now puts the clock to work for you immediately, buying you future time and freedom that extra earned income later cannot match.
The Compounding Head Start
Comparing outcomes on steady index fund contributions
6. Fees and high-interest debt compound relentlessly against you
Audit your investment fees and credit card balances this afternoon to protect your long-term compounding from quiet leakage.
During my twenties, carrying $12,000 in credit card balances at 18 percent interest siphoned hundreds of dollars every month that should have been compounding for my future. Clearing credit statements in full stops that penalty, while moving away from retirement funds charging a 1 percent fee preserves nearly a quarter of your thirty-year wealth.
Check the expense ratios inside your workplace plan today and start shifting even small balances into low-cost index funds that charge near-zero ongoing fees.
💡 Tip: Paying your credit card balance in full every 30 days reduces your effective borrowing interest rate to zero.
Fee and Drag Audit Benchmarks
High-Drag Warning Signs
- Workplace fund expense ratios exceeding 0.25%
- Balances carried beyond the standard 25-day grace period
- Advisory or account wrap fees between 1.00% and 1.50%
- Incurring annual card fees with unused perks
Low-Cost Targets
- Broad-market core funds charging under 0.05%
- Auto-pay set to clear entire statement balance monthly
- Self-directed index accounts with zero ongoing platform fees
- Cash held in accounts earning competitive base yield
Mindset and Autonomy
The ultimate goal of money management is not luxury goods or showing off to colleagues. Money is a tool designed to buy you control over your calendar, peace of mind, and the physical vitality to enjoy your life.
7. Financial independence is about autonomy rather than luxury
Measure your financial standing in unbought time rather than the physical possessions you accumulate. Real security is the number of months or years you can survive without a paycheck.
When you funnel surplus cash into broad-market index funds and working toward a paid-off primary residence, regular employment quietly transforms from a survival necessity into optional work. Chasing visible luxury goods only inflates your ongoing overhead, whereas buying control over your own calendar permanently removes the baseline panic from your daily routine.
A cash cushion gives you immediate professional power.
Holding two or three years of basic living expenses completely changes how you carry yourself at work. You gain the practical ability to decline abusive working conditions, walk away from toxic managers, or transition toward higher-conviction work, because an employer no longer holds your rent and grocery money over your head.
Reaching that level of autonomy can feel distant when you are starting out, which tempts people to quit. If saving aggressively is squeezing your household too hard this year, give yourself permission to downshift.
Scaling an investment transfer down from $400 to $75 for six months is far better than abandoning the habit entirely. You do not need to sprint until you break; building independence is about steady accumulation that fits your current reality, keeping your accounts growing without draining your spirit today.
Even a small reserve of three months buys you the mental clarity to make deliberate choices rather than reactive, fear-based compromises.
Consistency over decades always beats temporary, punishing intensity.
💡 PRO TIP
The Freedom Metric
Calculate your Freedom Number: divide your total liquid savings by your monthly bare-bones expenses. That number is the exact count of months you own completely free from employer dependency.
8. Simplicity in your financial system prevents costly errors
You might think that building wealth requires specialized brokers, daily spreadsheet auditing, and half a dozen trading apps. In reality, juggling multiple speculative platforms only breeds decision fatigue and causes unforced administrative errors.
A reliable architecture requires only three core pieces: one primary checking account for payroll, one high-yield savings account for emergencies, and automated contributions to broad index funds. On every payday, automated transfers send money directly toward fixed bills, savings goals, and total market funds before any discretionary cash hits my pocket.
The obvious trade-off here is absolute, unglamorous boredom.
You give up the excitement of day trading and the satisfaction of discussing hot market plays with coworkers. What you get in return is a resilient routine that keeps operating smoothly during severe market drops, career changes, and family emergencies, completely removing human panic and mental strain from your financial life.
Trading away the illusion of being an active Wall Street trader is a small price to pay for a predictable system that runs without breaking for thirty consecutive years.
9. Health and relationships are your greatest balance sheet assets
Treat your physical body and personal relationships as the ultimate assets on your balance sheet. It is easy to obsess over account balances while ignoring chronic stress and neglected friendships.
Running yourself ragged to build a multi-million-dollar portfolio by age fifty-two is pointless if severe burnout and chronic illness prevent you from enjoying your freedom. Late-career medical expenses will quickly chew through neglected wealth, while no amount of compound interest can replace lost years with aging parents or growing children.
Money is simply an instrument to protect your health and spend unhurried time with loved ones. Allocate guilt-free cash for shared family experiences along the way.
Frequently Asked Questions
Is it too late to start investing in my 40s or 50s?
It is never too late. While starting at 40 or 50 means you have less compounding time than a 20-year-old, you likely have higher earning power. By aggressively controlling lifestyle inflation, taking advantage of federal catch-up contribution limits, and putting automated transfers into broad market index funds, you can build meaningful security over a 10 to 15 year window.
Should I pay off debt or build my emergency fund first?
Build a starter emergency fund of one month of living expenses first. Having that initial cash buffer ensures that when an unexpected car repair or medical bill happens, you do not have to put it on a high-interest credit card. Once that starter cushion exists, throw every extra dollar at non-mortgage debt charging over 8% interest.
How do I choose between paying off a mortgage and investing?
Mathematically, broad market index funds often outpace a low fixed mortgage rate over decades. Psychologically, however, a paid-off primary residence eliminates your single largest monthly overhead cost and provides unmatched peace of mind. Many people choose a balanced approach: automate baseline retirement contributions first, then direct extra cash toward the principal.
How much should I hold in a cash emergency fund?
Aim for three to six months of bare-bones survival expenses: rent or mortgage, basic groceries, utilities, and debt minimums. Sizing it to baseline needs rather than full discretionary spending keeps your cash target realistic while still providing complete protection against sudden job loss or emergencies.
Automating Your Next Five Decades Today
Log into your banking portal today and schedule one automated recurring transfer – whether it is $50 or $400 – into a high-yield emergency fund or broad index fund.
Fifty-two years of trial and error proved that waiting for a raise, perfect timing, or ideal conditions guarantees lifelong financial delay. Wealth accumulation begins the exact moment you decouple your cash flow from lifestyle inflation.
You never needed the executive salary or the breakout stock pick to build autonomy; you just need to turn on the machine.
Review Your Recurring Transfers
Open your banking app right now and schedule an automated transfer for your next payday morning to start building your cash margin.