At fifty-five, your peers look enviably composed with their spreadsheets, but thirty-two years of real retirement taught me that neat projections ignore what extreme age actually demands.
I left a 35-year corporate administration career in 1992 at age 62 with a $420,000 nest egg and a $1,100 monthly pension, convinced simple frugality was an ironclad defense. It was not. Multi-decade horizons break static models against relentless inflation, sudden six-figure care bills, and cognitive fatigue.
Surviving to ninety-four requires trade-offs, not timid cash hoarding.
These twelve practical principles clarify how to price those realities early so your plan still holds up past eighty-five.
Quick Tips Before You Start
Keep Equity Growth
Hold at least 40% in low-cost broad-market index funds to counter three decades of rising prices.
Separate Care Reserves
Ring-fence a dedicated custodial care fund early because routine Medicare covers zero non-skilled daily assistance.
Pick Downsize Targets
Set a firm deadline to downsize before age 80 to protect your independence.
Assign Account Proxies
Add trusted secondary contacts and durable powers of attorney while your health is solid.
Managing Wealth Across Decades
The first third of retirement feels manageable because your health is intact and your expenses remain predictable.
The danger arrives twenty years later when compounding inflation erodes cash and rigid withdrawal rules force bad asset sales during prolonged market downturns.
1. Fleeing to Cash Guarantees Purchasing Power Collapse
The instinct to retreat into the perceived safety of cash the day you stop working is completely understandable. When the paychecks end, watching a market dip feels like a direct threat to your shelter.
I fought that exact urge when I retired at 62 back in 1992. Instead of burying my $420,000 savings in certificates of deposit, I held a steady 50/50 split between bonds and equities. By the time I turned 75, that nest egg had grown to $890,000, even after funding every single month of living expenses.
Cash feels safe today, but it silently bleeds over decades.
Between 1992 and 2016, an average 3% inflation rate cut the dollar's real buying power in half. Sitting on static cash guarantees you lose the war of attrition against ordinary grocery bills.
If your family tends to live into their nineties, you face a 35-year retirement horizon where cash-heavy allocations have the highest mathematical failure rate. Keeping a baseline 40% to 50% in low-cost, broad-market equity index funds at age 55 is what provides the growth needed to outpace compounding price increases.
2. Rigid Withdrawal Percentages Break During Extended Recessions
You do not need an airtight mathematical plan to start drawing income. Fearing that a market crash will wipe out your savings is completely natural, but practical flexibility protects you far better than rigid percentages.
Mechanical withdrawal formulas break when recessions drag out.
Blindly taking a fixed four percent dollar amount adjusted upward for inflation every year sounds orderly on paper. In reality, demanding that annual increase during severe multi-year downturns forces you to sell equity index funds at market bottoms, permanently damaging the engine that generates your future income.
Carrying a dedicated two-year liquid cash buffer fully covered my family's basic living expenses through both the 2001 dot-com crash and the 2008 financial crisis without selling a single depressed stock index share.
Start building that cash cushion with modest amounts today.
Even diverting $75 or $150 from each regular paycheck into a high-yield cash account at age 55 begins assembling the defensive moat you need. Over several working years, that quiet, steady habit forms the operational bridge that prevents you from touching your long-term growth investments when markets drop.
Pair that buffer with a responsive spending habit. Whenever your portfolio value finishes down in a calendar year, trim discretionary expenses like travel and dining out by 10% the following year.
Dynamic spending adjustments protect your portfolio longevity far better over a 30-year retirement than inflexible annual increases. Trimming a little fat during lean years lets your shares sit untouched until the broader market eventually recovers.
💡 Tip: Review spending every December. If your portfolio fell that year, freeze discretionary budget increases for twelve months.
Retirement Portfolio Risk Spectrum
How allocation choices impact 30-year solvency
- All-Cash Allocation: Extreme long-term purchasing power loss from compounding inflation.
- Rigid Fixed-Rate Spending: High risk of capital exhaustion during early multi-year market downturns.
- Balanced Growth with Buffer: 50/50 stock-bond allocation paired with a 2-year liquid spending reserve.
3. Account Complexity Becomes a Dangerous Burden After Seventy-Five
Consolidate your scattered workplace rollovers, legacy IRAs, and odd taxable accounts under one primary financial institution before your sixtieth birthday. Juggling five logins and multiple tax statements might feel manageable at 55, but tracking Required Minimum Distributions across separate firms becomes an operational nightmare when cognitive stamina dips in your late seventies.
Simplify the machinery while your focus is sharp.
Build a clean two-bucket system: automate a monthly cash transfer from your consolidated investment custodian into one local checking account. This basic pipeline removes the burden of ongoing asset sales and allows a surviving spouse or named fiduciary to manage your cash flow without confusion.
4. Home Equity Locked in Bricks Cannot Pay Grocery Bills
Sixty percent of total net worth tied up in home equity feels secure, but bricks cannot buy groceries. When you consolidate your accounts, holding too much capital in physical real estate becomes an obvious hazard.
Run an annual check on three figures: property taxes, insurance, and long-term maintenance like HVAC or roof replacements. On my 2,400-square-foot house, those carrying expenses climbed from $3,200 in 1995 to over $11,000 annually by 2015. Every dollar sunk into maintaining illiquid walls is a dollar unavailable to generate liquid investment yield.
A paid-off deed does not eliminate living costs.
Health, Family, and Hard Realities
No matter how carefully you budget for leisure and utilities, late-life health needs and family pressures create major financial stress.
Understanding where public insurance ends and setting healthy boundaries with relatives protects your independence when you are oldest.
5. Custodial Care Costs Dwarf Routine Medical Expenses
Most savers assume Medicare steps in, but it only covers acute clinical treatment and pays zero dollars for custodial help.
We treat late-life vulnerability as a medical problem when it is actually an intensive labor bill. Between 2017 and 2021, I paid $145,000 directly out of pocket for private in-home aides and custodial support for my spouse. That cost hit hard and required ready cash that illiquid property could never provide.
Long-term care is an operational cash expense.
Shift your mental framework by dividing retirement healthcare into two distinct balance sheet items before turning 60. One bucket funds routine doctor co-pays and prescriptions, while a separate dedicated liquid fund or hybrid long-term care policy handles custodial assistance. Without that dedicated reserve, six-figure care bills will force sudden, destructive asset sales.
If you are weighing hybrid insurance against self-funding, review the numbers with a fee-only fiduciary planner while your health history still allows for standard underwriting.
⚠️ COMMON MISTAKE
Assuming Medicare Covers Long-Term Custodial Care
Traditional Medicare pays for acute hospital care and rehabilitation, not non-skilled daily assistance. Plan for home health aides or assisted living through dedicated liquid savings or hybrid insurance.
6. Rescuing Adult Children Derails Your Own Late-Life Independence
Bailing out a grown child with retirement funds feels like good parenting, but it creates a dangerous trap. Adult children have decades of wage growth, thirty-year mortgages, and student loans available to absorb financial hits. An eighty-five-year-old retiree facing steep medical costs has zero borrowing capacity and cannot apply for a loan to buy dinner.
Automate this boundary by locking a strict rule into your financial plan at 55: tax-advantaged accounts like your IRA or 401(k) are completely off-limits for family bailouts. Remove discretionary emergency transfers from your monthly banking menu entirely.
Draining your own safety net guarantees you become their future burden.
Late-Life Housing & Care Realities — At a Glance
🏡 Downsizing Age
Age 84 Transition
💵 Monthly Rent
$4,100 All-Inclusive
🩺 Care Out-of-Pocket
$145,000 (4 Years)
📐 Space Reduced
2,400 to 950 Sq Ft
The Key Takeaway
Transitioning housing before a physical crisis guarantees personal choice over location and daily amenities.
7. Postponing Downsizing Until a Crisis Eliminates Your Choices
You protect your personal autonomy by leaving the family home before physical decline forces your hand.
The trade-off is undeniably painful: you are walking away from familiar rooms, garden routines, and decades of neighborhood memories. Sifting through forty years of accumulated possessions in a 2,400-square-foot house takes months of exhausting physical labor and hard emotional triage, particularly when your joints and energy levels are already beginning to fade.
Waiting for a medical emergency costs far more.
If you delay until a bad fall or stroke strikes, you surrender every choice to hospital discharge planners and panicked relatives scrambling to secure whatever room has an immediate opening. At age 84, I moved into a $4,100 monthly independent living apartment on my own terms, which cleared away yard chores and preserved my daily independence.
Establish a firm operational deadline to downsize before your eightieth birthday. That single boundary keeps you in complete personal control over what you keep, what you discard, and where you spend your final decades.
8. Silence on Estate Logistics Causes Family Feuds After Death
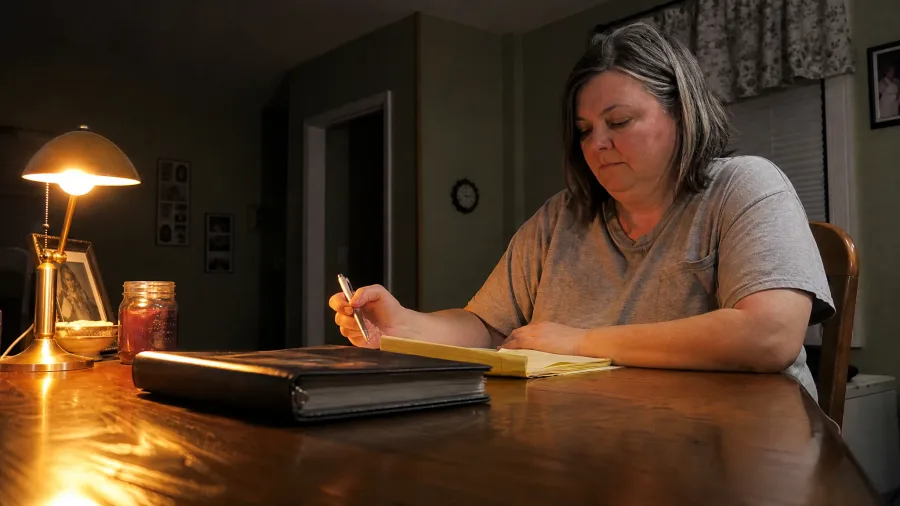
I sat at my dining room table at age 58 with three yellow legal pads and a shoebox of statements, suddenly aware that an unexpected medical emergency would leave my spouse completely blind to our balance sheet.
Most savers assume a basic will handles everything, but modern financial institutions bypass probate courts entirely. Direct beneficiary designations on your retirement accounts, brokerage holdings, and life insurance policies legally override whatever instructions are written in your will. An outdated designation filed decades ago will transfer your money to the wrong person regardless of your intent.
Polite family silence around money quickly turns into expensive probate battles.
When retirees avoid discussing logistics to prevent awkward dinners, surviving relatives face months of frozen checking balances, heavy legal fees, and administrative gridlock. You need durable financial power of attorney paperwork and healthcare proxies signed before age 60, securing legal authority for a trusted relative before any question of cognitive capacity or memory loss can arise.
Legal paperwork fails without plain operational instructions.
Assemble a dedicated emergency binder containing every institutional account number, property title, insurance policy, digital password, and estate lawyer contact. Schedule an audit every twenty-four months to verify that primary and contingent beneficiaries remain accurate across every taxable and tax-advantaged account. Store that folder securely and give your named executor exact instructions on how to access it.
Spend forty-five minutes walking your designated proxy through that file before the year ends. That single meeting removes the guesswork, prevents administrative delays, and protects your loved ones from avoidable conflict during their initial grief.
📋 Decade-by-Decade Estate Operations Checklist
Age 55
Add transfer-on-death (TOD) deeds to taxable brokerage and bank checking accounts so operating cash clears probate instantly.
Age 65
Consolidate scattered 401(k) plans into one custodian to reduce institutional points of contact down to a single dashboard.
Age 75
File formal trusted contact authorization forms across every brokerage and authorize your CPA to speak directly with your agent.
Age 85
Establish view-only electronic banking and utility access for your proxy to monitor recurring bill payments without surrendering full control.
Spending, Timing, and Perspective
Money is simply a tool to support your life, and its value changes dramatically as your physical energy shifts across different decades of retirement.
Balancing early travel, strategic family gifts, and local community connections produces a far richer late-life experience than simply hoarding every cent.
9. The Earliest Retirement Years Are Your Only Active Window
You do not have to hoard every single discretionary dollar out of fear. Once your foundational estate directives and emergency cushions are in place, give yourself permission to spend while your body still cooperates.
Post-career life inevitably moves through three distinct physical phases: the energetic go-go decade, the slower transition years, and the stationary late phase. In my early sixties, walking four miles across uneven European streets felt effortless; by my late seventies, walking through a single airport terminal required two full days of quiet recovery.
Money cannot buy back joint cartilage or aerobic stamina.
Underspending on physical travel between ages sixty and seventy-two out of extreme caution leaves you with unspent funds you simply cannot use at eighty-five. Allocating your largest experiential budget – perhaps $6,000 to $10,000 annually – to your first decade post-work extracts the greatest possible value from your savings before strenuous itineraries permanently close.
Front-loading your travel is not reckless abandon. It is a realistic acknowledgment that your physical window for ambitious adventure will expire decades before your investment portfolio ever runs its course.
10. Gifting Wealth While Living Delivers Value When Heirs Need It
I watched fellow retirees hoard every dollar for a will, only for their children to inherit assets at sixty-two, well after their peak borrowing years and child-rearing expenses had passed.
A targeted $15,000 gift toward a first home down payment or a 529 education plan transforms an heir's financial trajectory at age thirty. Gifting while living lets you witness that tangible relief firsthand, provided the transfers come strictly from surplus cash flow rather than compromising the dedicated reserves you will need for late-life custodial care.
Planned living gifts build family security far better than distant bequests.
💡 PRO TIP
Gift From Cash Flow, Never From Core Reserves
Only gift money generated from excess dividends, pensions, or surplus annual cash flow. Never tap your dedicated late-life healthcare cushion for family gifts.
11. Social Capital Outlasts Material Wealth in Late Retirement
The answer is never your portfolio balance.
Many people relocate at sixty-five to distant, isolated retirement enclaves, severing decades of community roots to chase quiet golf courses. By eighty, that isolation accelerates cognitive decline and creates expensive logistical dependencies. A paid caregiver can manage medication, but they cannot replace a familiar neighbor who notices when your mail piles up or your car sits unmoved.
You cannot hire authentic community during a sudden crisis.
Invest time and modest financial support into local neighborhood associations, civic boards, and multigenerational community groups right now while you are in your fifties. Your original peer group will thin over thirty years of retirement. Building ties with younger neighbors creates an active safety net that offers informal daily oversight, rides to appointments, and essential mental sharpness.
A dense local support system provides the responsive, everyday security that even the most substantial investment account cannot buy when your physical mobility starts to fade.
Late-Life Priority Strategy
Outdated 50s Assumptions
- Moving 100% of wealth into cash and CDs at retirement
- Staying in an oversized two-story home past age 80
- Leaving estate planning discussions entirely to a post-death will
- Hoarding travel funds for advanced old age
Field-Tested Longevity Moves
- Holding 40% to 50% equities for long-term inflation defense
- Downsizing proactively to single-story or supported living
- Updating direct beneficiary forms and assigning durable proxies
- Front-loading active travel during early healthy retirement years
12. Failing to Simplify Financial Directives Invites Predatory Exploitation
Strip every speculative asset, private placement, and complex annuity product out of your portfolio before you turn sixty-five. Processing speed and quantitative reasoning decline naturally with age long before any clinical diagnosis appears. Complicated holdings make aging investors prime targets for aggressive fee extraction, predatory schemes, and deceptive sales pitches you would have easily dismissed at fifty.
Complexity becomes a dangerous trap as your mental stamina fades.
Add a trusted secondary contact to every bank and brokerage account immediately to act as an automatic fraud tripwire. Then, sit down with a fee-only fiduciary advisor to map out a simplified, transparent drawdown strategy. Eliminating sales commissions and structural conflicts protects your wealth long before your oversight faculties slow down.
Frequently Asked Questions
Should I move everything into cash once I stop working?
No. Holding pure cash exposes your nest egg to compounding inflation across a thirty-year retirement. Maintaining 40% to 50% in broad-market index funds provides the growth needed to outpace rising living costs while short-term bonds and cash reserves cover immediate expenses.
How much cash should I keep outside my investment portfolio?
Keep roughly twenty-four months of baseline living expenses in high-yield savings or short-term certificates of deposit. This cash buffer prevents you from selling depressed equity shares during prolonged market downturns.
Does standard Medicare cover assisted living or home health aides?
Traditional Medicare pays zero dollars for non-skilled custodial care like dressing, eating, or bathing. You must fund long-term custodial help out of personal liquid savings, a dedicated health fund, or hybrid insurance policies.
When is the best age to downsize my family home?
Aim to downsize before age eighty. Moving while your physical health and mobility are intact gives you complete control over your living space and avoids rushed decisions during a medical emergency.
Why do beneficiary forms matter more than a standard will?
Direct beneficiary designations on bank accounts, retirement plans, and insurance policies override conflicting terms in a will. Reviewing and updating these designations prevents probate delays and family disputes.
Audit Your Longevity Plan This Weekend
Open your financial software this weekend and audit your thirty-year cash flow projections against a realistic 3% inflation rate and a six-figure custodial care reserve.
While your physical health and cognition are sharp, execute a durable financial power of attorney and designate trusted secondary account contacts across every institution.
My $420,000 nest egg survived thirty-two years of economic turmoil because I prepared for the realities of age eighty-five while still standing at fifty-five.
Check Your Account Beneficiary Designations Today
Log into your primary banking and retirement portals right now to confirm your designated beneficiaries and emergency contacts are completely up to date.