Many people hold onto the idea that retirement is a boundless stretch of freedom, a reward where the daily grind of work simply disappears. It certainly fixes the problem of deadlines and difficult meetings.
But this 'fix' removes a core structure from your life, revealing a new set of often-overlooked challenges that extend far beyond simply managing money.
Understanding these common, unexpected problems is the first step toward building a truly fulfilling retirement, not just an empty one. You are not alone in encountering these shifts. This article will help you identify key areas needing attention and offer practical steps to proactively prepare for and mitigate potential issues, so you can transition with confidence.
Quick Tips Before You Start
Schedule Activity
Block out specific times for hobbies or social engagements on your calendar, just like you would for work.
Build New Circles
Join a club, volunteer, or take a class to create new connections outside your old work network.
Review Healthcare
Meet with an advisor to understand your true out-of-pocket medical costs beyond Medicare.
Talk With Your Partner
Discuss expectations for shared time, personal space, and household duties openly.
Start Small
Pick one new routine or social activity to try for a month, then add another.
Personal Purpose & Time
Retirement doesn't just free up your schedule; it often redefines your sense of self and how you structure your days. The rhythm of work has a quiet power, and losing it creates space that needs to be filled intentionally.
These initial adjustments to purpose and time are often the first, and most profound, challenges many people face. They are rarely about money and almost always about meaning.
1. Losing Work Identity Creates a Void
Start exploring what truly brings you purpose outside of a paycheck right now, even if it feels premature.
The role you held for decades, the daily routine, even just having a 'job title' provided more than income. It was a source of identity, status, and a clear reason to get up each morning, and when that goes, a real void can open up.
You might feel adrift, wondering who you are without the structure of work. This isn't just a mental shift; it's a deep psychological change, and it's okay to acknowledge that confusion.
To counter this, consider giving just two hours a week to a local cause, like tutoring kids or helping at an animal shelter. Or join a community board that uses your professional expertise, perhaps meeting once a month. This small, consistent step is more powerful than waiting for a grand idea to strike, because it starts building a new identity long before the old one fades.
Your Identity Transition — A Roadmap
2. Too Much Unstructured Time Becomes a Burden
Build a loose framework for your days in retirement, otherwise, the endless free time can feel like a burden rather than a gift.
While the idea of spontaneous days sounds fantastic, for most people, the novelty wears off within a few months. That initial joy of sleeping in every day or simply deciding what to do at noon can quickly morph into boredom and a lack of motivation, a feeling much like aimlessness that can sit heavily on your chest.
Work provided built-in structure. It carved out hours, dictated tasks, and supplied social interaction. Without that, you have to be intentional about creating your own anchors. Try blocking out an hour each morning for a brisk walk, or dedicating a 'deep dive' slot from 10 AM to 12 PM three days a week to a new hobby, like learning to paint or woodworking.
It's easy to feel the pressure to fill every hour, every day, with exciting new plans immediately. You don't have to launch into a full, packed schedule the moment you retire.
Give yourself permission to ease into it. Start by identifying just one or two consistent activities you genuinely look forward to each week. Maybe it's a Tuesday morning volunteer shift or a Friday afternoon reading club. These small commitments create momentum and a sense of purpose without overwhelming you.
The goal is not to replace your old work schedule hour-for-hour, but to establish a rhythm that feels good and prevents the days from blurring into one another, turning freedom into a chore. Start by noting down potential new routines you're genuinely interested in, and try out one for a month while you're still working or in your first few weeks of retirement.
Relationships & Connection
The social landscape shifts dramatically in retirement. Your primary daily interactions often disappear, and existing home dynamics may need rebalancing.
Anticipating these changes allows you to proactively build new connections and strengthen existing ones, ensuring your social well-being remains strong.
3. Social Isolation After Workplace Bonds Fade
One of the biggest surprises I found after leaving my corporate job was how much I missed the casual chatter.
You don't realize how many daily, low-stakes interactions you have until they're gone: the quick chat by the coffee machine, the desk-side question, the team lunch. I used to have easily ten or fifteen short conversations a day, and when I stopped working, that dropped to nearly zero overnight.
It creates a real sense of social isolation, even if you have a strong family life. This isn't about deep friendships, but about the steady hum of connection that the workplace naturally provides. So, I decided to join a local photography club that met twice a month, just to get back some of that easy conversation and shared interest.
⚠️ COMMON MISTAKE
Don't Wait for Invitations
A common pitfall is expecting new social opportunities to simply appear. Proactively reach out to others, suggest activities, and take the first step to rebuild your social calendar.
4. Marital Dynamics Shift With More Together Time
Within the first six months to a year of retirement, you might notice a subtle shift in the most intimate social circle you have: your home life.
The change from spending 40+ hours a week apart to suddenly being together almost constantly can bring unexpected tensions. What used to be individual routines for work, hobbies, and downtime now overlap, sometimes creating friction where none existed before.
It's not about loving your partner less; it's about navigating a new reality that requires more communication than ever. You need to actively carve out space for separate interests, whether one of you takes up woodworking in the garage for a few hours daily while the other gardens, or schedules dedicated solo time for reading or errands.
But it's also a chance to build new shared experiences. Plan that long road trip you always talked about, or tackle a home renovation project together. The key is to check in regularly: maybe once a month, sit down and openly discuss evolving needs for alone time, what household tasks fall to whom, and what new activities you can both genuinely enjoy. This proactive conversation is how you avoid those small irritations from growing into something bigger.
Structuring Your New Time Together
Planned Shared Activities
- Target 2-3 focused hours daily on joint interests.
- Schedule one dedicated 'date' outside the home each week.
- Tackle one significant shared project (e.g., travel, home reno).
- Explore a new joint hobby or community involvement.
Protected Individual Space
- Ensure 2-3 hours daily for entirely solo pursuits.
- Maintain at least one independent hobby or routine.
- Cultivate separate social connections and friendships.
- Designate a personal quiet zone in your living space.
Financial Management
Even with careful pre-retirement saving, the financial landscape itself changes once you stop working. Managing your money becomes less about accumulation and more about sustainable distribution.
These new financial realities, especially unexpected healthcare costs, can quickly derail even the best-laid plans without proactive adjustment and professional insight.
5. Healthcare Costs Exceed Early Estimates
It's easy to feel overwhelmed by the thought of healthcare costs in retirement, wondering if your savings will really cover everything.
The common mistake is underestimating what Medicare doesn't cover. While it's foundational, out-of-pocket expenses for things like dental work, new eyeglasses, hearing aids, and many prescription drugs can quickly add up to thousands of dollars each year. Even more critical is the potential need for long-term care, like a nursing home or in-home assistance, which Medicare generally doesn't pay for and can quickly deplete a lifetime of savings.
One of the smartest moves you can make is to fund a Health Savings Account (HSA) if you're eligible, ideally aiming for a robust balance like $75,000 by retirement. This tax-advantaged account is specifically for medical expenses, and the funds can roll over year after year. Alternatively, explore supplemental insurance plans. For decisions like these, especially estimating your specific costs, talking to a financial advisor who specializes in retirement healthcare can provide the clarity you need.
Uncovered Costs in Retirement Healthcare
💸 Typical Annual Uncovered
$5,000 – $10,000
🦷 Routine Dental Care
Generally not covered
👀 Routine Vision/Glasses
Generally not covered
🏥 Nursing Home / In-Home
$60k – $100k+ annually
Pro Tip
Explore Medigap or Medicare Advantage plans to reduce your out-of-pocket exposure.
6. Navigating Complex New Financial Landscapes
For years, I focused solely on adding money to my retirement accounts. But when it was time to start taking money out, that felt like an entirely new challenge.
The fundamental shift is real: you move from accumulating wealth to carefully distributing assets for income. This requires a different investment approach.
Managing taxes on withdrawals from traditional IRAs or 401(k)s also adds complexity. Strategic planning for tax efficiency can save you significant money over time.
Beyond that, you have to fight inflation for decades. Building a diversified portfolio with categories like real estate or dividend-paying stocks helps maintain your purchasing power, preventing your savings from shrinking in value.
The trade-off is this isn't a hands-off system; regularly rebalancing your portfolio for income and mitigating risk takes ongoing attention.
But this consistent effort ensures your money lasts throughout retirement, giving you steady income and peace of mind. If it feels overwhelming, a fee-only fiduciary advisor can offer tailored guidance.
💰 Shifting Your Retirement Money Flow
Assess Expenses
Realistically determine your monthly spending needs in retirement, including any new hobbies or travel.
Review Sources
Identify all income streams: Social Security, pension, investment withdrawals, part-time work.
Optimize Withdrawals
Strategize which accounts to draw from first (e.g., taxable, then tax-deferred) to minimize taxes.
Inflation Proof
Adjust your portfolio to include assets that can keep pace with rising costs over time.
Annual Check-in
Meet with your financial advisor yearly to re-evaluate and adjust your plan as needed.
Well-being & Expectations
Retirement impacts your physical and mental health, often in subtle ways. Without the built-in activity and mental stimulation of work, it's easy to let these areas slide.
There's also a pervasive myth about retirement being a state of constant bliss. Confronting that expectation head-on allows for a more realistic and fulfilling experience.
7. Maintaining Physical and Mental Vitality Declines
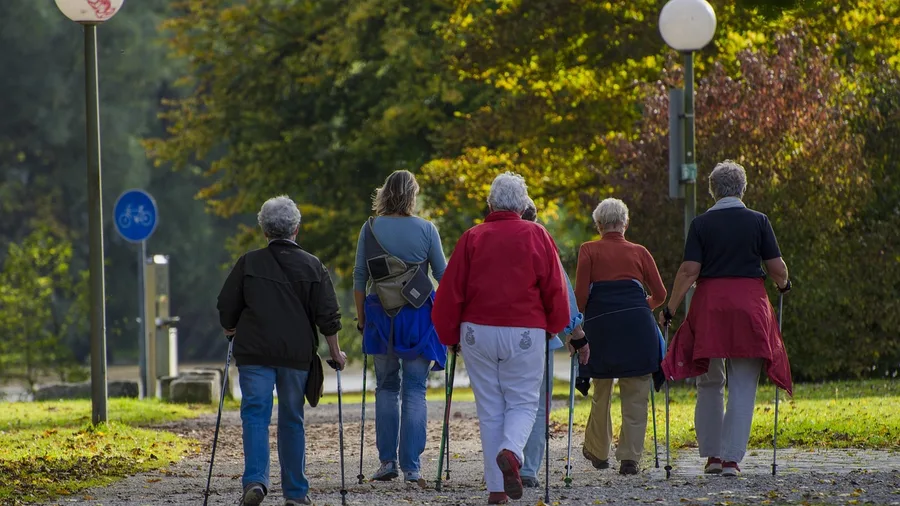
Just as you organize your finances, setting up automated routines for your health keeps you moving and thinking.
Make physical activity non-negotiable.
Schedule a 45-minute brisk walk every morning, or enroll in a gym class that meets twice a week. That consistency beats willpower.
For mental agility, commit to learning something new. Dedicate an hour each weekday to an online language course, or sign up for a community college history lecture series that runs for eight weeks. This pre-set engagement takes the decision out of it, making follow-through much easier.
8. Pressure to Be 'Happy' Ignores Realities
The widespread societal expectation paints retirement as a continuous parade of leisure, world travel, and unrelenting happiness. Many genuinely believe this picture will be their daily reality.
This myth, however, makes it tough to admit feelings of aimlessness, stress, or even quiet grief for a past professional identity. When these natural emotions surface, it's easy to feel like you're failing if you aren't perpetually cheerful.
But it's perfectly normal to feel this way. Retirement is a major life transition, and like any big change, it brings a full spectrum of feelings.
The concrete move is to give yourself permission to feel what arises, understanding that adjustment can take many months. Then, proactively plan for consistent emotional support, like joining local retiree peer groups or online forums that meet every other week for shared experiences. Schedule deliberate conversations with trusted family or friends, aiming for at least one longer chat each month.
If you find yourself struggling for more than a couple of months, consulting a therapist specializing in life changes can offer practical strategies and a safe space to process everything. This might involve three to five sessions. It's about being prepared for the emotional landscape of this new chapter.
Frequently Asked Questions
What is the biggest unexpected challenge in retirement?
Many people find the loss of work identity and the struggle to find new purpose the most significant unexpected hurdle. It can leave a void that requires proactive effort to fill with meaningful activities.
How can I prevent social isolation after I retire?
Proactively join new clubs, volunteer, or take classes based on your interests. Nurture existing friendships and actively seek out new social circles to replace the daily interactions from work.
Will Medicare cover all my healthcare costs in retirement?
No, Medicare does not cover everything. You will likely have significant out-of-pocket expenses for dental, vision, hearing aids, and many prescription drugs. Long-term care is typically not covered, so plan for supplemental insurance or an HSA.
Is it normal to feel bored or restless in retirement?
Absolutely. The initial novelty of unstructured time often fades. It is normal to feel bored or restless. Combat this by establishing new daily routines, scheduling engaging activities, and finding new passions to pursue.
Should I revisit my financial plan after I retire?
Yes, your financial plan needs to shift from wealth accumulation to income distribution. Revisit it with a fee-only fiduciary advisor to optimize withdrawals, manage taxes, and account for inflation over decades.
Proactive Steps for a Fuller Retirement
Navigating retirement successfully requires thoughtful, proactive planning beyond simply leaving work. Identify new purposes, structure your time, build social networks, communicate openly with your spouse, and plan for healthcare and financial complexities. These steps tackle common, unexpected challenges directly.
Maintaining your physical and mental well-being is also key. Retirement offers a chance to build a truly fulfilling life on your own terms. With this preparation, that imagined 'endless vacation' becomes a rich, lived reality, allowing the freedom you sought to genuinely flourish.
Start Your Proactive Plan Today
Re-read the "Quick Tips Before You Start" section and pick one small action you can implement this week to begin building your fulfilling retirement.