Getting this wrong at 58 costs years, not dollars – and I nearly spent six more of them. I moved $1.24 million last spring, a 401(k), two IRAs and a taxable brokerage, out of 14 advisor-picked funds and into three index funds.
I'm 58, an operations manager in Portland, Oregon. Six years from a planned retirement at 64, that money was still sitting in funds chosen long before, at an all-in cost of about $20,500 a year. I kept telling myself I was waiting for a better entry point. What I was actually doing was waiting out a countdown.
The switch was never a market call. It was stopping a fee bill, getting the tax right in the taxable account, and trading 14 funds for three at roughly $500 a year.
You can settle whether 58 is too late by doing one thing first: total the all-in cost of every account. Then fix the retirement accounts, and get a tax estimate before you sell anything taxable.
Quick Tips Before You Start
Add up every fee
Total the advisor fee plus fund expense ratios across all accounts before you move anything.
Keep cash separate
Leave your emergency fund in a high-yield savings account outside the portfolio.
Know your gains
In a taxable account, list the unrealized gains before you sell a single share.
Pick one review date
Choose a single day each year to check your mix; ignore the rest.
Write the plan down
One page: your target percentages, rebalancing rule, and retirement date.
The Switch Itself
This part is about the mechanics: the deadline I set, what the move cost up front, and what the portfolio looked like on the other side. It's the least emotional section and the one that saved me the most money.
Read it with a pencil. The numbers are the point.
1. At 58, the Deadline Was Mine, Not the Market's
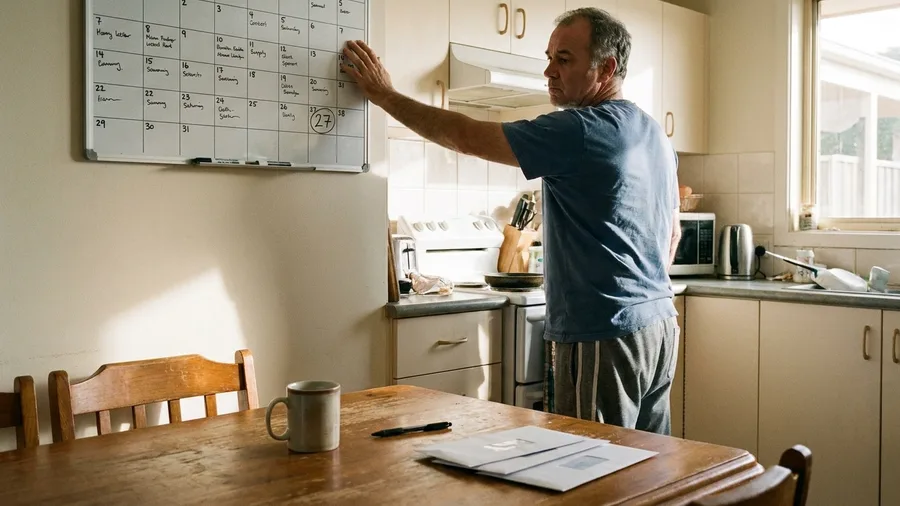
The number that stopped me was on a sticky note I put on the fridge in January 2025: 64. That's when I want to stop working, and I'm 58 now, so the countdown was six years, not some chart of where the market might go next.
What I had to admit was that every extra year of waiting on a better entry point was already costing me. My advisor portfolio ran about $20,500 a year in fees and fund expenses on $1.24 million, so another twelve months of patience was another $20,500 out the door before the market did anything at all.
I kept $60,000 in a high-yield savings account outside the portfolio, and I never touched a dollar of it through any of this. The cost of waiting wasn't a guess about a correction; it was a number I could see, and it made sitting still feel like a decision instead of a default.
| What changed | Old advisor portfolio | New three-fund portfolio |
|---|---|---|
| Number of funds | 14 funds | 3 funds |
| Annual cost | 1.1% advisor fee + ~0.55% fund expenses (~$20,500) | ~0.04% blended expense ratio (~$500) |
| Accounts | 401(k), two IRAs, taxable brokerage | Rollover IRA, two IRAs, taxable brokerage |
| Tax bill | Managed by advisor | $28k gains in taxable sold in two batches |
| Ongoing work | Quarterly statements, advisor calls | One January check, 5-point drift rule |
2. The Switch Cost Less Than One Year of Fees
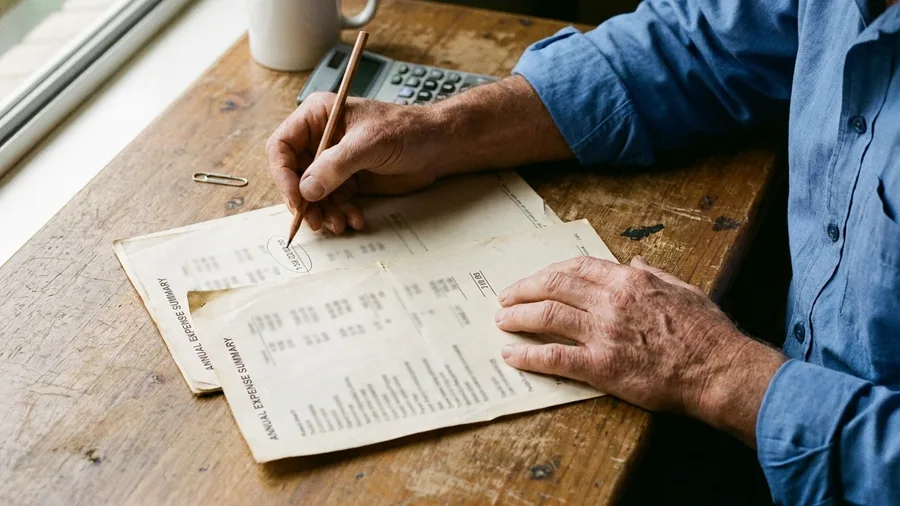
Moving to index funds is not a free transaction, and the common mistake is to assume it is, or to assume the bill is so large you should not bother.
For years I paid roughly $20,500 annually on a $1.24 million portfolio split between a 1.1% advisor fee and about 0.55% in fund expenses, and that steady drain was the reason a one-time bill was worth facing rather than avoiding.
The whole change took a little over a month and a half in the spring of 2025, and it moved through pieces with very different tax treatment. Rolling the 401(k) into an IRA and repositioning my two IRAs triggered no capital gains bill at all, so the only real planning happened in the $150,000 taxable brokerage account, which carried about $28,000 of unrealized long-term gains. I had a CPA price that out before I sold anything, split the sales across two tax years, and the new three-fund mix came in at a blended expense ratio near 0.04%, about $500 a year. The up-front cost to stop the old fees came in under what a single year of those fees had been charging me.
3. Three Funds Replaced Fourteen and a Login
Forty basis points. That is the entire ongoing cost of the portfolio now, about $500 a year on $1.24 million, against the 1.1% advisor fee and roughly 0.55% in fund expenses I had been paying.
The holdings fit on one page: 60% in a US total stock index, 25% in an international stock index, 15% in a bond index. That's it. No sleeve of specialty funds, no manager I had to call to ask what he thought about the second quarter, no quarterly statement packet I set on the counter and did not open for a week.
Before, the same money was scattered across 14 funds sitting in a 401(k), two IRAs and a taxable brokerage, with an advisor login on top and a statement arriving every three months. I could not have told you the overall expense ratio of that mix without asking, which tells you most of what you need to know about how well I was watching it.
What replaced all of that was one date and one rule. Each January I check the 60/25/15 split, and I only do anything if a slice has drifted more than 5 percentage points off its target. On a $1.24 million portfolio, a 5-point drift is roughly $62,000 of movement, so it is a genuinely rare event, not something that gives me an excuse to fiddle every few weeks.
Here is the part that makes the timing matter. The fees I stopped were not a one-time hit; they were being charged every year I stayed put, and every month I put the switch off was another month of the old bill running in the background. If you are 58 and looking at a similar setup, the expense ratio you are paying right now is the cost of your patience, and it keeps accruing whether or not the market cooperates.
There is a real trade-off, and I won't pretend otherwise. Getting to three funds meant a stretch of paperwork and phone calls, a CPA conversation I had been avoiding for a couple of years, and sitting with a few statements I did not fully understand. It took effort and it took attention I would rather have spent elsewhere.
But the ongoing job is small by design, which is the point. A page, a date in January, and a 5-point rule to keep me from tinkering. The simplification didn't just change what I own; it changed how much of my life the portfolio gets to occupy, and at 58 with a retirement date on the calendar, that is worth more than a basis point here or there.
What the Drift Rule Actually Triggers
🇺🇸 US stock drift band
55% to 65%
🌍 International band
20% to 30%
🛡️ Bond band
10% to 20%
📏 Dollar move that trips it
~$62,000
🔁 What you do when it trips
One trade, back to target
📅 What you do the other 11 months
Nothing
Skip this rule if
Your portfolio is under $200,000 — a 5-point drift is too small to justify the trade; check once a year and let new contributions do the work.
What Changed in the Money
Once the switch was done, I could finally see what I owned. This part is about the portfolio's shape, the one slice I had to defend, and the tax puzzle I couldn't ignore.
It's where the savings turned into something I could actually point to.
4. I Own More Companies, Not Fewer
The worry runs that fewer funds means less spread. It's backwards. Three index funds owned me more of the market than fourteen advisor picks ever did, and I can tell you why in a sentence: a total-market fund doesn't select companies, it holds essentially all of them, at the weight the market already assigns. Wondering whether such a boring portfolio really beats managed funds is the question worth sitting with before you make the switch yourself.
The old lineup looked diversified on the statement and wasn't. Several of those fourteen funds held the same large companies at different weights, so I was more concentrated than the fund count suggested, and I only learned that when I pulled every fund's top ten holdings into one spreadsheet and watched the same names repeat down the column.
The new shape is 60% US total stock index, 25% international stock index, 15% bond index, and that split is the entire diversification plan. No extra fund was needed to own more of the market. The 25% slice puts a quarter of the stock money in companies based outside the US, which the advisor mix barely did.
If you want to start smaller than a full switch, start smaller. Move one account, or even just redirect the next $500 of new contributions into a total-market index fund and leave the old funds sitting there. Owning the broad market in one fund still works at $500 a month; the fund count was never the point.
💡 Tip: Check your current funds for overlapping top holdings — you may already own the same companies five times.
⚠️ COMMON MISTAKE
Don't confuse simplicity with concentration
Three broad index funds can own more companies than fourteen handpicked funds. The number of funds tells you nothing about diversification — the holdings do.
5. Bonds Are the Part I Had to Defend
If the bond slice feels like a wet blanket next to stock returns, that reaction is normal and you are not doing it wrong. I felt it too. At the start, 15% came to about $186,000 sitting in bond index money that looked, next to a strong stock year, like the laziest $186,000 I owned.
The slice does one job: it covers what I plan to spend in the first five years of retirement, so that spending does not depend on a stock recovery arriving on schedule. That is the trade, plainly stated. Lower swings now, lower long-run growth than an all-stock mix would have delivered.
So the annual check is simple, and it is not the account total. Each January I look at three things: whether the 60/25/15 mix still matches the retirement date, whether any slice has drifted more than 5 percentage points from target, and whether the bond slice still covers five years of planned spending.
If a slice has drifted past that 5-point band, rebalance. If it hasn't, close the page. The one honest exception is a reader whose pension already pays every fixed cost; for you the bond slice's reason for being there is thinner, and the split deserves a second look against your own numbers.
The Numbers That Changed
6. The Taxable Account Was the Only Real Puzzle
The tax was the thing that kept me up at night.
Not the fees, not the mix, not whether the market was about to turn. The brokerage account. Every time I thought about selling what was in it, a number I couldn't see floated in the back of my mind, and that number was a bill. So I didn't sell, for months, which was its own kind of cost.
Here's what made it confusing: the retirement side turned out to be clean. I rolled the 401(k) into an IRA and repositioned the other two IRAs, and none of it triggered a capital gains bill, because inside a retirement account you can trade without a tax consequence. The brokerage account doesn't work that way. Sell a fund there and you realize the gain right then, and the tax comes due for that year.
On $150,000 of holdings, about $28,000 was unrealized long-term gain.
Long-term meaning I'd held the funds more than a year, which gets a lower rate than a quick flip would. Unrealized meaning the paper gain hadn't been taxed yet, because I hadn't sold. That is the whole trap: the gain sits there quietly until the day you sell, and then it's income for that tax year, at your rate, not the fund company's. Here's the permission slip, though. You do not have to sell it all at once, and you don't have to sell any of it to start fixing the retirement side.
That's the part I'd tell anyone standing where I stood. Do the part that doesn't cost you a tax bill first, and treat the taxable account as a slower, separate project. Before I sold a single share, I paid a CPA for an estimate, a few hundred dollars, to tell me what the sale would actually cost. Then I sold in two batches, splitting it across tax years, rather than dumping it in one go. It stretched the job over two springs instead of one.
If your taxable balance is small, or your gain is a few hundred dollars, the tax may not be worth the worry at all. Sell it, pay the small bill, move on. On a larger account, do less: one batch a year, after a tax estimate, and never a sale before you know the number. The one rule I came out of this with is simple. No taxable sale without knowing the tax bill first.
The Tax Cost, Side by Side
Retirement accounts
- Applies to: the 401(k) rollover and both IRAs
- Tax on the switch: $0
- Timeline: done inside the same six weeks
Taxable brokerage
- Applies to: $150,000 held, $28,000 of it gain
- Only the gain is taxed, not the whole balance
- Split into two batches, one per tax year
What Changed in My Head
The portfolio was simpler, but my habits weren't. This part is about the behavior the switch exposed — the checking, the reactions, and the discipline to do nothing.
It's the part I didn't expect, and the part that will decide whether the switch actually works.
7. I Checked the Balance Far More Than I Expected
Delete the app from your phone the week the money lands, and put one calendar reminder on the first Saturday of each month instead. I did not do that at first. For the first 60 days after the switch, I opened the balance most mornings, often before I had started the coffee, and a single red number could set the tone for the whole day.
The habit was never about the plan. The plan did not change one bit between Monday and Tuesday, and the funds did not either, but the total did, and I kept going back to look at it.
The trigger came on a 3% down day. I watched $37,000 of paper value disappear before lunch and I was fine, genuinely fine, because I knew my three funds and my 15% bond slice had not moved and my retirement date had not moved either. That was the moment I realized I was not checking on the portfolio. I was checking on my own nerve, and the checking was making the nerve worse, not better.
If you find yourself doing the same thing after you switch, the person to talk to is not an advisor who will charge you 1.1% to hold your hand. It is a fee-only fiduciary you pay by the hour, or a free call with your plan provider, or honestly just your spouse, who will tell you the same thing I eventually told myself: the number on the screen has no idea what your plan is.
The first statement after the move read $1,238,000. Six months later it read $1,301,000, and I had contributed exactly nothing in between, which is the point. Now the monthly check is the 60/25/15 mix. Not the total.
📅 What the Checking Habit Cost and Fixed
Days 1-60
Two to five minutes lost every morning before work; mostly dread, not information.
The fix
12 monthly checks a year, first Saturday, 15 minutes. Not 250 morning glances.
What to look at
$1,301,000 total was noise. The 60/25/15 mix was the signal, and it had barely moved.
What not to look at
The daily total, the news, and any red number before coffee. All three are unactionable.
Skip this if
You genuinely need the balance for a drawdown this year. Then check weekly, not hourly.
8. A Bad Week Felt Different From a Bad Year
Probably worse than you expect, and probably not for the reason you think. Four months in, a 10% pullback arrived and I felt every point of it, because a simple portfolio shows you the whole drop in one clean number instead of burying it in fourteen fund statements you never quite added up.
My old advisor portfolio would have fallen the same amount. I just saw it less often, and a quarterly report reads softer than a daily red line, which is not the same thing as being safer, though my gut treated it that way. The 15% bond slice softened the paper loss and gave the plan something to lean on, but it did not pretend the drop away.
So here is the move, and it takes about ten minutes. When the next drop comes, write down what you are feeling and what you want to do about it, in a note on your phone, date and all, and then do nothing for 24 hours. I wrote mine on a sticky note and stuck it to the door of my home office and read it the next morning. By then the urge to sell had passed and I could see the note for what it was, which is a reaction, not a plan.
9. The Hardest Part Was Doing Nothing
Ninety-four days. That is how long I went after the switch without placing a single trade, and it was the longest stretch of financial quiet I had in twenty years. I had expected the hard part to be the selling in spring. It was not. The hard part was January, when nothing was wrong and I still had to leave the accounts alone.
My whole job now fits on one page. Every January I open the statement, write down the three percentages next to the targets, and look at the gap. The rule I set for myself before the move was a drift of more than 5 percentage points, and I wrote it down in pen because a number in my memory is a number I can argue with later. A slice sitting at 62% against a 60% target is inside the line. A slice at 66% is not, and that is the only thing that gets me to touch anything.
Nobody is adding to the account anymore. The $1.24 million just sits there, and no new money goes in, which means every bit of growth has to come from the holdings themselves rather than from my paycheck. The first statement showed $1,238,000. Six months on, with zero dollars contributed, it had reached $1,301,000. That is the part that surprised me: the portfolio did its work while I was doing nothing, which is not the relationship with money I was trained to have.
The page also says when to rewrite it, and the answer is not the market. It is the retirement date. When I move that date up or push it back, the 60/25/15 mix gets a fresh look, because a plan built for a countdown to 64 is not the same plan if the countdown changes. A red day on the screen is not a reason to open the document. A change in when I stop working is.
That gets me to the honest cost of this arrangement. Restraint is not free; it means sitting with a decision you cannot see, on a schedule you set months ago, and trusting a rule you wrote when you were calmer. Some people will find that page too thin to lean on, and a fee-only fiduciary can help build a thicker one. For me, ninety-four days of no trades was the proof I needed.
The ongoing work is mostly refusing to tinker.
— What I tell anyone who asks about switching at 58
Frequently Asked Questions
Is it too late to move to index funds at 58?
No. The question isn't age, it's cost and taxes. If your current all-in annual cost is high, waiting another year costs you that amount again. The retirement accounts can usually be repositioned without a tax bill; only the taxable account needs a plan, and a CPA can give you an estimate before you sell.
What will the switch cost me up front?
For me, the one-time cost was less than the old annual fee bill. The main expenses were the tax on gains in the taxable account (about $28,000 unrealized in my case) and any transaction fees, which are often zero at major brokerages. Get a tax estimate first so there are no surprises.
Do I need to sell everything at once?
No. I sold the taxable account in two batches across tax years. The retirement accounts can be moved in one go without triggering capital gains. Spread the taxable sales if it keeps you in a lower bracket or reduces the tax hit.
How much should I keep in bonds?
That depends on your spending needs and other income. I chose 15% because it covers about five years of retirement spending without relying on a stock recovery. If you have a pension covering fixed costs, you might need less. If you're unsure, talk to a fee-only fiduciary.
Will I obsess over the balance after I switch?
You might, at first. I checked daily for 60 days and then deleted the app. Set a monthly calendar check instead of daily access, and focus on your target mix rather than the total. The habit fades once you stop looking.
The First Move Is an Addition Problem, Not a Market Call
It was worth it. My annual cost fell from about $20,500 to roughly $500, and 14 funds became three. If you're where I was, add up the all-in annual cost of every account first, fix the retirement accounts next, and get a tax estimate before selling a share of the taxable one.
At 58 the real deadline was six years to 64, not a forecast. My first statement read $1,238,000; six months later it read $1,301,000, with no new contributions from me.
My regret is the years of fees, not the week in spring 2025 I switched. The math was always there. I just hadn't done the addition.