I kept working years past the point my body and spirit told me to stop, convincing myself it was safer. That was my mistake, and I wish I'd listened to those signals sooner.
At 66, I've heard countless friends and colleagues say, 'just one more year,' always chasing a future that never quite arrives. That hesitation is understandable.
But the right time to retire isn't about a number on a calendar. It's about a confluence of clear, personal signs already showing up in your daily life.
These are the nine indicators I recognized in myself and observed in others, that tell you if you've already passed your best moment to step away from work.
By the end, you will have a clear framework to assess your current situation and decide if it's finally time to make the leap. You don't have to act on all of these today. Pick one or two that resonate most, and start there.
Quick Tips Before You Start
Journal Your Feelings
Spend five minutes daily writing about how work truly makes you feel.
Run the Numbers
Calculate your minimum monthly expenses and see if your savings cover them.
Talk to Your Family
Discuss your retirement thoughts openly with loved ones to gauge their perspectives.
Map Future Interests
List five activities you would pursue immediately if you retired tomorrow.
1. Your health shows a noticeable decline
For almost two years, I noticed my daily aches weren't just aches anymore; they were a dull, constant throb in my lower back, aggravated by long days driving between commercial property tours.
My work wasn't just stressful, it was actively harming me: that chronic pain, along with stress headaches from tight deadlines, became my constant companions. It stopped me from hiking the Montana mountain trails near my cabin, something I knew would clear my head and strengthen my body. My job was, in effect, preventing my own recovery.
This isn't about blaming your job for every sniffle. It's about recognizing if your work environment, responsibilities, or physical demands are directly contributing to a worsening health condition, or keeping you from getting better. I reached a point where continuing to push meant sacrificing my quality of life for a paycheck I no longer needed.
If you're seeing this in your own life, it's a critical sign to stop and ask: Is my health improving, staying stable, or getting worse because of my job? Go talk to your doctor. A medical professional can help you understand the real physical toll and whether your work is an active barrier to feeling better.
2. Motivation and burnout have taken over
It's easy to feel guilty when the passion for your work evaporates, especially if you're a long-timer. But if a constant feeling of dread or exhaustion has replaced that old drive, that's a clear signal.
For me, it became obvious after 20 years in commercial real estate. I'd sit staring at property reports, the details and market trends that once fascinated me now blurring into an endless, joyless chore. My enthusiasm was so low it started to affect my market analyses, making even simple tasks feel like climbing a mountain. This deep emotional burnout, I realized, was just as debilitating as any physical ailment.
Consider a simple system: the "Joyless Chore" tally. For one week, make a small mark every time you feel that deep mental drag or catch yourself wishing you were anywhere but at your desk. You're not doing this to feel bad, but to see plainly how much of your workday is spent in a state of quiet resignation, or worse, dread. It turns a vague feeling into a concrete sign.
💡 Tip: When dread sets in, ask yourself: 'What specifically am I avoiding today?' Write it down. Often, the answer reveals a deeper issue than just procrastination.
Retirement Ready: Jargon Decoded
3. Your finances are well-ordered
The next logical step, especially when burnout starts to set in, is to run your numbers. You might be surprised to find that continuing to work offers no significant financial benefit you don't already possess.
I paid off my Montana cabin five years before retiring, which felt like a massive weight lifted. I knew I had roughly $1.2 million in my retirement accounts. Using a basic 4% withdrawal rate – which historically helps money last through retirement, though returns are never guaranteed – I knew that would provide around $48,000 annually. This figure covered my desired lifestyle without relying on future income.
The trade-off then became clear: I was working for 'more,' not for necessity. The extra income wasn't adding to my security or options in a meaningful way; it was just delaying the freedom I'd already earned. This clarity gave me peace of mind to make the leap.
Cost of Delaying Retirement
⏳ Lost Time
1,800+ hours/year
📉 Health Impact
Increased stress
🌱 Missed Hobbies
Unlimited
🤝 Relationship Strain
Hard to quantify
Opportunity Cost
The biggest loss is often the life you could be living, not just the money you're earning.
4. Your job offers no new growth
I distinctly remember a Tuesday morning, maybe five years before I finally retired, sitting at my desk watching the rain fall on my cabin window, scrolling through new property listings. It was the same process I'd done thousands of times, but something had shifted.
The thrill was gone. The puzzle of finding the right commercial property, negotiating the deal, or even seeing a new development come to life had faded. It wasn't just boredom; it was an active disinterest in mastering the next market trend or learning another software update. My job, once a source of growth, had become a flat line.
With my finances solid, the primary driver for staying was gone, leaving a void where new challenges used to be. That's when I realized the real value was in creating my own challenges, outside of work.
This isn't about quitting your job on a whim. It's about consciously setting up avenues for personal development that run independently of your employment. For me, that meant dedicating time each week to learn woodworking techniques. I signed up for an online course and spent about two hours every Saturday morning studying joint types and safe tool usage.
The mechanism is simple: by actively investing a small, consistent amount of time into a new skill, hobby, or project outside of work, you start to pull your sense of purpose away from your job. You're building an internal "retirement magnet" – a strong, compelling set of reasons to step away.
It felt like an effort to get started, especially after a long week of work, but the payoff was immediate. Those two hours on Saturday filled me with a sense of accomplishment my job no longer provided, and it gave me a clear, exciting goal: building a new deck and workshop for my Montana cabin. This small, consistent commitment created a future to look forward to, making the daily grind less tolerable by comparison.
Start small. Can you find one hour this week to research a class, read an article about a new interest, or even just list three things you've always wanted to learn? Set it on your calendar and treat it like an unbreakable appointment. This isn't just dreaming; it's laying the groundwork for your next chapter.
Staying vs. Retiring: What Changes?
Continuing to Work
- Maintain current income (but miss out on hobbies)
- Structured daily routine (even if it's boring)
- Social interaction with colleagues (even if distant)
- Delay using savings (but delay living too)
Retiring Now
- More time for personal pursuits (woodworking, hiking)
- Freedom to create your own schedule (no fixed alarms)
- Deeper connections with family/friends (uninterrupted)
- Invest in yourself (new skills, travel)
5. You actively resent your job
This creeping sense of dread often starts when professional challenges fade, turning stagnation into outright resentment.
For me, the early alarm for another multi-day property tour – often set for 5:30 AM – would trigger a tangible clenching in my gut. It was a wave of actual dread, not just a dislike, a stark contrast to the quiet anticipation I used to feel about my work.
This level of aversion is a profound personal cost.
The common mistake is enduring this resentment, thinking it's simply "how work is" or that you just need to push through. I remember some mornings lying in bed for twenty minutes past my alarm, inventing small tasks just to delay the inevitable start of the day.
The thought of reviewing another commercial lease felt like a prison sentence compared to the pure joy I found hiking with my dog, Scout, on the mountain trails. When your personal life brings that much more happiness, it's a clear sign.
6. You have a clear retirement 'why'
"
For a successful retirement, it's not enough to run away from something; you need a strong "why" to run towards. This clarity of purpose fills the space your job once occupied, protecting you from boredom or a sense of aimlessness.
I started building my "why" years before I retired. I listed specific projects: a new deck for the cabin, a woodworking shop, and volunteering at the local animal shelter. I even mapped out a two-week road trip to visit old college friends. These weren't vague notions; they were concrete plans. If you're feeling that resentment, start by simply listing three activities you'd genuinely love to dedicate time to. Even picking one small thing you can start exploring now, like joining a local hiking group or researching a passion project online, can give you a powerful new direction.
💡 Tip: Start small: pick one single, concrete activity you'd pursue in retirement and spend 15 minutes planning it right now. The action makes the dream feel tangible.
The greatest wealth is to live content with little. My paycheck grew, but so did my discontent.
— My own realization at 64
7. Work strains your personal relationships
We often tell ourselves that family understands, that we'll make up for missed moments once work slows down. But those missed opportunities for connection, especially the milestones, carry a hidden cost that accumulates with every passing year. They don't compound like interest, but like absence.
My work in commercial real estate demanded constant travel. I recall the sting of missing both of my nieces' high school graduations because I was on essential, out-of-state property tours. I'd rationalize it, telling myself it was just 'part of the job,' but the feeling of being absent from such defining family events stayed with me.
That quiet regret built up over time, a stark reminder of the non-financial toll my career was taking. It wasn't just two phone calls; it was two irreplaceable days, two rites of passage that passed without me there to share them.
Retirement finally allowed me to prioritize those relationships. Now, I spend every Sunday having brunch with my sister and her family, a simple ritual that fills a void I didn't fully acknowledge before. The relief that comes from these consistent, unhurried moments is palpable, showing me just how much work had strained those ties and how much there was to gain by choosing to step away.
🗺️ Charting Your Retirement Journey
Self-Assess
Honestly evaluate your physical, mental, and emotional readiness for retirement.
Financial Check
Confirm your savings, investments, and expenses align with your retirement goals.
Plan Your Purpose
Identify hobbies, volunteer work, or new skills you want to pursue.
Discuss with Loved Ones
Share your plans and gather support from family and close friends.
Consult Experts
Talk to a fee-only financial advisor or CPA about your specific situation.
Set a Date
Choose a realistic retirement date and begin working towards it.
8. You constantly fantasize about retiring
If you find your mind constantly drifting away from your current tasks and into elaborate daydreams about retirement, it's a clear signal. This isn't just a brief mental break; it's a check-in on where your true engagement lies.
During long, tedious meetings about new property developments, I'd often mentally draft blueprints for the workshop I wanted to build behind my cabin. My focus on those details was intense, far surpassing my interest in the actual meeting agenda. I planned hiking routes through the national forest when I should have been strategizing my next quarter's sales.
This consistent mental escape showed me that my professional responsibilities were no longer holding my attention. My energy was already focused on my future, indicating my work was little more than a placeholder.
9. Physical abilities limit job performance
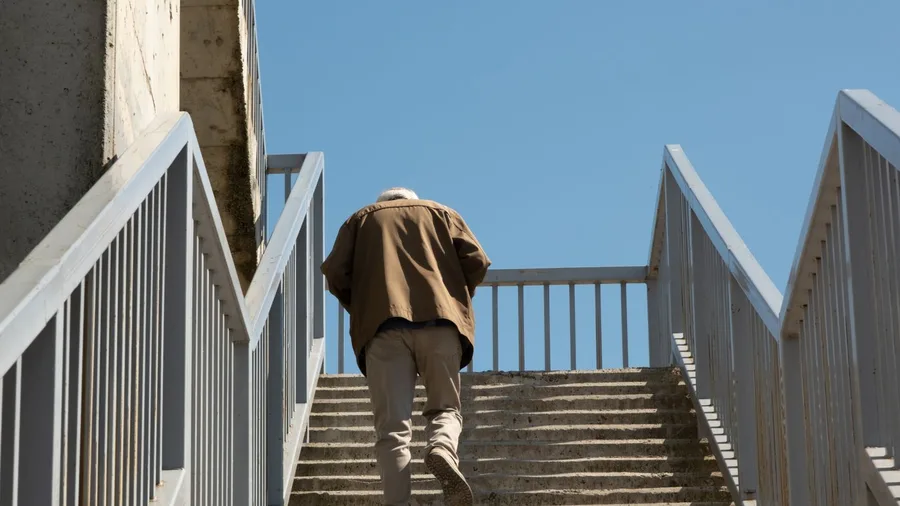
It's a question many of us quietly avoid, hoping that a little more effort or a good night's sleep will somehow fix it.
For me, working in commercial real estate meant physically inspecting buildings from top to bottom. Climbing multiple flights of stairs in large, vacant buildings during property tours became a significant struggle. By the fourth or fifth floor, my legs would ache and my breath would come in ragged gasps, a far cry from the ease I once felt.
This wasn't just about feeling tired; it was a clear decline.
Even more concerning was my work on ladders, checking roofs or elevated areas. I started feeling unsteady, a noticeable tremor in my hands when I gripped the rungs. That unsettling lack of balance wasn't just about my comfort; it raised real safety concerns, not only for myself but for anyone working alongside me.
The mindset shift wasn't about admitting I was 'getting old,' which felt loaded with shame. It was about recognizing that the job's physical requirements had simply outgrown my current capacity.
This wasn't a willpower problem, expecting to just 'hustle harder.'
My agility had reduced, and my stamina had diminished, making tasks that were once routine now genuinely difficult and potentially hazardous. My younger colleagues navigated construction sites with an ease I simply couldn't replicate anymore.
Understanding this difference – that the job itself was now asking for something my body couldn't safely provide – was liberating. It moved the decision from a source of personal frustration to a practical assessment.
Frequently Asked Questions
Is it truly too late to retire at 66?
It's rarely 'too late' to retire, but these signs indicate you've likely passed the optimal time based on personal well-being. Focus on what you can control now, not what's past.
What if my finances aren't fully in order?
Even if your finances aren't perfect, addressing these personal signs can still guide your next steps. Consider working part-time or seeking a fee-only financial planner to strategize options for your specific numbers.
How much should I have in my emergency fund for retirement?
Most advice suggests having three to six months of essential living expenses saved in an easily accessible, high-yield account. This cushion handles unexpected costs without disrupting your retirement income.
Should I pay off debt or save for retirement first?
The best path depends on your specific debt interest rates and feelings. High-interest debt (like credit cards) usually demands attention first, but your employer's 401(k) match should be maxed out even before that. It’s a nuanced choice; run it against your own budget first.
How can I avoid boredom in retirement?
Actively planning for your 'why' is crucial. Pursue hobbies, volunteer, learn new skills, or connect with community groups. The goal is to fill your days with purpose, not just leisure.
Recognizing the Unspoken Costs of Staying at Work
Recognizing even a few of these nine signs is a strong signal: you've likely passed your best retirement point, and it's time to act. Don't fall into the 'just one more year' trap, like many I know who regretted not moving sooner.
The freedom, purpose, and renewed well-being that come from making this decision now are priceless. If these signs resonate, start by noting the top three things you resent about your job, and the top three you dream of doing.
I once told myself pushing through my own clear signals was safer. It wasn't. Don't make that same mistake. Your next chapter is waiting.
Ready to Plan Your Retirement?
Revisit your top signs, then jump to our 'Charting Your Retirement Journey' timeline above for immediate next steps.