The first Friday arrives without an employer direct deposit hitting your checking account, marking the official switch to drawing from cash reserves.
Stepping away from full-time work between ages 62 and 67 promises complete sovereignty over your days. Yet the moment your commute ends, colleagues, extended family, and financial salespeople immediately recalibrate their expectations, treating your newly cleared hours as an unallocated public resource.
Managing the shift from a predictable paycheck to systematic distributions is demanding enough without having to defend your balance sheet and daytime schedule against outside entitlement.
Setting explicit, non-negotiable boundaries during your first thirty days protects your relationships, shields your accumulated savings, and keeps your retirement entirely your own.
Quick Tips Before You Start
Hold a 30-Day Freeze
Decline all long-term volunteer roles and non-essential financial products during month one.
Guard Daytime Hours
Treat 9 AM to 3 PM as personal transition time rather than open availability for family errands.
Script Financial Deflections
Use neutral statements about working with a fee-only planner to shut down prying questions.
Protect Grandparent Limits
Cap family child care assistance at fixed, agreed hours before unmanaged requests escalate.
Shifts in Professional and Social Circles
Leaving the workplace severs the daily operational ties that formed your primary social environment for decades.
Understanding how professional relationships instantly transform prevents unexpected emotional shock while shielding your daily calendar from working friends who project their leisure fantasies onto your new schedule.
1. Former coworkers stop reaching out once workplace utility ends
Most new retirees assume their daily office friendships will survive without the office. That expectation falls apart during the first two weeks away from the desk.
Within fourteen days of surrendering your building badge and email login, project threads, direct messages, and quick desk check-ins drop to zero. That silence feels personal, but workplace connection is fueled by shared tasks. Once your day-to-day utility to the team ends, the transactional glue disappears with it.
Accepting that professional utility drove those daily interactions protects you from feeling discarded. It lets you stop hunting for ongoing workplace validation and direct your energy toward real personal connections.
💡 Tip: Archive your former corporate contact list so you are not left waiting on check-ins.
Retirement Boundary Terms Explained
2. Working peers assume you have endless time for midday plans
On my third Tuesday off the clock, my phone lit up at 10:15 a.m. with an invitation to a two-hour brunch from a working neighbor who had taken a sudden remote day.
While former workplace colleagues drift away, friends still on the job often swing to the opposite extreme. They project their personal leisure fantasies onto your open calendar, expecting instant availability for spontaneous mid-morning calls, long restaurant lunches, or afternoon errands while you are actively trying to construct a focused daily rhythm.
Treating daytime pings like obligations turns your schedule into an unscheduled void.
Constantly answering every text during regular 9-to-5 working hours teaches peers that your retirement is idle time waiting to be filled by their convenience.
Run a five-minute check-in every Sunday evening during month one. Review two concrete numbers: how many short-notice daytime plans you accepted, and how many hours remained dedicated to your own personal transition. If outside invites hijacked your mornings, correct course immediately by declining spontaneous meetups and suggesting pre-scheduled evening or weekend times instead.
💡 PRO TIP
Protect Your Daytime Calendar Structure
Block 9:00 AM to 1:00 PM for personal projects, exercise, and household finances so spontaneous requests do not derail your transition.
3. Acquaintances bluntly pry into your personal finances
That sudden, tight knot in your stomach when a casual acquaintance leans in to ask how you can afford to leave work is completely justified.
People who never once asked about your annual salary suddenly feel entitled to ask about your portfolio size, exact pension formulas, or whether you claimed Social Security between ages 62 and 67. In almost every case, they are using your transition to benchmark their own preparedness against your personal balance sheet.
Revealing real numbers invites jealousy and unsolicited scrutiny.
Sharing your monthly distribution rate or cash reserves can also trigger uncomfortable borrowing inquiries from people who assume retirement assets represent idle, surplus cash.
Set up a simple, repeatable deflection system whenever someone probes your accounts. Tell them your distribution schedule was structured with a fee-only planner to cover basic household baseline expenses, then change the subject. It provides a polite, definitive barrier, shares zero dollar figures, and ends invasive prying before it starts.
Social Financial Boundaries — At a Glance
🛑 Direct Questions
Inquire on nest egg size
💬 Standard Reply
Neutral fiduciary script
🔒 Private Data
Distribution percentages
🎯 Goal
Preserve privacy
Key Boundary
Never disclose portfolio totals or exact distribution checks to casual acquaintances.
4. Peers near retirement project their own financial anxieties onto you
Colleagues who are still years away from leaving the workforce will instinctively project their personal financial fears onto your newly open schedule.
When coworkers cannot extract your account balances, their uncertainty often converts into unsolicited warnings about brutal market drops, persistent inflation, and outliving your savings. These lectures rarely describe your balance sheet. They stem directly from their own savings shortfalls, escalating lifestyle overhead, and the deep psychological dread of letting go of a biweekly paycheck.
Their panic belongs entirely to them.
Stepping away from work between ages 62 and 67 requires transitioning from automated compensation to living on cash reserves or initial account withdrawals. That shift demands focus. Absorbing catastrophic forecasts from working acquaintances only triggers second-guessing during the exact month you are establishing your baseline distribution discipline.
You can acknowledge general economic turbulence with a neutral comment without disclosing your target allocation, cash cushion, or specific monthly withdrawal rate. Deflect the topic and keep the conversation general.
Never defend your solvency to an anxious peer.
If outside commentary makes you question your readiness, sit down with a fee-only fiduciary financial planner or a CPA to audit your withdrawal math. A thirty-minute review of your 3.5% to 4% distribution strategy gives you objective confirmation based on your actual holdings, which permanently silences the noise from people who have not done the work.
Relying on a qualified professional protects your peace of mind and keeps your long-term plan insulated from the financial insecurity of former coworkers.
💡 Tip: Refuse to debate market timing or withdrawal rates with anxious coworkers.
Changes in Family Dynamics
Family members frequently misunderstand the purpose of retirement, viewing your open weekday hours as an unallocated domestic resource.
Establishing explicit boundaries with adult children and spouses during week one prevents uncompensated labor from consuming your newfound autonomy.
5. Adult children treat your open calendar as on-demand childcare
Publish a clear, non-negotiable schedule for family support before your adult children begin treating your retirement as free, full-time daycare coverage.
Without predefined boundaries, unpaid caregiving by grandparents quickly expands to 10 to 15 hours per week during the first thirty days. That unstructured commitment introduces unexpected fuel costs, dining expenses, and constant calendar disruptions. Automate the boundary by offering one fixed window – such as Thursday from 9 a.m. to 1 p.m. – and keep that rule static.
Locking in a single recurring block removes the weekly negotiation, preserves family warmth, and keeps the remaining four weekdays reserved for your own retirement priorities.
🗓️ Establishing Domestic Boundaries
Week 1: Audit Open Requests
List every recurring family request for daytime assistance or errand support.
Week 2: Set Caregiving Limits
Define exact hours for child care and decline open-ended availability.
Week 3: Protect Morning Hours
Reserve core morning hours exclusively for personal transition tasks.
Week 4: Review Calendar Load
Assess your weekly schedule to confirm discretionary time remains intact.
6. Relatives ask for free labor on weekday home and repair projects
Relatives often look at an open retirement calendar as an unallocated public resource rather than earned personal time. Agreeing to sit through a four-hour appliance delivery window or run midday errands converts your retirement into an unpaid maintenance job, fracturing the daily structure you need to build during your first thirty days off the payroll.
Availability is not an obligation to work.
When a relative asks you to monitor a plumber at their house to avoid taking time off work, a direct refusal establishes the necessary standard. Explain that your weekdays are fully booked with personal transition tasks. Giving a clear refusal in month one stops family chore delegation before someone else's household logistics permanently consume your week.
Guarding your daytime hours ensures your retirement remains an independently governed asset, leaving your energy focused on your own home, health, and schedule.
Handling Family Requests in Month One
Unhealthy Patterns
- Accepting last-minute errand requests
- Providing open-ended child care hours
- Subsidizing group family vacations
- Managing contractor visits for relatives
Firm Day-One Rules
- Scheduling family help on fixed days
- Capping caregiving at agreed weekly limits
- Enforcing standard equal splits on meals
- Directing relatives to manage their own trades
7. Family members assume your financial situation is either lavish or fragile
Within 30 days of leaving work, relatives often polarize your balance sheet, treating retirement accounts as unallocated cash ready for zero-interest personal loans or group vacation subsidies.
Meanwhile, anxious relatives scrutinize ordinary restaurant bills or weekend travel plans, questioning normal discretionary spending as reckless the moment regular paychecks stop coming in. You do not need to share withdrawal math or explain your budget to reset these expectations.
Start with one small move: insist on an even split on the next $50 dinner tab. Drawing that simple line early stops financial supervision and keeps your distribution rules private without drama.
💡 Tip: Split family restaurant tabs evenly and decline requests to fund extended group vacations.
⚠️ COMMON MISTAKE
Do Not Disclose Distribution Rules to Relatives
Sharing exact monthly retirement distributions invites unsolicited spending critiques from family members who do not understand your overall plan.
8. Your spouse or partner micro-manages your daily routine
Worrying about unexpected tension with your partner during your first month of retirement is completely normal, and it does not mean your shared future is in jeopardy.
Full-time cohabitation instantly upends years of established domestic rhythms. An already-retired or homemaking partner often begins tracking your hourly movements, critiquing your daily projects, and assuming you want to share every daytime domestic chore. Shared kitchen counters and competing background noise turn peaceful mornings into territory squabbles within the first seven days.
Unspoken routines quickly turn into mutual surveillance.
Give yourself explicit permission to scale back joint activities instead of forcing constant companionship. You are not obligated to coordinate midday lunches, run errands as a pair, or take on joint household tasks simply because you are both home during hours that used to belong to an employer.
Claim a distinct workspace in a separate room, commit to independent hobbies outside the house, and agree on clear blocks of solo time to protect your relationship while you both adapt.
Interactions with the Outside World
External institutions and commercial businesses adjust their posture the moment your corporate affiliation ends.
Navigating aggressive financial product pitches, community leadership solicitations, and shifts in public status requires deliberate boundary management.
9. Financial salespeople aggressively pitch account rollovers and insurance
I opened my mailbox eleven days after turning in my office badge and counted six separate glossy brochures promising safe returns in a turbulent market.
When human resources logs your retirement status, public data feeds and commercial databases flag your old workplace retirement plan as prime territory for moving. Suddenly, your name lands on outbound lead lists for insurance agents and commission-driven brokers eager to capture your nest egg before you even settle into a morning routine.
The pitch always sounds like protection.
Advisors will urge you to shift a $400,000 or $600,000 workplace balance into equity-indexed annuities with steep surrender charges, complex income riders, or managed accounts carrying 1.5% annual fees. They frame these contracts as safety against market drops, but the trade-off is locked-up liquidity and ongoing costs that quietly chip away at your principal.
Direct transfers from an employer plan to an individual retirement account take two to four weeks to clear. That window requires you to audit custodial charges and fund expense ratios on your own terms rather than signing under pressure.
Put a mandatory 30-day freeze on all new financial products.
Tell every solicitor that your accounts are locked during a scheduled distribution review. Giving yourself a full month prevents impulsive commitments, keeps your starting cash reserves intact, and gives you space to compare low-cost index options without a salesperson breathing down your neck.
The First 30 Days: Financial Management
10. Community organizations recruit you heavily for volunteer leadership
Many assume joining a community board immediately provides purpose without corporate stress. In reality, local clubs and homeowners associations hunt for recent retirees to take on uncompensated operational and treasurer roles.
Stepping into committee leadership turns into an unpaid 20-to-30-hour weekly job before travel plans, morning workouts, or daily rhythms even settle. Saying no feels uncomfortable, especially when neighbors push, but placing a strict six-month freeze on binding commitments gives you the space to test what you actually want to support.
Protecting your initial months costs popularity but saves your schedule.
💡 Tip: Tell volunteer coordinators you are observing a strict 90-day transition pause on new commitments.
11. Service businesses and strangers treat you as an elder rather than a professional
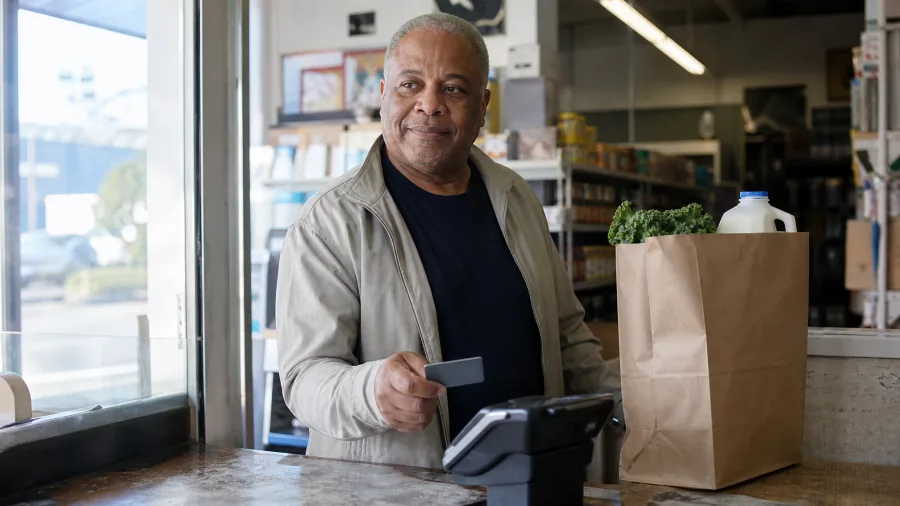
Prepare for a sharp change in how strangers address you during standard business hours. Leaving behind workplace badges and tailored clothing for casual weekday errands immediately alters how retail workers, auto mechanics, and service counters categorize your presence.
The initial misstep is reacting with silent resentment when a grocery clerk offers an unprompted senior discount or a medical receptionist uses an overly familiar, simplified cadence. After decades spent in professional settings where your background commanded baseline authority, hearing patronizing labels during a routine morning errand creates an unexpected identity shock.
Losing public professional validation catches most retirees off guard.
Many people attempt to correct the balance by subtly dropping past titles or asserting managerial experience into casual service interactions. Trying to reclaim professional respect from frontline staff who are simply ringing up hardware or groceries only highlights personal insecurity and prolongs the struggle to find grounding in your new routine.
Service workers are not making a considered judgment about your capabilities. They are managing high-volume shifts and reacting quickly to daytime demographic cues.
Anchor your self-worth in personal autonomy, steady financial reserves, and self-chosen daily projects rather than an old business card. When a clerk knocks five dollars off your ticket with an unsolicited discount, take the savings without debate, finish the errand, and protect your peace of mind.
Viewing public errands as simple logistical tasks rather than venues for status confirmation keeps your attention focused on your own calendar. You no longer need external validation from strangers to confirm the value of your time.
True independence means you never have to prove your background.
Frequently Asked Questions
How long does a 401(k) rollover to an IRA usually take?
Direct rollovers from an employer 401(k) to an individual retirement account typically require two to four weeks to process depending on plan administrator requirements. Maintain regular contact with both custodians to confirm funds transfer directly without tax withholding.
What should I say when relatives ask for personal loans in month one?
State plainly that your retirement portfolio is allocated strictly to generate regular living distributions through a structured plan. Explaining that funds are committed to an automated schedule shuts down borrowing requests without creating hostile arguments.
How many hours of grand-parenting child care should I commit to initially?
Start with a modest, fixed schedule such as four to six hours per week rather than open availability. Establishing tight boundaries early prevents unmanaged caregiving from expanding into an uncompensated 15-hour weekly job.
Why should I wait thirty days before buying new financial products?
A mandatory thirty-day freeze prevents making emotional, rushed decisions on complex annuities or high-fee management wrap accounts while adjusting to your new cash flow. It gives you time to audit fees and evaluate low-cost index options calmly.
How do I handle the feeling of losing professional workplace status?
Acknowledge that workplace relationships were largely built on transactional utility. Focus on establishing independent daily routines, personal health goals, and self-directed projects that provide purpose outside a corporate job title.
Guarding Your Calendar After You Retire
Protect your autonomy during week one by deploying clear parameters before outside requests harden into obligations. Tell working peers that weekdays are committed to establishing your new routine, cap family caregiving at a single defined block like Tuesday mornings from 9 to 12, and remind financial inquiries that your assets are locked into a structured distribution plan.
Enforcing these lines in your first seven days ensures your time serves your own priorities rather than everyone else's convenience. When the next monthly transfer moves from cash reserves into checking, it funds a schedule designed entirely by you.
Audit Your Day-One Boundaries Today
Review your weekly calendar and establish your 30-day commitment freeze before outside expectations take over your schedule.