Voluntarily writing a check to the IRS when you do not have to feels entirely wrong.
For decades, the entire point of personal finance was keeping taxes as low as possible every single April, treating every dollar sent to Washington as a loss.
Then I turned 63, looked at my traditional retirement accounts, and realized that tax deferral was starting to look less like a shelter and more like a ticking time bomb.
I deliberately triggered a higher tax bracket by moving a chunk of my tax-deferred savings into a Roth account, and it was the best financial move I made all year.
You do not need to copy my exact numbers, but you do need to understand why paying taxes now can sometimes buy you total freedom later.
Quick Tips Before You Start
Target the Gap
Look for the income valley between retirement and Social Security.
Keep Brackets Low
Never jump past your current marginal tax bracket in a single year.
Use Taxable Cash
Pay the conversion tax from a separate savings account, not the fund.
1. Accepting the Short-Term Tax Hit
People assume that paying taxes early destroys your compounding power.
It feels like throwing cash straight into a bonfire.
When I first looked at writing a five-figure check to the IRS just to move my own money around, my stomach dropped.
traditional pre-tax accounts let you deduct contributions today, but every single dollar you withdraw later gets taxed at whatever ordinary income rate exists then, including your eventual mandatory withdrawals.
When you convert early, you pay the tax bill right now at known, historically moderate rates, trading a predictable short-term cost for permanent tax-free growth.
The trade-off is real, painful, and entirely upfront: your bank account shrinks in April, and your cash flow takes a temporary hit.
Do it anyway because the alternative is letting future tax laws dictate your standard of living.
This week, run a simple calculation on your pre-tax balance to see what a $5,000 or $10,000 chunk would cost you at your current marginal rate.
💡 PRO TIP
The Golden Rule of Conversions
Never pay conversion taxes using funds taken out of the retirement account itself, as that triggers additional withholding penalties.
2. Knowing When to Call a CPA
I sat at my kitchen table with a stack of old 1099 forms and a mild sense of panic before I ever moved a single dollar across accounts.
Tax brackets are complicated, and a single mistake can push you into a higher Medicare surcharge bracket without you even realizing it until the bill arrives.
This is the exact moment to run your numbers past a fee-only fiduciary or a certified public accountant who understands retirement sequencing.
I spent two hours with an accountant before moving my first dollar to make sure I wasn't missing a hidden penalty.
It cost me a few hundred dollars in professional fees, which saved me thousands in miscalculated bracket thresholds and kept my cash flow intact.
3. Starting With Small Increments
You do not need to convert your entire retirement account in one massive lump sum.
The fear of a giant tax bill freezes people into doing nothing at all, which misses the entire point of incremental planning. Moving a smaller amount keeps you entirely out of trouble while still letting you chip away at future required withdrawals.
Even $2,500 moved incrementally each year builds momentum without shocking your cash flow. It creates a manageable tax obligation you can pay out of regular savings instead of scrambling.
Consistency beats ambition every single time when dealing with tax planning. Doing a modest slice annually lets you test your withholding accuracy without risking a massive penalty in April.
Start small, watch how it affects your return, and scale up next year.
Conversion Impact Snapshot
4. Beating the RMD Time Bomb
At age seventy-three, the rules change entirely whether you want them to or not.
Required Minimum Distributions force you to withdraw a calculated percentage of your tax-deferred accounts every single year, and that involuntary income can instantly push you into a higher tax bracket while driving up your Medicare premiums. Waiting until the government forces your hand turns a manageable tax bill into an expensive annual ambush.
Convert a portion of those funds early to defang the rule before the clock runs out.
5. Avoiding the Bracket Creep Trap
It is completely normal to look at a lower-income year and want to clear out your traditional accounts in one frantic sweep.
The mechanism that trips people up here is the progressive tax system itself: moving too much at once shoves your dollars right past the 12% or 22% lines and straight into a 32% or 35% bracket you never meant to touch. I almost did this myself when I retired early, seeing a massive block of savings sitting there waiting for a lower rate.
Fill up your current bracket line, stop right before the edge, and save the rest for next January. This week, check your exact taxable room left in your current bracket before doing anything.
⚠️ COMMON MISTAKE
Don't Ignore Medicare IRMAA
Pushing your modified adjusted gross income too high in a conversion year can permanently spike your monthly Medicare Part B and D premiums.
6. Automating Your Annual Transfers
Can you actually trust yourself to remember a complex tax move every single autumn while life gets busy?
Usually, the answer is no, which is why relying on pure willpower to handle annual financial maneuvers almost always results in procrastination.
When December rolls around and the year-end deadline is breathing down your neck, it is far too easy to freeze up and let another twelve months slip by without moving your money.
The fix is to take the decision away from your future stressed-out self by setting a recurring calendar reminder for every October to evaluate your year-to-date income and decide on a specific target figure.
Once you have that number, instruct your brokerage to execute a partial transfer automatically before December 31st, taking about ten minutes to set up so you never have to stress about missing the deadline again.
7. Moving Funds in Down Markets
Shift your conversion windows to match market downturns, moving shares when asset prices drop.
Transferring investments during a market dip lets you lock in lower valuations, moving more units for the exact same tax cost. When the market recovers, those extra shares bounce back inside the tax-free bucket instead of the tax-deferred one, maximizing your long-term spread.
Check your portfolio during the next quarterly correction and convert a targeted $5,000 block of depreciated shares before the recovery begins.
8. My Own Conversion Wake-Up Call
I spent years believing that keeping every dollar in a tax-deferred account was the smartest strategy possible.
Then I ran the projected numbers for my mandatory withdrawals at age 75 and nearly dropped my pen.
Between my traditional IRA, future social security, and pension income, I was staring down a tax bracket higher than the one I had during my peak earning years.
The math stopped making sense.
I was simply deferring a tax debt to a future version of myself who would have less flexibility to absorb the blow.
So I broke my own rule, paid an extra $2,400 in taxes that spring, and moved $20,000 across the line.
My portfolio looked smaller that month, but my long-term peace of mind finally felt secure.
That single move completely rewired how I view tax planning.
Tax deferral is not tax elimination. It is just borrowing against your future flexibility.
— What retirement planners keep repeating
9. Using the Three-Bucket Strategy
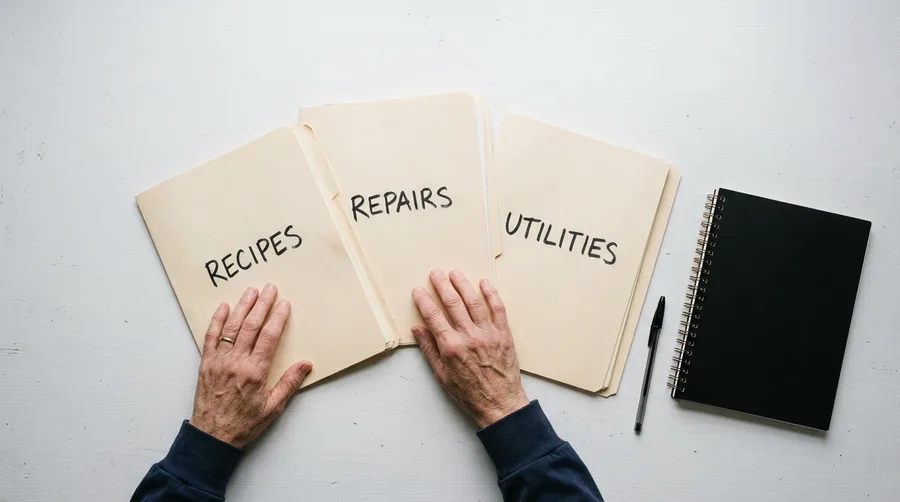
Keep your money sorted into three distinct buckets: cash reserves, tax-deferred holdings, and tax-free Roth assets.
This structure lets you control your taxable income down to the dollar every single year.
10. Reviewing Your Bracket Every October
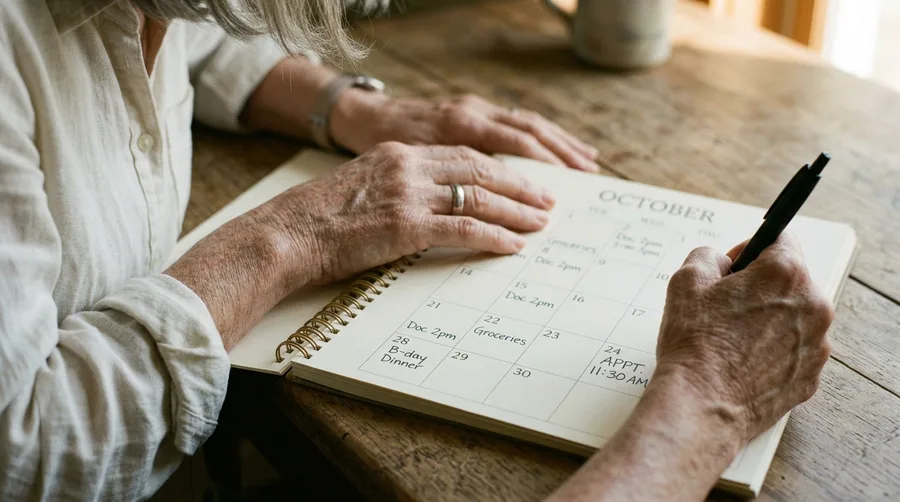
April tax season feels like an ambush when you have spent the entire previous year flying blind.
We wait for forms to arrive in the mail, hand them over with a knot in our stomach, and let whoever is filing tell us what the damage is.
You can step off that treadmill completely by moving your review date to October instead.
Pulling your year-to-date earnings in the middle of autumn gives you a clean window to look at where your income actually sits against the tax brackets.
You take your total wages, add whatever traditional retirement distributions you have taken so far, and look at the gap between your current level and the top edge of your bracket.
If you have $4,500 of breathing room before you tip into the next federal bracket, you can choose to convert exactly that amount of traditional funds to Roth right then.
It takes about twenty minutes with a calculator and your latest pay stub, but it turns tax planning from a panic into a deliberate choice.
Once you make your move for the year, close the folder and leave it alone until next October.
11. Dropping the Fear of Brackets
Stop treating tax brackets like enemy territory.
Embrace paying a fair share now to secure absolute freedom later.
12. Scaling Back When Cash Gets Tight
You do not have to keep moving money when life decides to get expensive.
It is completely fine to pause your conversions during a high-expense year.
Life happens, roofs leak, and medical bills pop up unexpectedly.
Scale your transfers back to zero for twelve months, let your cash flow recover, and pick right back up when things settle down without feeling like you failed.
This week, check your cash reserves and cancel any scheduled transfer if your bank account dropped by more than $1,500.
13. Targeting the Retirement Income Valley
The absolute best window for a Roth conversion sits in the gap between stopping work and claiming Social Security.
During those specific years, your earned income drops to zero while your mandatory benefits have not started yet.
Move $15,000 to $30,000 annually through this exact valley to pay historically low tax rates on massive sums of future growth.
Yearly Conversion Breakdown
14. Automating Tax Withholding Payments
I forgot about the IRS withholding form on my first conversion and spent a miserable April writing a check I definitely had not budgeted for.
Brokerages usually only take out standard federal and state percentages unless you specifically tell them otherwise, which leaves a gap when you pull a larger chunk over.
Fix it this week by logging into your electronic tax payment portal and scheduling automated quarterly transfers straight from your checking account every three months.
15. Watching My Portfolio Finally Breathe
I used to track my net worth with a lingering sense of anxiety over how much of it actually belonged to the government.
Every time the market rallied, I mentally discounted the total by whatever tax rate I expected to pay later in life.
Moving those assets across the line changed how the balance sheet felt.
When I look at my Roth accounts today, every single comma is 100% mine to spend, invest, or leave behind without a single tax form attached.
It took three years of intentional, sometimes uncomfortable tax bills to get here.
I volunteered for a bigger bill then, and it bought me complete financial independence now.
You can do the exact same thing, one small transfer at a time.
Conversion Journey Roadmap
Frequently Asked Questions
Is it too late to start Roth conversions in my sixties?
Not at all. Your sixties often represent the ideal window because earned income drops while mandatory Social Security and RMDs have not started yet.
Should I pay conversion taxes out of my retirement funds?
Never. Withdrawing money from the account to pay taxes destroys compounding growth and triggers extra penalties. Always pay from outside cash.
What happens if I push myself into a higher tax bracket?
Only the dollars crossing the bracket threshold are taxed at the higher rate, not your entire income. However, watch out for Medicare IRMAA cliffs.
How many years should I spread my conversions across?
It depends entirely on your traditional account balance and current bracket space. Most people space them across five to ten years to stay low.
Make It Stick
You do not need to overhaul your entire retirement plan by tomorrow morning.
Pick one small transfer amount, check your current tax bracket, and move a manageable slice this season to buy yourself long-term freedom.
Take Control of Your Future Taxes
Join our community for weekly practical money strategies that keep more cash in your pocket.