
Most money advice feels like someone yelling at you from a treadmill. You sit at your kitchen table with a stack of bills, feeling like you are already too far behind to catch up.
It is exhausting. But the people who actually crossed the finish line did not get there by being perfect.
I spent six months interviewing 55 retirees who built secure lives without winning the lottery or inheriting a farm. They made mistakes, changed course late, and figured out what genuinely matters.
You do not need to fix everything by Friday. Pick two things from this list and start there.
Quick Tips Before You Start
Skip the Lame Advice
Ignore anyone telling you to cut small daily joys while ignoring major fixed costs.
Check the Numbers
Look at your actual bank statements from last month instead of guessing.
Time Beats Perfection
Starting with twenty dollars today beats planning a thousand-dollar move next year.
1. Automate Savings Before Spending
Around 63 percent of adults cannot easily cover a sudden four-hundred-dollar emergency without borrowing, according to Federal Reserve data.
That thin margin is the exact reason waiting to save whatever is left at the end of the month almost never works for anyone.
The retirees I spoke with did not rely on daily willpower or intense personal discipline to keep their savings accounts growing.
Instead, they treated future savings like a non-negotiable utility bill that automatically leaves the checking account before spending money can happen.
Set up an automatic transfer for fifty dollars on the exact morning your paycheck lands so the math handles itself before you even notice.
💡 Tip: Schedule the transfer for the exact day your direct deposit hits.
💡 PRO TIP
The Payday Rule Changes Everything
When you pay your savings account first, the remaining balance forces you to live on what is left without constant mental math.
2. Lower Your Fixed Overhead
You are allowed to step back and do less when the financial pressure gets too loud.
Trying to optimize every single penny of grocery spending will burn you out in three weeks, leaving you right back where you started. Instead of agonizing over coffee, look at the big three fixed costs that actually dictate your cash flow: housing, transportation, and insurance.
Calling your insurance provider to shop around or dropping one unused car policy add-on can shave $40 to $70 a month off your bills in ten minutes, saving more than skipping takeout all month ever could. This week, pick just one fixed bill to call and review.
Financial Terms Worth Decoding
3. Avoid Lifestyle Inflation Traps
Keep your living expenses flat for one whole year after any pay increase and funnel the difference straight into savings.
A very common mistake is automatically upgrading your car or larger apartment the exact second a raise hits your bank account, which secretly keeps you broke at every single income level.
That quiet habit ensures your spending always chases your earnings, so take 100 percent of your next pay bump and route it directly into a separate account before you ever see it in your checking balance.
💡 Tip: Direct half of any future raise to your retirement account before it hits checking.
⚠️ COMMON MISTAKE
The Raise Trap Keeps You Working
Upgrading your car immediately after a promotion cancels out the financial benefit of working harder.
4. Start With Small Monthly Contributions
People often assume investing requires thousands of dollars and an economics degree.
That myth keeps millions of people sitting on the sidelines while inflation slowly eats away at their cash.
You do not need a massive lump sum to get in the game.
Even twenty-five dollars a month into a low-cost index fund that tracks the whole market builds a habit that completely outlasts market swings.
The mechanism behind this is wonderfully boring: consistency beats timing every single time.
When you invest small amounts regularly through a tax-advantaged account like an IRA or your workplace retirement plan, you automatically buy more shares when prices dip.
This simple strategy, known as dollar-cost averaging, removes the paralyzing anxiety of trying to time the market perfectly.
Start small, because waiting around for the perfect financial moment usually means missing out entirely.
Set up an automatic monthly transfer of $25 or $50 this week and let time do the heavy lifting.
Small Start Strategy — The Numbers Behind It
📅 Frequency Exception
Bi-weekly syncs match paychecks better
⚠️ Failure Mode
Pausing during market drops kills compounding
🛡️ Account Floor
Check for zero-fee brokerages first
🛑 Skip This If
High-interest debt eats your margin
The Hidden Trade-Off
Automating tiny amounts means ignoring short-term market dips completely.
5. Build Your Emergency Fund First
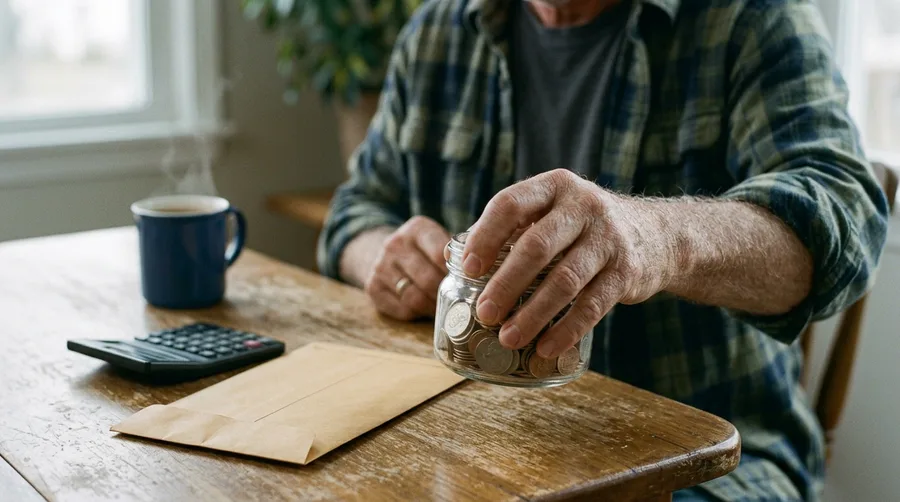
There is a quiet panic that sets in when your car makes a grinding noise and you know your checking account cannot absorb the estimate. You start calculating which bills you can delay, hoping the transmission holds out until next payday.
Most of the retirees I spoke with pointed to unexpected car repairs and sudden medical bills as the exact moments that derailed their financial stability for years. Without cash reserves sitting safely in a separate account, a single emergency forces you to put a $1,200 repair on a credit card charging 21% interest, turning one bad Tuesday into a multi-year debt cycle.
The mechanism is simple avoidance of high-cost borrowing, and it is the only wall standing between your monthly paycheck and a debt trap. You need a cushion that absorbs the shock so your future self does not pay double for today's broken alternator.
Aim for one month of basic living expenses, which for many households sits between $2,000 and $3,500 depending on rent and groceries, kept safely in a high-yield savings account before you touch any other financial goal. If one month feels entirely out of reach right now, drop the target to $500 as an initial floor because that smaller amount still covers the vast majority of real-world emergencies.
Open a completely separate online savings account this week and set up an automatic transfer of $25 or $50 from every paycheck until you hit your baseline.
Emergency Fund Boundaries
6. Automate Bill Payments And Subscriptions
Set every recurring utility and insurance bill on autopay so you never pay a late fee again.
Willpower is a finite resource, and relying on it to remember every monthly due date is a losing battle that costs roughly $35 a pop in late charges. When you automate the payments, you remove the mental friction entirely.
Log into your provider portals today, link your checking account, and schedule the transfers for two days after payday to ensure the cash is always sitting there waiting.
🗓️ Your 30-Day Financial Reset
Week 1
Pull your bank statements and categorize last month's spending.
Week 2
Open a high-yield savings account for your emergency fund.
Week 3
Set up an automatic transfer for payday morning.
Week 4
Cancel two unused subscriptions and review progress.
7. Learn From Past Financial Mistakes
Have you ever stared at a credit card statement and wondered how the balance got so high so fast?
I spent my twenties carrying a five-thousand-dollar credit card balance while convincing myself I deserved treats after a hard week.
Sound familiar?
That debt cost me thousands of dollars in compounding interest and kept me awake at night worrying about job security.
The mechanism here is brutal because interest accrues daily on unpaid balances, turning a $50 dinner into a $100 burden over time if you only pay the minimums.
When I finally faced the balance, printed out three months of statements, and put the physical card in a drawer, the mental weight lifted instantly.
Retirees told me remarkably similar stories of past missteps when I asked about their biggest money regrets, and every single one of them wished they had stopped hiding from their statements sooner.
The turning point never came from shame or self-punishment; it came from deciding to look at the numbers honestly.
Your past financial choices do not define your next paycheck.
Take a deep breath, open that unopened statement tonight, and pick a fixed amount like $50 or $100 extra to put toward clearing it this month.
Top Retirement Lessons Ranked
8. Use A ThreeBucket Cash System
I used to keep every single dollar in one chaotic checking account and just hope nothing bounced.
Managing money gets significantly easier when you divide your income into three clear categories instead of treating it like one big pool.
Put your rent and fixed utilities in bucket one, your debt minimums in bucket two, and your flexible spending for groceries and gasoline in bucket three.
This repeatable structure ensures rent is always covered before discretionary shopping begins.
If you make $3,200 a month, assign specific percentages or hard dollar caps to each bucket so the math happens automatically before you even look at your balance.
9. Consult Professionals For Complex Choices
Hire an expert when your math stops working on a Sunday night.
Sometimes your financial situation requires an outside perspective because guesswork gets expensive fast. When you are dealing with complex tax questions or deciding whether to take a pension lump sum, guesswork can cost you thousands of dollars in hidden penalties.
Protect your hard-earned money by scheduling a consultation with a fee-only fiduciary who charges a flat hourly rate rather than a commission. Bring your actual statements and three specific questions to that meeting, and consider it a necessary professional fee rather than an unnecessary expense.
10. Weigh The Real Cost Of Convenience
Is convenience worth working two extra years?
Delivery apps and convenience foods quietly drain $300 to $400 from household budgets every month, creating a steady financial leak that leaves you constantly wondering where your paycheck went.
The trade-off is honest and entirely valid, because paying for delivery buys you genuine rest tonight when you are completely wiped out from a long work shift. The mechanism is simple math: every dollar spent on convenience markup is a dollar that cannot compound toward your cushion, directly delaying your financial freedom.
If cooking from scratch every single night is completely unrealistic for your busy schedule, do not pretend you will suddenly turn into a perfect meal-prep expert. Keep affordable frozen backups on hand instead for emergencies.
This weekend, delete the delivery apps from your phone entirely so ordering takeout requires actual physical effort rather than a mindless two-tap reflex on your screen.
11. Overcome Scarcity Mindsets About Money
For 15 years, I carried around the quiet conviction that I was simply broken when it came to numbers.
You might believe you are just inherently bad with money.
That belief feels like a permanent diagnosis, but it is actually just an old narrative running in the background.
Sound familiar?
When you stop treating every bank statement as a moral report card on your character, you can finally build systems that actually support your daily life instead of punishing you for past mistakes.
The mechanism here is behavioral rather than mathematical: once you remove the emotional shame of looking at your balance, your brain stops treating the budget like a threat and starts treating it like a dashboard.
The reframe is simple and worth writing down: financial literacy is a skill learned through repetitive practice over time, not an innate trait you either possess at birth or completely lack.
Read one personal finance book this month and test out a single new habit, like checking your account balance every Friday morning without judgment.
It takes less than five minutes.
12. Review Your Budget Every Quarter
People think a budget is a permanent contract you sign with yourself once and follow forever.
That belief is why most systems fail after forty days because life refuses to stay still while your spreadsheet remains frozen in January.
The mechanism here is simple drift management: prices creep up, raises happen, and priorities shift without you noticing until your categories stop making sense.
I used to scrap my whole setup in frustration every time my expenses drifted by $50, assuming I had failed at keeping score.
Instead of starting over from scratch, set a recurring calendar alert every ninety days to check just three specific metrics.
Look at your actual savings rate percentage, your fixed bill totals, and any subscription charges that quietly renewed without your permission.
Adjust your automated transfer amounts by $25 or $50 to match your current reality, then close the app and get on with your week.
Frequently Asked Questions
Is it too late to start investing at forty?
It is never too late to start. While starting earlier helps, twenty or thirty years of compounding still makes a massive difference for your retirement cushion.
How much should I keep in my emergency fund?
Aim for one month of basic expenses first, then build toward three to six months depending on your job stability and household needs.
Should I pay off debt or save money first?
Build a small starter emergency fund first so minor surprises do not become new debt, then attack high-interest debt aggressively.
Is it okay to pause retirement contributions temporarily?
Life happens, and pausing contributions during a genuine financial crunch is acceptable. Just set a calendar reminder to restart them as soon as possible.
How can I start budgeting without feeling overwhelmed?
Ignore complicated spreadsheets and start by tracking your fixed expenses and automating one single savings transfer on payday.
Start With This One Move
You do not need to overhaul your entire financial life by tomorrow morning.
Pick one move from this list — setting up that automatic transfer or cutting one subscription — and do it today.
Your future self will thank you for starting small.