
Walking away from a steady paycheck at 59 felt less like crossing a finish line and more like stepping off a cliff without a parachute.
You spend decades chasing a specific portfolio balance, convinced that hitting a certain milestone will magically cure your underlying anxiety about money. Then you hit it, you walk out of the office for the last time, and you realize your brain is still wired for scarcity.
It is not too late to build security, but money freedom changes your daily reality in ways nobody talks about on internet forums. This is the honest truth about what happens after you finally secure your freedom, and the exact steps you can take right now to prepare.
I spent my first year making expensive mistakes so you don't have to. You can pick and choose the strategies that fit your life rather than trying to overhaul everything by Friday.
Quick Tips Before You Start
Automate Early
Set your transfers for the morning your paycheck lands.
Track Categories
Keep your fixed expenses separate from discretionary spending.
Build a Buffer
Keep one month of bare expenses in a separate account.
Write It Down
Review your cash flow every single month without fail.
1. Quarterly Portfolio Review Habits
People think hitting your retirement number means you never have to look at a financial spreadsheet again.
That myth will quietly cost you thousands of dollars in unoptimized taxes and missed portfolio adjustments. Here is the actual mechanism at play: your spending fluctuates, tax laws shift, and individual accounts drift away from their target allocations over a span of three months. A structured quarterly review takes roughly forty-five minutes and stops small leaks from turning into major structural problems down the road.
When you open your dashboard, ignore the daily market noise and look at three specific things only: your actual cash outflow, your asset allocation percentages, and any upcoming large expenses scheduled for the next ninety days.
I put this exact review off for the first six months after leaving my job because opening accounts felt too much like going back to work, and I paid for it in avoidable account drift.
Fix this by putting it on the calendar right now. Schedule it for the first Saturday of every new quarter, grab a cup of coffee, and treat it like routine maintenance on a car you plan to drive for decades.
💡 Tip: Keep your quarterly review checklist on a single sticky note inside your desk drawer.
💡 PRO TIP
The Golden Rule of Quarterly Reviews
Never make major portfolio changes during a market drop. Wait forty-eight hours before moving a single dollar.
2. Tax Bracket Management Windows
It is completely normal to feel a knot in your stomach when tax season approaches, but you do not have to stay stuck reacting in April.
Tax surprises are entirely optional.
Waiting until tax season to think about your brackets is like checking your rearview mirror after you already hit the ditch. The tax code actively rewards proactive planning, especially in the crucial window right before and after leaving full-time work, because pulling money from tax-deferred accounts without a strategy can easily push you into a higher bracket and trigger massive Medicare surcharges.
Map out your expected income streams for the next three years every single autumn. Use lower-income windows to execute strategic withdrawals or Roth conversions before mandatory distributions kick in, saving yourself thousands in unnecessary friction.
This requires looking at your actual numbers rather than guessing. Run the projections or sit down with a fee-only fiduciary who understands multi-year tax bridging before the year closes.
Tax Planning — At a Glance
📅 Review Window
Every October
📉 Target Bracket
Lowest viable tier
⚠️ Primary Risk
Bracket creep
💡 Action
Map conversions early
Proactive Rule
Plan your withdrawals three years out to avoid surprise tax spikes.
3. Scaling Back Fixed Overhead
Around 40% of retirees make the mistake of keeping an oversized lifestyle just because the portfolio balance supports it on paper.
You do not have to live like a monk, but trimming fixed monthly obligations gives you psychological safety when markets dip. Even $200 a month saved on fixed bills equals $2,400 a year that doesn't need to be generated by your investments. Drop the subscriptions you haven't touched in six months, and seriously look at downsizing the second car if it mostly sits in the driveway costing you insurance premiums.
You have permission to scale this back slowly over a few months instead of overhauling your entire life by Friday.
Overhead Choices
Old Lifestyle
- Maintaining two newer vehicles
- Paying for unused gym memberships
- Dining out out of sheer habit
- Ignoring annual insurance rate hikes
Lean Freedom
- Owning one reliable car outright
- Swapping subscriptions for local library apps
- Cooking batch meals on Sundays
- Shopping your insurance policies yearly
4. Healthcare Cost Buffer Reality
Stop treating healthcare in early retirement as a vague monthly estimate.
People treat medical costs like an afterthought until a single prescription refill or unexpected dental procedure wipes out three months of cash flow, turning a manageable transition into an emergency fund crisis before Medicare eligibility even begins.
Go to the marketplace website today, check actual ACA premium costs and out-of-pocket maximums for your specific zip code, and set aside a dedicated 15 percent buffer strictly for medical surprises.
⚠️ COMMON MISTAKE
The Healthcare Trap
Do not assume your old employer subsidy carries over affordably. COBRA costs can triple your monthly medical expense overnight.
5. Building the Cash Buffer Floor
I kept roughly $85,000 sitting completely idle in a checking account for the first six months after I left the workforce because the sheer terror of having no paycheck paralyzed my decision-making.
That fear cost me thousands in missed market gains while inflation quietly ate away at my purchasing power in the background.
Start small if you need to, because even $50 a month transferred automatically builds the essential muscle memory for protecting your future self.
Consistency beats intensity every single time when you are trying to break decades of living paycheck to paycheck.
holding twelve to twenty-four months of living expenses in a separate high-yield savings account acts as emotional armor for your investments.
When the broader stock market drops by 20 percent, you never have to sell your equities at a terrible loss just to buy groceries or pay the electric bill.
I eventually moved mine to an entirely different online institution so I would not be tempted to raid it for random home improvements or weekend impulse buys.
The trade-off is completely real: holding that much cash deliberately drags down your overall portfolio return year after year.
Do it anyway, because absolute peace of mind has a tangible mathematical value when you are entirely dependent on your own assets to survive.
This week: open one separate account and schedule your first automatic transfer into it.
Our Top Cash Floor Rules
6. Portfolio Withdrawal Sequence Rules
It feels wrong to empty your taxable accounts while watching your tax-deferred savings sit untouched.
Withdrawing from the wrong account first triggers unnecessary tax penalties and can shorten your portfolio lifespan by a full decade. The mechanism is simple math: pulling from tax-deferred accounts too early forces you into a higher bracket while robbing your Roth savings of time to grow tax-free.
The trade-off is real: managing the sequence takes upfront effort and requires ignoring your short-term comfort. Keep it straightforward by drawing from taxable brokerages first, tax-deferred accounts second, and Roth accounts last. This week, list your accounts by tax category so you are ready before the first withdrawal.
Withdrawal Allocation Order
Federal Reserve SHED framework proportions for tax efficiency
7. The Three-Bucket Cash Flow System
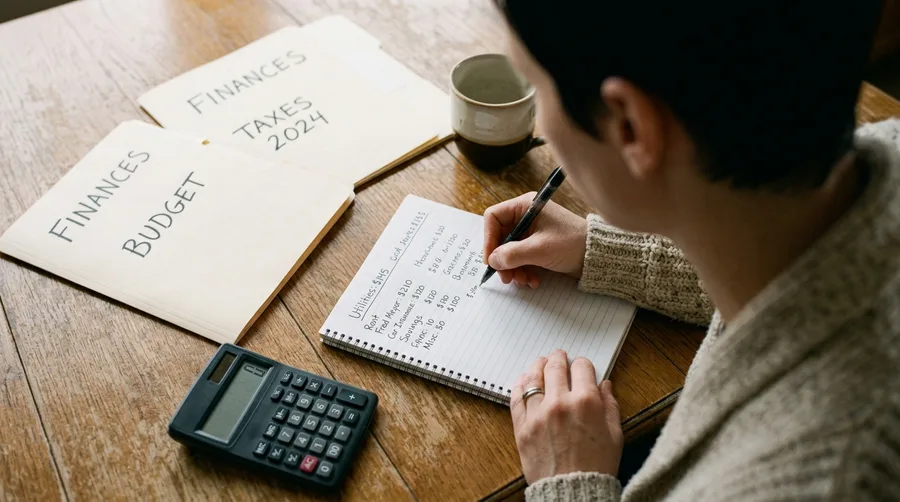
How do you actually manage your everyday money when you no longer get a predictable bi-weekly paycheck deposited into your checking account? You build a repeatable structure so you never have to guess where your cash is going each month.
divide your monthly withdrawals into three distinct buckets on the first of the month. Bucket one handles housing, utilities, and insurance. Bucket two covers debt minimums and healthcare. Bucket three is your weekly discretionary cash.
Never rob your fixed bills to fund entertainment.
If you happen to fall short in any given month, fund buckets one and two fully first, and let bucket three take the inevitable hit instead.
I use separate sub-accounts with different debit cards for each specific category. It feels surprisingly rigid for about two weeks, then it simply becomes second nature. The trade-off is managing multiple accounts instead of one lump sum, which takes about ten extra minutes a month of organization.
That tiny bit of extra administrative friction completely eliminates the constant background hum of financial anxiety that wakes you up.
Simplicity beats complexity every single time.
This week: set up your primary bill-paying account and label it clearly in your banking app so you are ready to begin.
Bucket System Jargon Buster
8. Automating Your Monthly Cash Flow
Set your automated transfers for the exact morning after your monthly distribution lands in your primary checking account.
End-of-month manual transfers mean you only save whatever happened to survive the last thirty days, and what usually survives is absolutely zero. Payday automation completely bypasses that emotional trap by shifting the designated amount before your brain has any time to negotiate with itself or find a justification to spend it elsewhere. This is a timing fix rather than a discipline fix, which changes your success rate overnight.
I used to rely on remembering to move cash manually every single time, and I stalled out for months simply because life got too busy, unexpected expenses popped up, and decision fatigue quietly took over.
It takes about four minutes inside your banking app to locate the recurring transfer settings and link the accounts properly.
Set the rule up once, verify the numbers match your baseline cash flow, and then leave it entirely alone so you never have to waste another ounce of daily willpower on it again.
Frequently Asked Questions
Is it too late to start building wealth at 50?
It is never too late to improve your financial security. Focus on maximizing catch-up contributions, capturing employer matches, and reducing fixed overhead to accelerate your savings rate immediately.
How much cash should I keep in an emergency fund?
Aim for three to six months of bare living expenses, or up to twenty-four months if you are newly retired and want protection against sequence-of-returns risk during a market downturn.
Should I pay off debt or save for retirement first?
Always secure your employer retirement match first, then tackle high-interest debt above 7% APR before accelerating general investments. Balance the math with your personal peace of mind.
Is it okay to pause my savings contributions for a while?
Pausing contributions during acute financial stress or job loss is completely acceptable. Protect your basic food and shelter first, then resume automated saving at a smaller amount when possible.
Your Next Step Toward Financial Freedom
You do not have to overhaul your entire financial life by Friday afternoon. Pick just one move from this list — whether it is setting up an automated transfer or opening a separate cash buffer — and do that today.
Freedom isn't about hitting an arbitrary portfolio number. It is about building a system that gives you choices, protects your peace, and lets you breathe a little easier every single morning.