
Most money advice speaks in a loud, frantic rush, acting as if every missed paycheck is a permanent emergency. It wears you down until you avoid looking at your account balances entirely.
When you sit down with people who have already navigated forty years of paychecks, recessions, and unexpected medical bills, the noise drops away. They do not talk about crypto surges or secret investment hacks. They talk about boring consistency, clear boundaries, and refusing to live with regret.
You do not need to fix your entire financial life by Friday. You just need to borrow a bit of their perspective and pick one solid move to make today.
Quick Tips Before You Start
Drop the Guilt
Shame never helped anyone save a dollar.
Audit One Account
Look at last month's bank statement for hidden subscriptions.
Automate Early
Move savings before you have a chance to spend them.
Pick Two Moves
Ignore the rest of the list until those are done.
1. Consulting a Fee-Only Fiduciary
Around $50,000 in accumulated debt or retirement savings, the numbers get complicated enough that guessing stops working entirely.
Too many people rely on commission-based brokers who push proprietary products with hidden fees. A fee-only fiduciary works for a flat hourly rate and has a legal obligation to put your interests first.
If your tax situation or pension options give you a knot in your stomach, book a one-time consultation. Pay the flat fee of $200 to $400, get a clear map, and stop guessing. This is not admitting defeat.
At a Glance: Fiduciary Check
2. Running Annual Financial Audits
Reviewing your financial standing once a year prevents small leaks from becoming major budget disasters.
Set a recurring calendar reminder for your birthday or the weekend you file your taxes so you never have to guess when it is time.
Look at three specific things during your review: your total debt balances, your fixed subscription costs, and your automatic savings rate.
Do not judge what you find when you open those statements; just record the raw numbers and look at where the cash actually went over the last twelve months.
Small price hikes on insurance, streaming services, and forgotten utilities easily bleed $600 from your checking account without your notice over a single year, making a thirty-minute audit one of the highest-return tasks on your calendar.
⚠️ COMMON MISTAKE
Ignoring Subscription Creep
Small recurring charges under $15 slip past notice for months. Check your statements for unused apps and streaming services twice a year.
3. Avoiding High-Interest Debt Traps
It feels like you are finally doing something responsible when you make that minimum payment every month, but the truth is it is just a holding pattern that feeds the bank.
Most people get trapped by credit card debt because they treat those minimum payments like actual progress, not realizing the math is working against them every single day.
With average credit card interest rates hovering around 20% to 21% according to Federal Reserve data, a $5,000 balance costs roughly $1,000 a year in pure interest charges alone.
That is money vanishing straight into thin air instead of going toward your actual life.
The fix requires brutal honesty and a complete shift in how you handle the plastic in your wallet.
Stop using the cards entirely today, list every single balance from smallest to largest so you can see the whole picture without hiding, and throw every spare dollar at the top one until it is completely gone.
It feels deeply restrictive and annoying at first.
The freedom on the other side is worth every sacrificed takeout dinner.
Do not let interest compound against you another month.
The Cost of Carrying Balances
Federal Reserve G.19 credit benchmarks
4. Starting Retirement Contributions Early
Everyone says you need to wait until your income stabilizes before you even think about retirement accounts.
That logic sounds safe when rent swallows half your paycheck, but it quietly costs you thousands of dollars in missed compounding every single year you delay.
Compound interest means your returns start generating their own returns, turning time into the most valuable asset you have on your balance sheet.
Putting away just $100 a month into a tax-advantaged account like an IRA or a workplace 401(k) starting at age twenty-five creates a wildly different cushion than waiting until forty-five, even if you try to catch up by doubling your monthly contributions later.
Log into your payroll portal today and route just 2% of your gross pay toward your employer's retirement plan before you ever see it in your checking account.
First Month Setup Budget
5. Accepting the Real Cost of Living
Can we just admit how exhausting it is to buy groceries and pay rent right now?
Pretending prices will magically return to 2019 levels is a waste of mental energy that could be spent elsewhere.
The honest trade-off here is brutal: cutting your subscription stack or dining out saves maybe $40 a month, but it takes an annoying afternoon and means genuinely giving things up. Do it anyway to free up cash for essentials. This week, pick one recurring bill over $50 to cancel for good.
💡 PRO TIP
Base Budgets on Reality
Track your actual spending for thirty days before building a budget. Guessing your grocery and utility costs guarantees your plan will fail by week two.
6. Scaling Back Without Giving Up
You do not need to cancel every single joy in your life to build a secure financial foundation.
Extreme deprivation leads straight to burnout and a massive spending binge.
Cut the clutter by dropping $40 or $50 a month in automatic subscriptions you forgot you had, but keep the two routines you actually love.
Consistency beats perfection every single time.
7. Building a Concrete Emergency Fund
I kept my savings in my main checking account for years, watching it slowly drain away into everyday groceries and random online purchases.
Moving cash to a separate high-yield savings account at an entirely different bank changed everything because out of sight truly means out of spend, stopping the endless bleed of accidental withdrawals.
Aim for $1,000 first, then build toward one month of bare expenses by opening that separate external account today and setting up a transfer for your next payday.
Emergency Fund Milestones — The Numbers & Rules
🌱 First Milestone Target
$1,000 cash floor (covers 80% of sudden car and medical repairs)
🏡 Second Milestone Target
$2,500 to $4,000 bare monthly expenses (rent, utilities, food only)
🛡️ Failure Mode
If you dip into it for non-emergencies, pause all extra debt payments until refilled
🏦 Skip This If
You carry credit card debt above 20% APR; split your transfer 50/50 with the balance instead
Transfer Timing
Schedule the automatic transfer for 24 hours after payday so the money moves before temptation does.
8. Using a Three-Bucket System
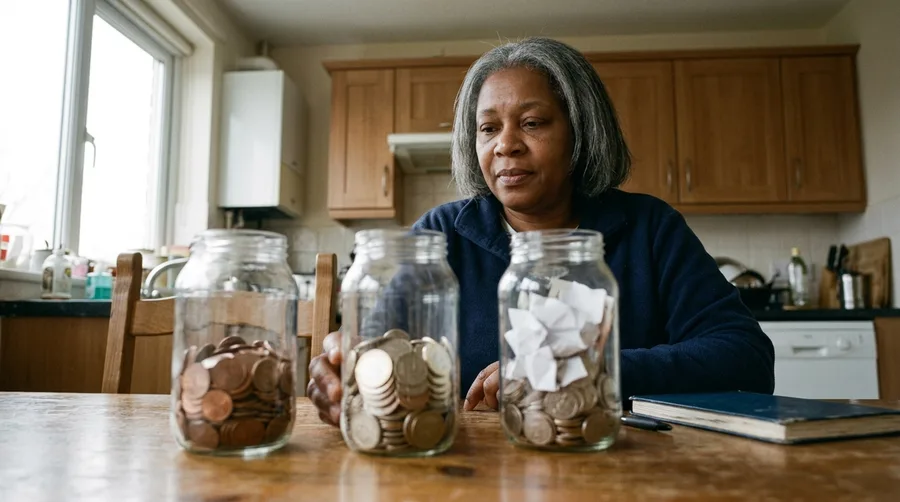
Divide your checking account into three distinct silos right away.
Most people keep everything in one pool and guess what is safe to spend, which is why the balance always feels like a mystery until it hits zero.
Bucket 1 handles your non-negotiable fixed bills like rent, power, and insurance, while Bucket 2 automatically absorbs debt minimums and your baseline savings transfer on the morning your paycheck clears.
Bucket 3 holds whatever is left over, and that remaining amount becomes your flexible weekly cash for groceries, gas, and everyday living without guilt.
I used to keep it all in one place and ended up eating into my rent money for minor weekend expenses more times than I care to admit.
This system removes daily willpower from the equation because the math is settled before you even open your wallet.
Set up your automated split for the first two buckets today and let the leftover money do the rest.
9. Overcoming Scarcity Mindsets
For $50, you can buy a temporary escape from the constant feeling that you are falling behind.
That is the exact price point where impulse spending meets a scarcity mindset, turning a takeout order into a small rebellion against a financial reality that feels entirely out of your control.
Most of us grew up absorbing the quiet lesson that money is fundamentally scarce, morally complicated, or simply something that happens to other people.
That invisible script keeps you paralyzed, too afraid to open your banking app on a Tuesday morning or ask for the raise you earned six months ago because deep down you believe the answer is already no.
Sound familiar?
When you feel like you will never actually get ahead, avoiding the numbers entirely becomes a coping mechanism.
The mechanism of scarcity keeps your nervous system in a constant low-grade panic, which makes long-term planning feel impossible.
You cannot strategize for retirement when your brain is busy managing immediate survival stress.
The shift happens the moment you stop treating your bank statement like a personal report card measuring your moral worth.
Look at the data instead as a dashboard showing you precisely where the car is heading, completely free of judgment or shame.
What I believe now is simple: money is just a tool for buying options, not status or safety.
Start small by checking your balance every single Monday morning without beating yourself up over what happened on the weekend.
That tiny act of looking breaks the spell of avoidance and lets you finally take the wheel.
10. Automating Your Savings Transfers
You stare at the balance on the last day of the month, wondering where every single dollar went while your savings account sits stubbornly at zero.
It is exhausting to feel like you failed another test of discipline, even though you genuinely meant to put something aside.
The truth is that relying on willpower at the end of the pay cycle is a losing battle because life always finds a way to absorb whatever cash is left.
Schedule your savings transfers for the exact morning your paycheck clears, moving $50 or $100 out before you even have a chance to spend it.
When the transfer happens automatically, you learn to live on what is left in checking and you take the daily decision-making completely out of your hands.
It takes about four minutes to set up inside your banking app, and you never have to think about it again once it is running.
11. Embracing the Power of Small Starts
I used to wait around for a mythical paycheck where an extra five hundred dollars would magically appear so I could finally start saving.
Waiting for a big number to save is just a clever way to keep putting it off until tomorrow.
Start with twenty-five dollars a month moved automatically to a separate account, because consistency builds the muscle memory of saving long before the actual balance feels impressive.
You can bump it up by ten dollars every single quarter once your cash flow gets used to the quiet subtraction.
12. Learning From Financial Mistakes
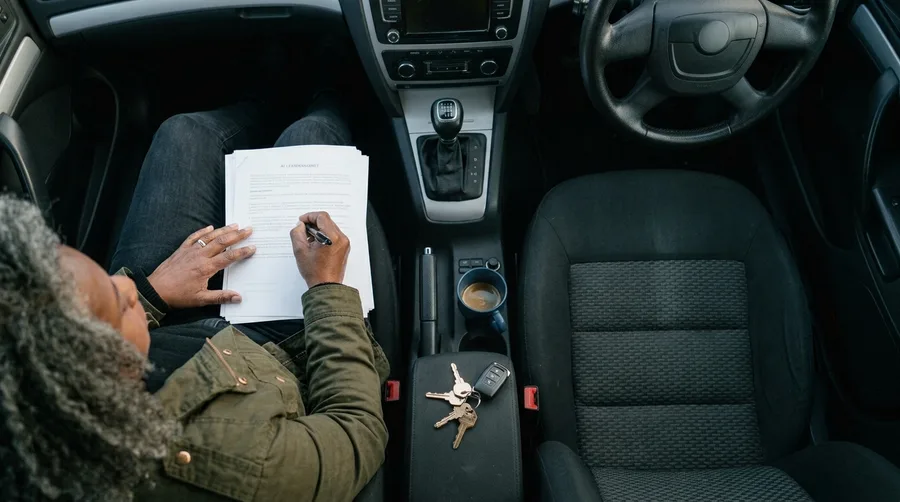
Have you ever signed paperwork at a dealership knowing deep down the numbers did not quite add up?
When I bought my first car, I rolled negative equity from an older loan straight into a new, high-interest financing agreement because I cared entirely about what the monthly payment looked like on paper rather than what the total balance was actually costing me.
That mistake turned into an expensive four thousand dollar lesson in the importance of reading the fine print, asking hard questions, and simply walking away when a deal makes no financial sense.
The underlying mechanism of that kind of trap is simple: lenders count on your focus being drawn to the short-term monthly cash flow while quietly stacking long-term interest against you over a sixty-month term.
Everyone makes financial missteps along the way, but the real secret is letting an expensive mistake actually teach you how to spot the trap next time instead of letting shame keep you from looking at the numbers.
13. Redefining Wealth and Success
Society trains us to measure wealth by luxury cars, square footage, and flashy vacation photos on social media.
That definition is a trap designed to keep you on a treadmill of endless consumption where the finish line always moves.
Older adults who sleep soundly at night usually define wealth very differently: having zero credit card debt, owning a reliable used car outright, and possessing enough cash to handle a broken water heater without panic.
When the average credit card APR sits around 20% to 21% according to Federal Reserve data, paying interest on lifestyle inflation is the quietest way to bleed your future cash flow dry.
True financial security is quiet.
It does not need an audience or an Instagram post to be real.
When you stop trying to impress people who do not care, your monthly savings rate tends to shoot up naturally by $200 or $500 simply because you stopped buying things you never actually wanted.
Focus on buying your peace of mind instead of someone else's aesthetic.
What I believe now: wealth is simply having options when life gets messy.
14. Taking Action With Micro-Steps
Reading about money all afternoon can feel like you are actually doing something, but your bank account does not care about your browser tabs.
It is easy to freeze up when every guide tells you to overhaul your entire life by Friday morning.
You do not need a complete financial transformation today, and trying to fix everything at once is usually why we give up by dinner time.
Momentum comes from a single click rather than a grand plan, and even a tiny transfer changes how you feel about your choices.
Pick one micro-move right now, such as setting up a $25 automatic transfer into a separate account or cancelling one forgotten subscription that keeps draining your checking balance.
The amount feels insignificant, but the mechanism matters because it proves to your brain that you can take control without waiting for a massive raise.
Frequently Asked Questions
Is it too late to start building wealth at 40 or 50?
It is never too late to improve your financial cushion. While starting early helps through compounding, making consistent automated transfers and eliminating high-interest debt in your forties still dramatically changes your financial trajectory.
How much should I keep in my emergency fund?
Aim for $1,000 as an initial milestone, then build toward one month of bare living expenses. Once you hit that baseline, keep working toward three to six months depending on your job stability.
Should I pay off debt or save money first?
Build a small $1,000 emergency buffer first so a flat tire does not force you back into debt. Once that cushion exists, throw every spare dollar at high-interest credit card balances.
Is it okay to pause retirement contributions when cash is tight?
Pausing contributions temporarily during genuine financial hardship or income loss is acceptable. Just set a calendar reminder to restart them as soon as your cash flow stabilizes.
Where to Go From Here
You do not need a complicated spreadsheet or a finance degree to build a secure life. You just need to stop letting fear keep you from looking at the numbers.
Pick one small move from this list, set it up today, and let consistency do the heavy lifting.