
Stepping away from a decades-long career leaves a quiet room that can feel surprisingly heavy.
You earned this time, yet waking up without an inbox full of demands can make you wonder what comes next.
The shift from daily production to complete autonomy is not just a scheduling change; it tests how you direct your attention and protect your savings.
You do not need to figure out the next twenty years by Tuesday.
We built this guide using practical research on cognitive health and sensible spending so you can shape retirement on your own terms.
Quick Tips Before You Start
Protect Routine
Keep a consistent wake-up time to anchor your energy.
Track Fixed Costs
Know your monthly baseline before changing investments.
Move Daily
A twenty-minute morning walk sharpens cognitive focus.
Pace Yourself
Add one new commitment at a time rather than filling every day.
1. Separate Identity From Your Former Job Title
People often assume retirement brings instant clarity, while actually it triggers a quiet identity slip.
your brain loses the external markers that signaled competence for forty years, forcing you to generate internal purpose instead.
The mistake is trying to replace the old career with an equally demanding schedule right away.
Instead, take sixty days to sit in the quiet before committing to new boards or part-time consulting.
I tried to fill every blank square on my calendar during month one and burned through my patience within three weeks.
The trade-off is feeling temporarily untethered in exchange for discovering what you actually care about.
This week: write down three things you do that have nothing to do with a paycheck.
⚠️ COMMON MISTAKE
Do Not Rush Into Heavy Commitments
Saying yes to every volunteer request early on leads to quick burnout. Protect your calendar for the first few months.
2. Build a Simple Three-Bucket Cash Flow System
Money anxiety creeps in when all your cash sits in one checking account where bills and discretionary spending blur together.
It feels like every time you log in, the numbers are moving in the wrong direction and you have no idea where it all went.
We use a three-bucket structure: fixed expenses, short-term reserves, and flexible spending.
Move fixed bills to a dedicated account that funds itself two days after your pension or Social Security lands, targeting roughly fifty percent of your baseline monthly inflow to cover the non-negotiables like housing and utilities.
This removes guesswork and stops accidental spending on things that do not matter to you, leaving a clear $200 or $300 buffer in your main checking account for everyday groceries without guilt.
Three Buckets — The Numbers Behind It
3. Master a Complex Motor Skill Every Year
People assume cognitive decline is an inevitable part of getting older.
It is not a given at all, and your brain actually keeps building new neural pathways when you challenge it with physical coordination. Spending twenty minutes daily on a complex motor skill like the piano or woodworking does more for neurological health than hours of passive repetition.
Pick one new discipline this month and commit to twenty minutes every single morning before opening your email. I fumbled through my first guitar chords for weeks, but keeping the daily streak alive matters far more than sounding good right away.
Daily Focus Metrics
Small habits that preserve cognitive agility
4. Reframe Scarcity Mindsets Around Spending
I used to check my banking app three times every morning before my feet even hit the floor, bracing myself for a balance that felt entirely out of my control. That constant knot in your chest is a scarcity loop forged by decades of saving for a distant finish line you have already crossed.
The mechanism driving this is simple behavioral conditioning: when you spend forty years treating every dollar as a scarce resource required for survival, your brain treats any outgoing transaction as a direct threat. You are not being irresponsible when you hesitate to buy a $4 cup of coffee; your nervous system is reacting to fifty years of conditioning.
What I believe now is entirely different: spending money on experiences that sustain your health is part of the actual plan, not a failure of discipline or a sign of bad habits. A budget that causes you constant anxiety is fundamentally broken.
Take one concrete step this week by allocating a specific monthly fun fund of exactly $75 that you must spend entirely on yourself before the month ends. The psychological shift of forcing yourself to enjoy that money breaks the fear loop faster than any spreadsheet ever could.
🌱 GROWING TIP
Give Yourself Permission to Spend
Your savings exist to support your life, not just sit in an account. Designate a guilt-free spending category today.
5. Keep a Structured Weekly Routine
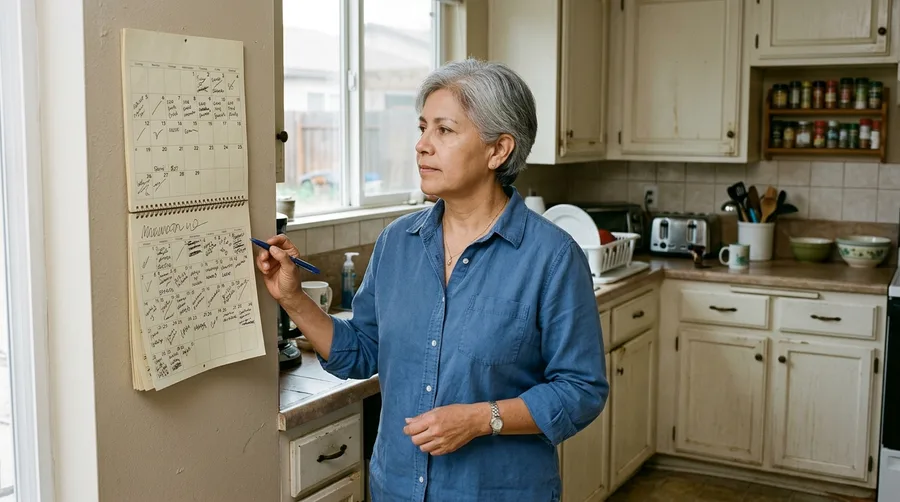
Lock in at least three anchor events every single week, such as a Tuesday morning swim class or a Thursday volunteer shift, to keep your calendar from dissolving into formless drift.
When I retired, Tuesday looked exactly like Saturday, and that lack of structure drained my motivation so badly I stopped opening my online accounts for nearly three weeks.
The mechanism here is behavioural rather than purely mathematical: routine protects your cash flow because empty days tend to invite impulsive spending and unnecessary errands.
This week, write down three fixed appointments on your fridge and treat them with the same seriousness you used to give a Monday morning meeting.
Retirement Approaches
What Works
- Automate fixed bills
- Protect health reserves
- Learn new motor skills
- Pace your commitments
What to Avoid
- Filling every calendar day
- Obsessing over tiny expenses
- Ignoring tax deadlines
- Isolating from community
6. Automate Small Monthly Giving Goals
$25 a month feels entirely too small to matter when you look at the scale of local needs.
Setting up an automatic recurring transfer removes the friction of remembering and anchors your money to what you actually care about. Consistency beats grand gestures every time because a steady, invisible contribution builds a community habit without straining your own monthly margins. I used to wait until I had extra cash to give, which meant I never gave anything at all.
Open your mobile banking app today and schedule one recurring transfer to a local cause you trust.
7. Automate Your Required Minimum Distributions
What happens if you miss the deadline for taking money out of your retirement accounts once you hit that age threshold?
The IRS slaps you with a heavy tax penalty of up to 25% on the amount you were supposed to withdraw, which is a painful way to lose money you saved yourself.
Log into your custodian portal today, set up automatic distributions for the exact required amount, and leave the rest alone so you never have to stress about missing the deadline again.
8. Scale Back Commitments Without Quitting
You do not owe your retirement to every board, committee, or favor you agreed to take on while your schedule was still crowded with a full-time career.
Stepping back often feels like quitting, but the underlying mechanism is about preserving your mental bandwidth and protecting your physical energy from chronic drain.
I kept saying yes to volunteer shifts for six months after I left my job until I realized my calendar looked just as exhausting as it did before.
Pick one regular commitment to drop completely over the next thirty days, freeing up at least two to four hours every single week.
The trade-off is feeling a brief pang of guilt when you send the email, but the reward is actually having days that belong to you.
9. Protect Your Health Buffer Against Inflation
There is a quiet panic that sits right behind your ribs when you look at a doctor bill and realize it could wipe out half your savings in a single afternoon.
You spend decades building a cushion, only to watch health expenses climb faster than standard inflation year after year.
Federal Reserve SHED data from October 2024 shows that roughly six in ten adults could cover a $400 emergency expense with cash, while thirteen percent could not cover it at all.
When those numbers meet rising medical costs, a standard emergency fund disappears almost overnight if it is not specifically protected.
The mechanism is simple cash flow vulnerability: medical bills hit without warning, and if they share space with your grocery money, every prescription refill threatens your basic survival.
The trade-off is deeply frustrating because keeping cash locked away in a health buffer means telling yourself no to travel or immediate comforts right now.
It feels restrictive to leave money sitting idle when you want to enjoy your retirement, but that separation is what keeps one bad health diagnosis from turning into a total financial collapse.
Start by building a dedicated reserve that covers at least three months of out-of-pocket premiums and routine copays, moving fifty dollars from each pension check into a high-yield savings account.
This week: open a separate health savings sub-account and make your very first transfer before the month slips away.
💡 PRO TIP
Isolate Your Medical Reserve
Keep your health buffer in a separate bank account so you are never tempted to spend it on home renovations.
10. Consult a Fiduciary Before Major Tax Moves
Fifteen thousand dollars in unexpected taxes can quietly sneak up on you when a conversion goes sideways.
A Roth conversion or pulling a lump sum out of a traditional pre-tax account is rarely a simple math problem that a generic online calculator can solve safely for your exact situation.
The mechanism here is tax brackets and statutory thresholds, which penalize sudden income spikes by pushing your entire withdrawal into a higher marginal rate than you anticipated.
I watched a neighbor trigger an accidental Medicare surcharge because they moved too much money in one calendar year without checking the local bracket boundaries first.
Before you make any major tax moves this season, schedule a meeting with a fee-only fiduciary who operates on a flat-fee or hourly model rather than a commission structure.
Bring your exact statements, your current tax return, and a clear list of what you plan to spend over the next three years so the advice is actually built around your real life.
11. Accept the Trade-Offs of Downsizing
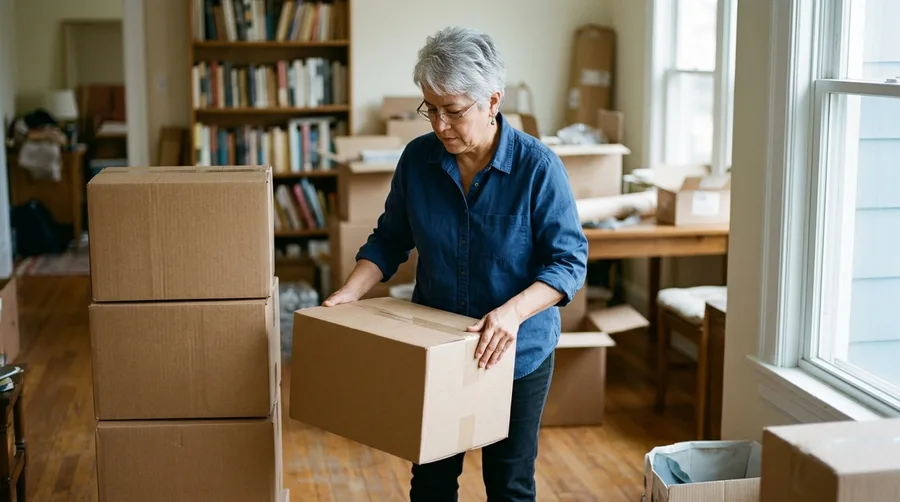
Moving to a smaller home cuts maintenance costs significantly.
It also means sorting through decades of accumulated belongings, which is emotionally exhausting and takes a real physical toll.
Do it slowly room by room, and tackle no more than one closet every weekend so you do not burn out halfway through.
The trade-off is painful upfront work in exchange for saving roughly $200 a month in utility and upkeep costs down the road.
12. Review Your Spending and Health Cadence Quarterly
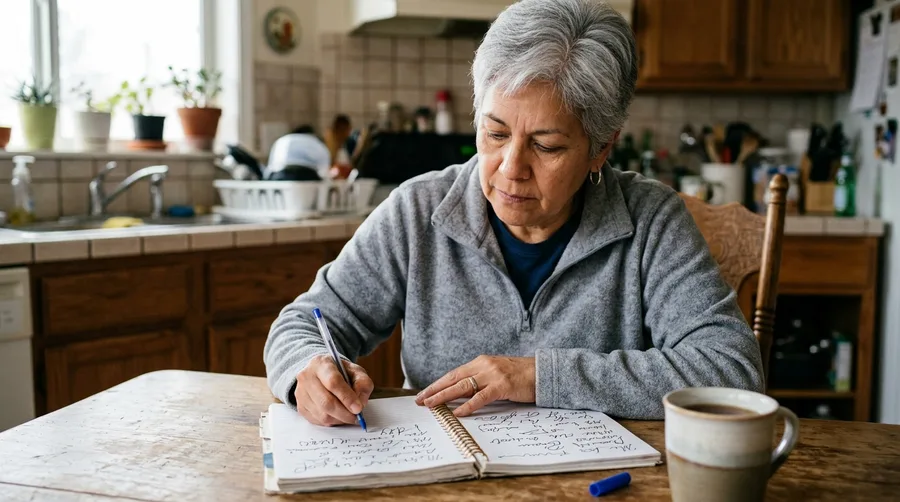
I used to wait until December to look back at my finances, and every single year it felt like opening a tax audit I never asked for.
That frantic annual panic is why I finally moved to a quarterly check-in instead.
Set a recurring calendar reminder every three months to review both your budget and your physical fitness goals at the exact same time.
your actual cash flow versus your original projections, your investment fee ratios to make sure you are not bleeding extra percentage points to management costs, and your daily step count averages to see how your health baseline is holding up.
The mechanism here is simple course correction, which operates much like a ship steering across the ocean.
Catching a $50 monthly budget leak in April prevents a full-blown financial scramble when the holidays roll around in December.
I review mine over a Saturday morning breakfast with a plain paper notebook and a blue ink pen, keeping away from complex software that just frustrates me.
The trade-off is spending an hour looking at spreadsheets when you could easily be out gardening or walking.
Do it anyway because financial clarity beats generalized background anxiety every single time.
This week: put the next review date on your wall calendar in thick marker.
13. Scale Back Complex Hobbies When Burnout Hits
You have to keep going once you start an expensive project or a complex craft because quitting means you wasted the money.
That belief is a trap that turns leisure into a second job when your energy is already running low.
The mechanism behind burnout is simple: when a hobby starts costing more mental bandwidth than it returns in joy, your brain treats it like an unpaid obligation rather than rest, spiking stress hormones and draining focus.
Give yourself permission to pause for at least 90 days and put those complicated supplies in a closet out of sight.
If you spent $400 on woodworking gear or specialty software last year, letting it sit for three months costs you nothing compared to the relief of dropping a chore you no longer enjoy.
This week, pack away just one complex project and pick up something that costs zero dollars and takes less than 20 minutes to finish.
14. Avoid Over-Optimizing Every Single Budget Category
Stop spending three hours a week clipping coupons to save four dollars on cereal.
We all fall into the trap of hyper-optimizing micro-expenses because those tiny cuts feel instantly controllable when the rest of the financial landscape feels heavy and completely out of reach. But saving twenty-four dollars a year on generic paper towels does not actually change your financial baseline.
I spent months agonizing over a fifteen-dollar grocery overage while completely ignoring an auto insurance policy that was quietly overcharging me by sixty dollars every single month. You burn out your decision energy on the microscopic stuff, which leaves nothing left for the structural expenses that actually dictate your cash flow.
Shift your attention entirely to the three heavy hitters that make up the vast majority of your fixed overhead: housing, vehicle insurance, and healthcare. Spend one afternoon calling your providers or shopping your policies instead of auditing every single receipt at the checkout counter, and keep your daily life enjoyable.
Save your willpower for the big lines.
15. Schedule One New Social Connection Weekly
How do you stop retirement from shrinking your world until it feels entirely too small?
You make connection a deliberate item on your calendar instead of waiting for it to happen by accident.
Commit to one new social touchpoint every single week, whether that means calling a former colleague you miss or walking into a local club for the first time.
Consistency builds deep community over time, turning an awkward first meeting into the foundation of a routine that keeps you grounded.
🗓️ Your First 90 Days
Weeks 1-2
Rest and establish a consistent morning wake-up time.
Weeks 3-6
Set up your three-bucket cash flow system.
Weeks 7-10
Commit to one new skill or weekly community group.
Weeks 11-12
Review your budget and make your first quarterly check-in.
Frequently Asked Questions
How much should I keep in my emergency fund after retiring?
Aim for three to six months of fixed expenses in a high-yield savings account. This covers unexpected repairs or medical costs without forcing you to sell investments during a market downturn.
Should I pay off my mortgage immediately upon retiring?
It depends on your interest rate and cash flow. If your mortgage rate is low, keeping liquid reserves often makes more sense than tying up all your cash in home equity.
Is it normal to feel restless during the first few months?
Yes. Losing a daily professional structure is a major transition. Give yourself permission to take things slow while you build new routines.
How do I balance spending on travel with preserving my principal?
Create a separate discretionary bucket funded by your safe withdrawal plan so you can spend guilt-free without touching your core retirement principal.
When should I consult a fee-only fiduciary?
Talk to a professional whenever you face major tax decisions, Roth conversions, or restructuring your income streams to ensure you avoid costly penalties.
Your First Step Forward
You do not need to overhaul your entire lifestyle by tomorrow morning.
Pick one small move from this list — open that separate savings account, schedule your quarterly review, or set your morning walk routine — and start there.
Retirement is yours to shape, one steady choice at a time.