
You have spent decades dreaming of the Friday you never have to log back in. The daily commute, the endless meetings, the alarm clock set for 6:00 AM — you want them gone.
Then you read a study suggesting that walking away from your desk at 55 instead of 65 might quietly rob you of up to nine years of healthy life. The room gets very quiet.
It feels like a bad joke after you spent your entire adult life saving every extra dollar.
You are not bad with money for wanting to rest, but the transition out of work changes your daily rhythm in ways a brokerage account cannot measure.
Quick Tips Before You Start
Define Purpose First
Money funds the exit, but daily routine keeps you alive.
Test Drive a Month
Take a four-week sabbatical before handing in your resignation.
Factor Healthcare
Private insurance before Medicare costs thousands more than you think.
Keep Social Ties
Work provides half of most adults' social contact.
1. The Identity Trap After Leaving Work
You miss the title before you miss the paycheck.
When someone asks what you do at a dinner party, the silence that follows your answer can feel heavier than any drop in your investment balance. We tie our worth directly to our productivity without ever realizing we are doing it.
That sudden loss of daily structure creates a sharp spike in cortisol that physically damages your well-being over time. Stress is not just a mental state; it is a physiological toll that hits hard when the alarm clock stops ringing.
Plan your post-work identity long before you finalize your portfolio. Aim to define at least two concrete, non-financial roles you will step into within the first 90 days after leaving your job.
This week, write down three things you care about that have nothing to do with earning money.
⚠️ COMMON MISTAKE
Mistaking Financial Readiness for Life Readiness
Having the math solved does not mean your daily routine is ready for fifty empty hours a week.
2. Automating Your Post-Work Cash Flow
Set up automatic monthly transfers from your main brokerage account to your everyday checking account right before you finally step away from work.
Treat your retirement distributions like a steady paycheck so your brain registers stability instead of constant panic. Financial anxiety drops noticeably when income arrives on the exact same Tuesday every month, averaging somewhere around $3,000 to easily cover your baseline living costs without daily guesswork.
It takes about ten minutes in your banking portal to set up today, and you never have to manually move funds again.
Retirement Readiness Audit
3. The Three-Bucket Retirement Reserve
Keep one year of cash, two years of short-term bonds, and the rest in broad index funds.
This simple structure stops you from selling stocks during a market downturn by giving you a buffer so you never have to cash out shares when the market drops twenty percent.
Copy this split immediately by checking your current reserve balances this afternoon and moving the required amounts into their designated buckets before Friday.
Leaving Early vs Staying On
Retiring at 55
- Higher risk of cognitive decline
- Extended healthcare premium costs
- Loss of workplace social network
- Depleted compounding window
Working Until 65
- Maximized social security benefit
- Employer-subsidized health insurance
- Maintained daily mental stimulation
- Higher peak lifetime earnings
4. Consulting a Fee-Only Fiduciary
I sat at my kitchen table for three hours trying to figure out if my retirement math could survive a tax law change, and honestly, I just stared at the blank spreadsheet until my eyes watered.
Your brother-in-law's well-meaning investment tips will not cover your medical bills at 72.
When tax laws shift and your withdrawal strategy gets complicated, talk to someone whose only incentive is an hourly fee.
You need a certified financial planner who does not sell insurance products on the side, meaning they make money from your success rather than from selling you a specific fund.
Expect to pay $1,500 to $3,000 for a comprehensive written plan, which feels steep until you realize a single bad tax move costs twice that in your first year out of the workforce.
Run your numbers against a professional baseline before making irreversible moves this month.
5. Calculating Your True Annual Burn Rate
Do you actually know what it costs you to live right now? Most people underestimate their monthly spending by at least 20% because they completely forget about home repairs, property taxes, and irregular medical bills.
We tend to assume our expenses will magically drop the moment we leave a job, picturing a quiet life of cheaper routines and wide-open days. If you spend $4,500 a month right now, do not plan your exit around a fantasy of suddenly living on $3,000 just because you have free time.
The math has to match reality or the portfolio fails.
Track every single dollar for three consecutive months using a simple spreadsheet or a paper notebook. It is tedious, mildly uncomfortable work, but it is the absolute only way to catch the quiet lifestyle leaks that inflate your baseline without you ever realizing it.
Multiply your actual monthly outflow by 12, then add a mandatory 15% buffer specifically for healthcare inflation and unexpected roof leaks, because ignoring these inevitable variables guarantees a painful shortfall down the road.
I avoided doing this for a long time because looking at my convenience spending felt like an indictment, but awareness is just data, not punishment.
Open your bank statement tonight.
Categorize every single line item by hand so you see where the money actually goes instead of guessing based on memory.
It takes an annoying afternoon, but it protects your future self.
Real Retirement Burn Rate
6. Overcoming the Scarcity Mindset
You saved $1.2 million over thirty years, yet every single grocery receipt still makes your stomach knot. Sound familiar? That relentless hyper-vigilance kept you safe during your decades of earning, but it quietly poisons the freedom you just bought for yourself and your partner.
The survival scoreboard is hard to throw away.
When your entire adult life is defined by accumulation, suddenly shifting into distribution triggers a deep primal panic. Your brain still thinks the wolf is at the door, even when the pantry is completely full. I spent my first retired year tracking every $4 cup of coffee as if my survival depended on it.
What I believe now is entirely different. Money is a tool for buying time, not a scorecard for survival, and hoarding it forever defeats the entire purpose of early retirement.
Give yourself absolute permission to spend the dividends without guilt. Pick one small luxury this week, like a $30 dinner out, and cover it using only your investment returns while keeping the main ledger completely closed.
7. Starting With a Tiny Expense Audit
$25 a month is all it takes to start shifting the needle on your cash flow.
Most people skip small audits because they think they need to overhaul their entire spending life in one violent weekend. That approach burns you out by Tuesday afternoon.
Instead, open your credit card app right now and look for anything you have not touched in ninety days. Cancel those subscriptions immediately.
The mechanism here is purely about friction and behavioral momentum. Once you see that canceling two forgotten $12 services takes less than three minutes, the overwhelm starts to lose its grip.
Consistency beats sweeping lifestyle overhauls every single time.
8. Establishing an Annual Portfolio Review
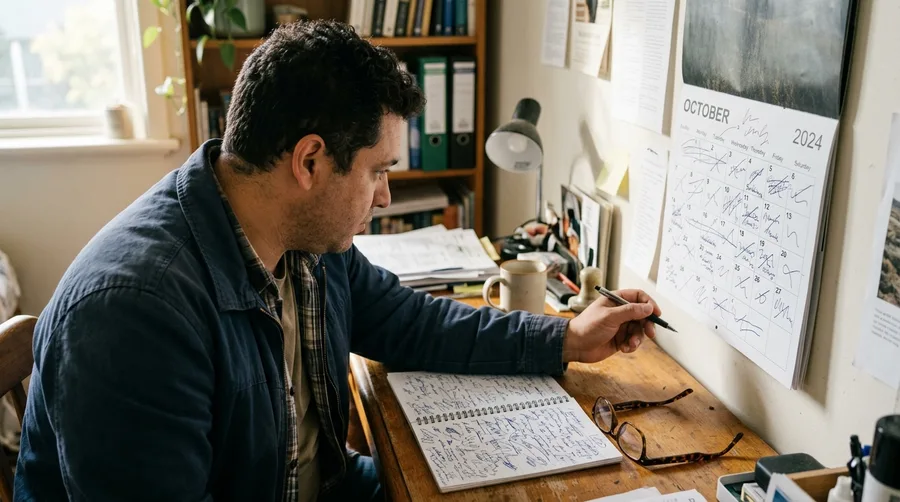
Watching your retirement account fluctuate during a market downturn feels deeply personal, as if your entire financial security is unraveling before your eyes.
Checking your balance every single day only amplifies that anxiety without giving you any useful leverage over the broader economy.
The mechanism behind an annual review relies on behavioral finance: by limiting your exposure to daily noise, you prevent emotional panic-selling that permanently locks in losses.
Set one specific weekend every October on your calendar to audit your asset allocation and actual withdrawal rate rather than obsessing over short-term market noise.
Focus exclusively on three metrics during this review: your total portfolio value, your trailing twelve-month spending, and any upcoming tax law changes that might impact your bracket.
When I first started doing this, I realized my cash drag was costing me hundreds in missed yield simply because I was too timid to rebalance my equities.
The trade-off is that looking at the full picture can feel intimidating if the market had a rough quarter, but facing the actual data once a year beats guessing in the dark.
Open your calendar application right now and schedule a recurring two-hour block for mid-October before you close this tab.
Annual Review Protocol — At a Glance
📅 Timing
Every October
📊 Metrics
3 key numbers
⏱️ Duration
45 minutes max
Golden Rule
Never adjust your long-term strategy during a single bad market week.
9. Downsizing Before the Market Forces It
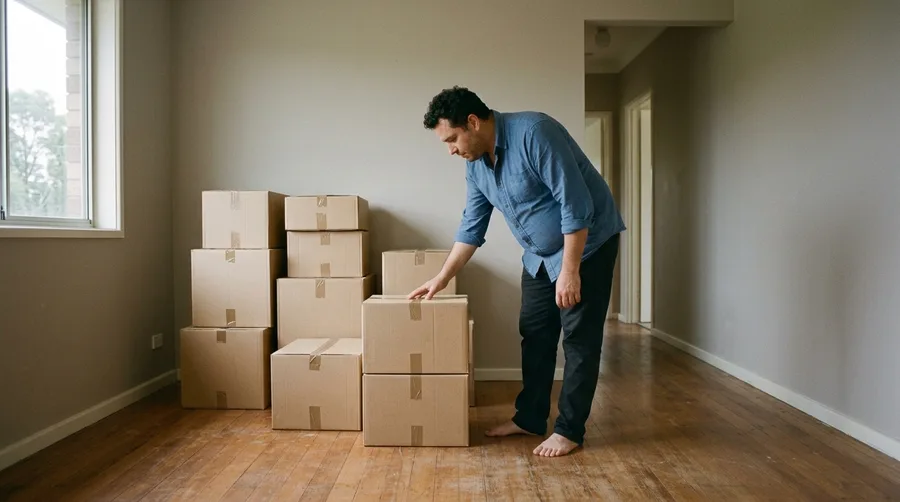
I sold our family home three years too early rather than five years too late, and it saved us from a slow financial bleed.
Dropping square footage cut our property tax and maintenance bills by $11,000 a year, which immediately freed up cash for our retirement baseline.
Do it while you still have the energy to pack boxes and clear out decades of clutter on your own terms.
This week, look at your current housing costs and calculate what a smaller footprint would save you annually.
10. Accepting the Cost of Free Time
You picture early retirement as a quiet morning with coffee and endless empty calendar squares, but nobody warns you how expensive having nothing to do actually gets.
The trade-off is real: more free time directly increases your operational budget because idling around the house always turns into project spending, hobbies, and travel.
Factor an extra $500 a month into your baseline projections for boredom projects so you are never caught off guard.
This week: add that specific buffer line to your retirement spreadsheet before you lock in your final departure date.
11. Scaling Back Without Quitting Entirely
Leaving a forty-hour workweek can feel like standing at the edge of a cliff, especially when you worry that your savings will not quite stretch the distance.
You do not have to make that absolute leap right away. Stepping down gradually through part-time consulting or seasonal project work bridges the psychological gap while keeping your investments untouched during market dips.
Working just ten hours a week brings in roughly $1,500 a month in flexible income, which buys you both breathing room and social connection.
Give yourself explicit permission to slow down rather than stop cold. This week, list two former colleagues you can contact about flexible or project-based work.
💡 PRO TIP
The Bridge Career Strategy
Part-time consulting covers your groceries and lets your core investments compound for five more years.
12. Beating the Inflation and Tax Clock
Why wait until tax season to look at what you are handing over to the government?
Waiting until next year to optimize your tax brackets costs you thousands in unnecessary withholdings.
Look at Roth conversions now while your income is lower, shifting money into tax-free growth before December 31 adds thousands back to your long-term buffer.
I put this off for two years and watched $1,500 slip away in avoidable bracket drag before I finally scheduled a half-hour call with a CPA to map it out.
Act this month by checking your current taxable income against the bracket thresholds and moving one small chunk before the year closes.
13. Avoiding Social Isolation Traps
Schedule your social life with the exact same discipline you used for work meetings before you hand in your badge.
Most people completely underestimate how much of their daily connection is built entirely around office small talk, hallway hellos, and Friday lunch groups that were never really about the food.
When you leave early, your phone suddenly stops ringing by week three, and the sudden quiet in the house can feel heavier than any spreadsheet.
Health research from institutions like Brigham Young University shows that chronic loneliness carries the exact same mortality risk as smoking 15 cigarettes a day.
That is not a wellness platitude; it is a biological cost that no amount of compound interest in a brokerage account can actually offset.
Build a real community outside your employer well before your final day by joining a weekly pottery class, volunteering at a local food bank, or starting a neighborhood walking group.
Money in the bank will never replace a simple Tuesday coffee date with a good friend who knows your story.
This week: pick one recurring local activity and put it on your calendar as a non-negotiable appointment.
Retirement Realities
14. Automating Your Monthly Tithe to Savings
10 percent of every single freelance check needs to move into your reserve account automatically before you even look at it.
Relying on sheer willpower for variable income fails because the temptation to absorb extra cash into lifestyle spending is too fast and too quiet.
Log into your bank app tonight and set up the automated split so the money disappears before you can miss it.
15. The Three-Bucket Cash Flow Blueprint
I spent my first three years out of a corporate job watching my annual property tax payment accidentally get swallowed by a weekend road trip because every dollar sat in one messy, unified checking account.
That chaotic blur finally ended the month I split my cash flow into three dedicated accounts with entirely separate jobs: fixed survival costs for rent and utilities, discretionary fun for guilt-free spending, and long-term reserves that stay untouched.
When money is segregated this way, the mechanism removes daily financial friction and you never accidentally spend your $1,200 property tax money on a casual dinner out or a sudden impulse buy.
Setting this up takes about twenty minutes inside your mobile app, though the real adjustment is behavioral, requiring you to let the buckets do their jobs without constantly panicking and moving cash back and forth when things get tight.
Copy this three-bucket split into your bank app today and watch how fast your daily financial anxiety drops when your core bills are quietly handled in the background.
Frequently Asked Questions
Is it actually dangerous to retire early?
Research suggests that retiring before traditional age without a clear daily purpose or social network correlates with higher health risks and cognitive decline. Staying mentally and socially active is the key variable.
How much should I have in cash before quitting work?
Aim for one to two years of living expenses kept in high-yield savings or short-term instruments. This prevents you from selling stocks during a market downturn.
Should I pay off my mortgage before leaving my job?
Eliminating a major fixed monthly payment drastically lowers your required withdrawal rate, providing immense psychological relief during your first years out of the workforce.
What is the biggest hidden cost of early retirement?
Healthcare premiums before Medicare eligibility at age 65 frequently shock retirees who budgeted only for basic living expenses.
How do I deal with the loss of routine?
Build a structured weekly calendar before you quit, including volunteering, exercise classes, and social commitments, so your days retain a healthy rhythm.
Where to Go From Here
You do not have to solve your entire retirement strategy by Friday afternoon.
Pick one actionable step from this list — track your actual spending for thirty days or book a conversation with a fiduciary — and start there. Your health, your wealth, and your future days belong to you.