
The cake is gone, the cards are in the recycling bin, and the office phone finally stopped ringing.
Nobody warns you how quiet the house feels on a Tuesday morning when the rest of the world is stuck in traffic.
You spent decades planning the target savings number, but you spent very little time planning the actual mechanics of living on a fixed income.
It is normal to feel a sudden wave of financial panic even when your accounts look healthy on paper. Here is the unvarnished look at what changes next, and how to build a routine that actually holds up.
Quick Tips Before You Start
Automate Basics
Keep bills on autopay so you never miss a due date.
Audit Spending
Track every dollar for thirty days to see where cash actually goes.
Review Health
Factor rising medical costs into your annual baseline.
Update Papers
Review your will and beneficiaries every single year.
1. The First Month Quiet Shock
People assume walking away from a career instantly cures your financial stress, but the silence is actually the loudest part.
When I stepped away from my last full-time job, I assumed the hard part was completely behind me. It was not. The sudden drop in daily routine creates a strange psychological itch that people try to scratch by spending money, and I accidentally burned through $400 on random online orders in my first three weeks just to feel productive.
Expect this quiet shock so it does not catch you off guard. This week, pick one free physical project or daily walk to anchor your mornings before the urge to browse sets in.
💡 PRO TIP
Anticipate The Transition Lag
Give yourself a full ninety-day grace period before making any major financial pivots or selling off assets.
2. Permission To Scale Down Expenses
It feels terrifying to admit that your income has dropped and your old spending habits no longer fit the reality of your bank statement.
Society trains us to treat lifestyle creep as a permanent milestone, as if letting go of a club or a vehicle upgrade means you are somehow losing ground.
You do not need to maintain the exact lifestyle you had during your peak earning years just to prove you are okay. Retirement gives you a completely valid, unarguable excuse to strip away every single expense that does not directly add joy to your days. If you hate golfing, stop paying for the club membership immediately. If you prefer cooking at home, drop the dining-out line item from $400 a month down to zero without a second thought.
Scaling down is never a failure.
It is a strategic choice that protects your principal and gives you actual breathing room when inflation ticks upward. When your fixed costs drop, your baseline anxiety drops right along with them.
It feels weird at first to tell friends you are cutting back, but nobody is actually tracking your line items as closely as your own brain tells you they are.
Start this week by cutting your subscription stack back by at least half. Cancel the streaming services you have not opened in three months and redirect that cash straight into your safety cushion.
Scaling Down — Decision Rules
3. The Hidden Tax Trap On Withdrawals
There is a quiet panic that sets in when you pull money from a traditional retirement account for the first time and realize the tax man is waiting in the wings.
Every single dollar you withdraw from a pre-tax account counts as ordinary income, meaning it stacks right on top of whatever else you are bringing in that year.
People get completely blindsided when these withdrawals push them into a higher tax bracket than they expected, leaving them with a surprise bill that can wipe out months of careful planning.
The window to fix this is before you actually need the cash, not next April when the penalty notice arrives in the mail.
Plan your withdrawals across multiple buckets including taxable, tax-deferred, and tax-free accounts to keep your annual liability under control, and talk to a fee-only fiduciary before making large lump-sum withdrawals to avoid a massive shock.
Retirement Tax Myths
4. Overcoming Scarcity Mindset Blocks
About 60 percent of adults worry constantly about outliving their savings, according to Federal Reserve SHED data from 2024.
That fear turns every minor home repair into a real catastrophe.
When a $200 plumbing fix feels like the beginning of total ruin, you are fighting a scarcity mindset that tells you every dollar leaving your hand is gone forever.
Shift your perspective from hoarding cash to managing cash flow efficiently by mapping out predictable monthly income sources like pensions and Social Security so the fear starts to lose its grip.
This week, write down your guaranteed baseline income on a single piece of paper and compare it directly against your non-negotiable living costs to see where the actual safety net lies.
⚠️ COMMON MISTAKE
Hoarding Out Of Pure Fear
Refusing to spend any money on travel or hobbies out of anxiety defeats the entire purpose of saving for decades.
5. Automate Your Monthly Paycheck
Set up an automatic monthly transfer from your investment accounts to your checking account on the first of the month.
Taking human emotion out of the withdrawal process stops you from second-guessing every market dip, because selling during a bad week destroys your returns far more than a temporary market correction ever will.
Set it up once in your bank portal for $2,000 or whatever your monthly baseline requires, and leave the rest alone for at least six months.
Typical Monthly Fixed Baseline
6. When To Consult A Fee-Only Fiduciary
I spent three weeks trying to map out a complex Roth conversion ladder on a messy spreadsheet before I finally realized I was completely out of my depth.
Complex portfolios and estate planning require professional eyes because a single miscalculation can trigger thousands of dollars in unnecessary taxes over a thirty-year horizon.
Find a certified financial planner who operates strictly on a fee-only fiduciary model rather than earning hidden commissions on the specific insurance products or mutual funds they sell you.
The fiduciary standard legally requires them to put your financial interests above their own compensation, which changes the entire nature of the advice you receive.
This week: look up local fee-only planners in your area, set aside your current investment statements, and book an introductory consultation to run your specific numbers against a sustainable withdrawal rate.
💡 PRO TIP
Check Fiduciary Status
Always verify that your advisor is legally bound to put your financial interests above their own commissions.
7. The Three Bucket Cash Flow System
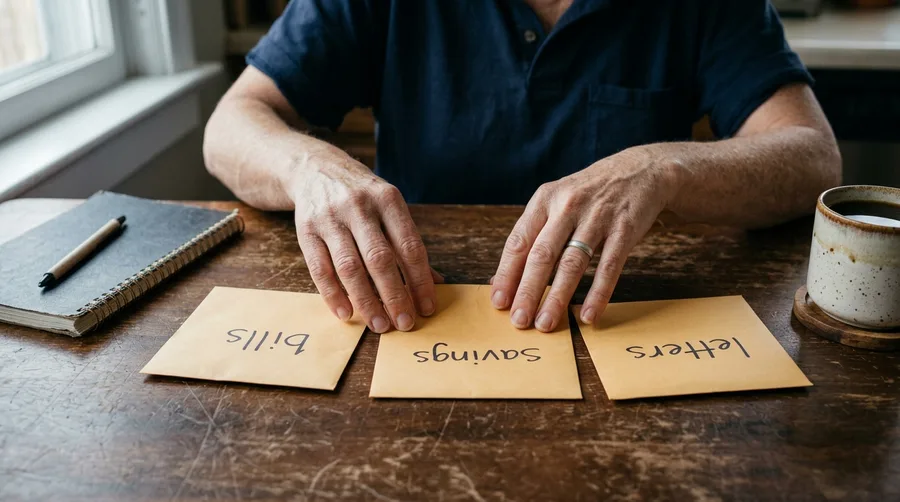
Organize your retirement cash flow into three distinct buckets today so market drops never catch you off guard or ruin your sleep.
Bucket one holds one full year of living expenses in a high-yield cash account to cover immediate bills without ever touching your long-term investments. When the grocery delivery arrives or the utility bill lands, the money is right there in a safe place, completely shielded from stock market volatility.
This layer stops panic selling cold.
Bucket two holds conservative income-producing assets like short-term bonds or stable instruments meant for years two through five of your timeline. This middle tier bridges the gap between your immediate cash and your long-term growth, shielding you from having to liquidate holdings during a terrible market quarter.
Bucket three holds growth-oriented index funds that track the broader market for the long haul, giving your capital room to compound over decades. If the market drops 20 percent, you simply draw your living expenses from bucket one and let bucket three recover in peace without taking a permanent loss.
I used to think a single giant pool of savings was simpler, but watching a downturn eat into a live checking balance teaches you otherwise very quickly. The psychological friction of seeing numbers drop is real, and structural separation is the only reliable fix for human anxiety.
Setting this up takes a quiet afternoon across your accounts, but the structural peace of mind pays dividends on the very first rough trading day of the year.
Open your first separate account today.
8. Healthcare Costs Will Outpace Inflation
Will your standard retirement budget actually survive a routine trip to the specialist? Most people plan for groceries and travel while completely forgetting that medical expenses tend to outpace regular inflation by a wide margin as we age.
healthcare inflation historically runs faster than general inflation, meaning a prescription or co-pay that costs $50 today will quietly take a much larger bite out of a fixed income ten years from now.
Build a dedicated health buffer into your annual spending plan right now by earmarking an extra $150 to $200 a month strictly for out-of-pocket medical costs. Set up a separate savings category this week so an unexpected dental procedure or specialist visit never derails your grocery money.
9. The Psychological Cost Of Idle Time
Keep a project in mind before you hand in your notice. Walking away from a forty-hour workweek leaves a massive vacuum that boredom fills faster than you think.
The hidden danger here is expensive lifestyle creep disguised as entertainment. When you suddenly have an extra forty hours a week and nothing to anchor your mornings, you start browsing online stores or taking up costly hobbies just to pass the hours, burning through savings you meant to keep.
Hobbies cost money, so plan for them honestly. Allocate $100 a month specifically for project supplies so your free time has a structure and a boundary.
10. Annual Portfolio Review Cadence
You do not need to look at your retirement accounts every single day, and frankly, doing so will only drive you crazy.
Checking the balance constantly turns normal market dips into a daily emotional emergency, which is why most people burn out on managing their own money.
Instead, pick one specific month, like every January, to sit down with your statements for exactly forty-five minutes.
During that yearly check, look only at three metrics: your total withdrawal rate to ensure you are not pulling out more than three to four percent annually, the health of your cash buffer to make sure you have enough liquid money for unexpected expenses, and whether your estate documents still name the right people.
That calendar cadence keeps small portfolio drifts from turning into massive imbalances over time without requiring you to obsess over every single headline.
11. Avoid Emotional Portfolio Selling
I watched my portfolio drop nearly $14,000 during a rough market correction a few years back and panicked so hard I almost sold everything just to make the red numbers stop flashing.
The common mistake is treating a paper loss like actual money gone forever, which leads people to sell during a downturn and permanently lock in a 20% or 30% drop instead of riding it out.
The mechanism is simple: stocks recover over time, but selling low guarantees you miss the rebound, and history shows markets eventually bounce back for those who stay invested.
This week, delete the financial news app from your phone and let your designated cash buckets handle the short-term noise so you do not touch your investments.
12. Start Small With Your New Routine
Can you actually change your financial habits when you are decades into a routine?
Yes, and you do not need to overhaul your entire life to make it stick.
Most people get stuck because they think every financial move requires a massive, painful sacrifice to count.
The truth is that consistency beats perfection every single time you try to build a new habit.
Even $25 a month shifted toward a personal passion fund or an emergency buffer builds a powerful psychological habit over time.
The mechanism here is purely behavioral: when you start small, your brain stops treating the action as a threat, which means you actually keep doing it instead of quitting by the second month.
You do not need a million-dollar spreadsheet to start feeling secure today.
Pick one small adjustment from this list and put it into motion this week.
The first step is always the hardest part, but once the system runs on autopilot, the anxiety fades into the background.
You have built a lifetime of experience, so now it is time to build a financial routine that respects it.
Take a deep breath, close this tab, and go set up your first automatic transfer.
Frequently Asked Questions
Is it too late to start investing for retirement at 50?
It is never too late to start building cushion. Maximize your employer catch-up contributions and automate small monthly transfers to bridge the gap.
How much cash should I keep in an emergency fund?
Aim for three to six months of basic living expenses, or a full year if you rely on variable income streams.
Should I pay off my mortgage before stopping work?
It depends on your interest rate and psychological comfort. If your rate is low, keeping liquid cash might provide better peace of mind.
How do I calculate a safe withdrawal rate?
Many financial planners use the four percent rule as a baseline guideline, but your personal number depends on your health, age, and portfolio mix.
Your Next Step This Week
Take one concrete action from this list before Friday afternoon.
You do not need to overhaul your entire financial life overnight. Small, consistent steps build the security you deserve.