
You sit at the kitchen table with a spreadsheet, staring at numbers that refuse to add up the way the financial planners promised they would.
It is easy to feel like you missed a memo when post-work expenses outpace your fixed income.
Most people assume they failed because they bought too many lattes, but real retirement budgets break down over predictable structural traps.
After digging through dozens of household ledgers, I found the exact places money leaks away.
You do not need to fix everything at once, but you do need to know where the actual damage happens.
Quick Tips Before You Start
Audit Fixed Costs
Pull the last three months of bank statements to find hidden recurring expenses.
Cut Subscription Creep
Cancel any streaming or software service you have not used in thirty days.
Weigh Healthcare
Assume out-of-pocket medical costs will rise by at least five percent annually.
Inspect the House
Set aside a distinct maintenance fund before a roof leak forces your hand.
1. Consulting a Fee-Only Fiduciary
I spent three weeks trying to map out my own tax distribution strategy before I finally realized I was completely out of my depth.
When your portfolio crosses $100,000 or tax laws shift, guessing stops being a viable strategy and starts becoming an expensive hobby.
Find a fiduciary who charges a flat hourly rate of $200 to $300 rather than taking a percentage of assets under management.
This protects your returns from quietly bleeding out through hidden fees, and gives you an objective partner whose only incentive is your actual stability.
💡 Tip: Verify fiduciary status directly through the NAPFA database before booking an initial call.
Audit Essentials
2. Automating Your Monthly Transfers
Why does saving money feel like an endless uphill battle when you rely entirely on willpower alone?
The honest truth is that expecting yourself to manually transfer cash every single payday is a setup for frustration.
If the money sits right there in your primary checking account, everyday life has a funny way of absorbing it before you even realize it is gone.
A casual dinner out, an unexpected grocery run, or a random online purchase will quietly eat away at the exact funds you intended to put toward your future.
you bypass willpower entirely by building a system.
Set up an automatic transfer for $250 straight into a separate high-yield savings account the exact morning your paycheck lands.
When the transfer happens before you can look at the balance, you naturally learn to adjust and live on what remains instead of trying to save whatever happens to be left over at the end of the month.
This single habit transforms sporadic, stressful saving into an invisible and reliable engine that quietly works in the background.
Open your banking app this morning, schedule the recurring transfer, and let the system run itself so you never have to think about it again.
💡 PRO TIP
Payday Automation Rule
Schedule your savings transfers for the exact morning your paycheck clears to prevent accidental spending.
3. Overcoming Fixed Income Scarcity
Every single purchase feels like a direct threat to your long-term survival.
Scarcity whispers that if you spend $40 today, you are actively failing tomorrow.
The mechanism behind this trap is insidious, as hoarding cash in a basic account means inflation slowly chews away at your purchasing power by roughly 2 to 3 percent every single year.
You are losing money simply by refusing to let it move.
The reframe is quite simple: your cash is a tool for security, not a scorecard of your personal worth.
Shift your focus entirely away from painful restriction and toward deliberate allocation.
Set aside 15 minutes this afternoon to look at your actual numbers instead of running from them.
Mindset Shifts
4. Accepting the Healthcare Trade-Off
It is completely normal to feel a wave of frustration when you open your statement and look at how much medical premiums cost every single month.
Protecting your nest egg means accepting the unglamorous reality that healthcare will consume a much larger slice of your fixed monthly income, often running between $400 and $900 for a standard individual plan before deductibles ever kick in.
The trade-off is deeply annoying: you are handing over hard-earned cash month after month for coverage you genuinely hope you will never have to touch.
Skipping health coverage entirely just to free up a bit of quick cash right now feels like a clever shortcut, but it is a devastating financial gamble that can instantly wipe out years of disciplined savings with a single unexpected accident or hospital stay, trading short-term relief for long-term disaster.
This week, pull your actual medical spending from the last six months, calculate your real baseline costs, and lock that number into your budget as a non-negotiable line item that never gets cut.
The Safe Route
- Max out supplemental plans
- Keep dedicated health savings
- Review deductibles annually
The Risky Gamble
- Drop coverage to save cash
- Ignore rising prescription costs
- Skip preventative checkups
5. Capitalizing on Compounding Windows
Waiting another year to fix your budget costs you thousands in lost compounding returns.
Compound interest means your money earns a return, and then that return earns its own return, creating a snowball effect over time. When you delay starting by even twelve months, you miss out on a full year of growth on the earliest dollars you put away. It is not about timing the market perfectly; it is simply about giving your money more years to work in the background.
Open that account this week and set up your initial transfer, even if it is only $50 to get the door open.
Compounding Mechanics — The Fine Print
🛡️ Fee Waiver Threshold
$500 minimum or automatic transfer
📊 Assumed Model Rate
7% historical annual average
🛑 Skip This If
Carrying debt above 20% APR
The Math Check
Projections assume steady growth, but actual market returns vary year by year.
6. Automating Bill Pay Cycles
Over four hundred dollars a year vanishes in late fees and missed payment penalties for the average household simply because due dates arrive before notice does.
Willpower fails when you have to manually log in and pay twelve different utilities every single month.
The mechanism here is removing the decision entirely from your plate.
Put every recurring bill on autopay linked to a dedicated rewards credit card that you pay off in full every single month.
This protects your credit score, prevents accidental oversights, and frees up crucial mental bandwidth.
You are not doing this to become some rigid financial machine, but rather to save your energy for decisions that actually matter instead of calendar alerts.
Set up the system once and let the bank handle the routine while you leave the account alone.
Take twenty minutes today to link your primary accounts and reclaim your peace of mind.
⚠️ COMMON MISTAKE
Autopay Trap to Avoid
Never link autopay to an account with a fluctuating balance to avoid painful overdraft fees.
7. The Three-Bucket Cash Flow Split
Divide your post-tax income into three distinct buckets the morning your paycheck hits: fixed bills, debt minimums, and flexible spending.
Without a physical boundary between your rent money and your dinner money, discretionary spending quietly eats your balance. You glance at your checking account, see $2,100, and feel safe spending $120 on eating out. But that total includes next week's electric bill and your car payment, turning an innocent Friday night into a late-month panic.
The fix is a simple allocation system.
Cap your fixed bills and basic survival needs at 50 percent of your income, reserve 30 percent for flexible lifestyle choices, and send 20 percent straight to savings or extra debt paydown. When you split the cash upfront, the guesswork vanishes from your weekly grocery run because you are only looking at the money meant for that week.
I ran into this trap for years until I opened a second checking account just for fixed bills. The trade-off is setting up a few automated transfers, but moving that money first turns cash flow from a guessing game into a repeatable routine.
Bucket Setup Checklist
-
Calculate exact monthly fixed bills Include rent, utilities, and insurance.
-
List all minimum debt obligations Never miss a scheduled payment.
-
Establish a weekly flexible cash limit Withdraw physical cash for groceries.
8. Fixing the Housing Maintenance Blindspot
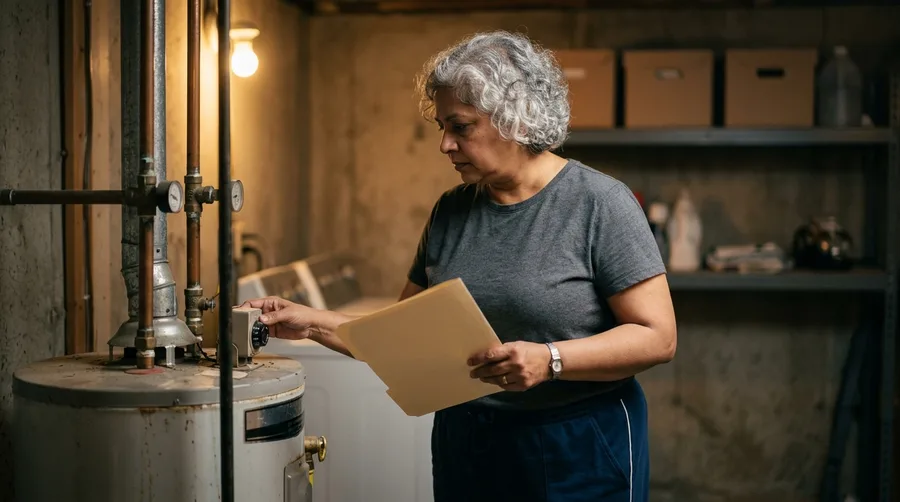
People assume homeownership costs stop once the mortgage is paid off, as if the physical structure stops aging the moment the bank hands over the deed.
Roofs leak and HVAC units fail without warning, turning what should be a secure roof over your head into an unexpected $7,000 emergency bill because the maintenance line was left blank.
Set aside one percent of your home value annually into a separate repair fund to cushion these inevitable shocks without reaching for high-interest credit cards.
Open a dedicated savings sub-account this afternoon and move your first monthly maintenance deposit into it.
9. Starting With the Twenty-Five Dollar Floor
Start with a tiny twenty-five dollar automatic monthly transfer into your retirement account.
Waiting until you can magically save hundreds of dollars a month means you never actually start at all.
The mechanism behind this is simple behavioral friction. When the transfer happens without your active permission each payday, saving stops being a daily choice you have to fight yourself to make and turns into background infrastructure.
Even small contributions build the psychological habit of paying yourself first instead of waiting for whatever is left over after expenses.
Scale the amount up by ten dollars every six months as your comfort grows, and watch how quickly the baseline shifts.
Frequently Asked Questions
Is it too late to start investing at 50?
It is never too late to begin building a cushion. While you missed early compounding, higher catch-up contribution limits and intentional spending adjustments can still drastically improve your financial security.
How much should I keep in my emergency fund?
Aim for three to six months of essential living expenses. If your income fluctuates or your health is unpredictable, lean closer to the six-month mark and hold it in a separate high-yield account.
Should I pay off debt or save for retirement first?
Secure any employer retirement match first, then attack high-interest debt aggressively. Leaving free match money on the table while paying off low-interest debt slows down your overall progress.
Is it okay to pause my savings during tight months?
Yes, pausing temporarily is completely fine when life happens. The key is setting a reminder to restart your automatic transfers as soon as the emergency passes so you do not break the habit.
How do I calculate realistic healthcare costs?
Look at your current out-of-pocket premiums, deductibles, and regular prescriptions, then inflate that number by five percent annually. Medical expenses tend to rise faster than standard inflation.
Where to Go From Here
You do not need to overhaul your entire financial life by tomorrow afternoon.
Pick one move from this list, set up the automation, and let consistency do the heavy lifting.