
Most financial advice sounds like it was written by a spreadsheet.
You stare at the projections, the assumed annual returns, and the terrifying target numbers, and you feel entirely unequipped for the math.
The best guidance I ever received came from people who were already ten years past the finish line, and not a single one of them talked about compound interest first.
They talked about habits, health, and the quiet shifts in perspective that happen when the paycheck finally stops.
You do not need a finance degree to get this right, and you certainly do not need perfection.
Quick Tips Before You Start
Keep It Simple
Ignore daily market swings and focus on your monthly savings rate.
Know Your Baseline
Track three months of actual spending before building any long-term projections.
Automate Early
Set up automatic transfers on payday so you never have to make a choice.
1. Ignoring the Perfect Market Timing Myth
People love to talk about buying the absolute lowest dip as if anyone has a crystal ball. Waiting for the ideal moment to invest costs you more in missed time than a minor market correction ever will.
The honest trade-off here is discomfort: you will almost certainly buy something on a Tuesday and watch it drop 3 percent by Friday, feeling foolish. The math favors consistency over cleverness every single time because staying on the sidelines waiting for perfection guarantees you miss the recovery.
Start where you are with what you have, even if it is just $50 this month.
⚠️ COMMON MISTAKE
Waiting for the Perfect Market Drop
Trying to time your entry into the market usually results in sitting on cash for years while inflation eats your purchasing power.
2. Automating Your Monthly Transfers
Set the automatic transfer for the exact morning your paycheck lands, rather than waiting until the last day of the month.
End-of-month saving means you are trying to save whatever survived your spending, and what survives is usually nothing at all.
Payday saving flips that script completely because the transfer amount is decided before the month gets a single vote.
You are moving the exact same $50 or $200, but you get a completely different success rate simply by changing the calendar trigger.
This is a timing fix rather than a discipline problem, and it takes about four minutes in your banking app to set up and leave alone forever.
Automation Impact
Why automatic transfers beat willpower
3. Learning From My Own Budget Failures
I felt like a constant failure for three years straight because of a plastic green binder.
Every Sunday night, I tried to force our household into a strict $400 monthly grocery budget, treating our eating habits like a rigid calculus problem instead of a normal human necessity. By the twentieth of every month, the fridge was bare, the budget was blown, and the shame cycle triggered a flurry of takeout orders that cost double what I tried to save.
The fix was counterintuitive: I raised the food line to $600 a month to give us actual breathing room. Giving myself a $200 buffer ended the guilt-driven spending spikes completely, which unexpectedly boosted our overall monthly savings rate by nearly 12%. Today, review your most frustrating budget category and add a 15% reality cushion so your plan actually survives the week.
4. Embracing the Power of Scaling Back
About 70 percent of households feel like they are falling behind on long-term goals.
That quiet panic usually hits right when an unexpected dental bill or a $400 car repair lands on top of a month that was already stretched too thin.
You do not have to fix everything on your financial checklist by Friday afternoon.
Scaling back your targets when life gets expensive is not a failure of character.
It is a deliberate structural shift to keep your core routine alive when your cash flow takes a hit.
Pausing a retirement contribution for two months to handle a sudden home repair is not quitting.
It is simply adjusting your pace so you can finish the race without burning through your sanity.
Consistency survives flexibility; it shatters under rigid perfectionism every single time.
When you try to maintain an aggressive $500 monthly transfer during a month where your grocery costs spiked by $150, you usually end up raiding the whole account in frustration.
Lowering that transfer down to $50 temporarily keeps the muscle memory of saving intact without breaking your month.
The mechanism here is purely behavioral: keeping the habit alive matters more than the exact dollar amount during a lean season.
I spent years beating myself up for dropping my automatic transfers during a brutal three-month stretch of medical bills, thinking I had ruined my trajectory.
All I actually did was create an unnecessary cycle of guilt that made returning to normal savings much harder than it needed to be.
The permission slip is built right into a sustainable system.
Give yourself explicit permission to dial your numbers down by 50 percent or even 80 percent for sixty days when life gets heavy.
This week, look at your automatic transfers and decide which single number you can safely cut in half until your next pay raise, keeping the channel open without choking your daily cash flow.
Household Savings Reality
Federal Reserve SHED, 2024
5. Recognizing the Urgency of Starting Now
Is it actually too late to start building serious momentum?
That is the question everyone asks when they hit forty and look at a nearly empty account, staring at bank balances that feel stubbornly small while everyone else on the internet seems to have everything figured out.
Compounding rewards starting this month over next year, but it also rewards starting today over five years from now because interest needs time to actually do the heavy lifting for you.
every dollar invested today earns returns that then generate their own returns, whereas waiting five years means giving up the exact window where growth accelerates the fastest.
Every single dollar you put away today buys you options tomorrow.
Take a breath, stop regretting the years you spent figuring things out, and open that retirement account this week to move even $50 into a low-cost index fund that tracks the whole market.
6. Building a Three-Bucket Cash Flow System
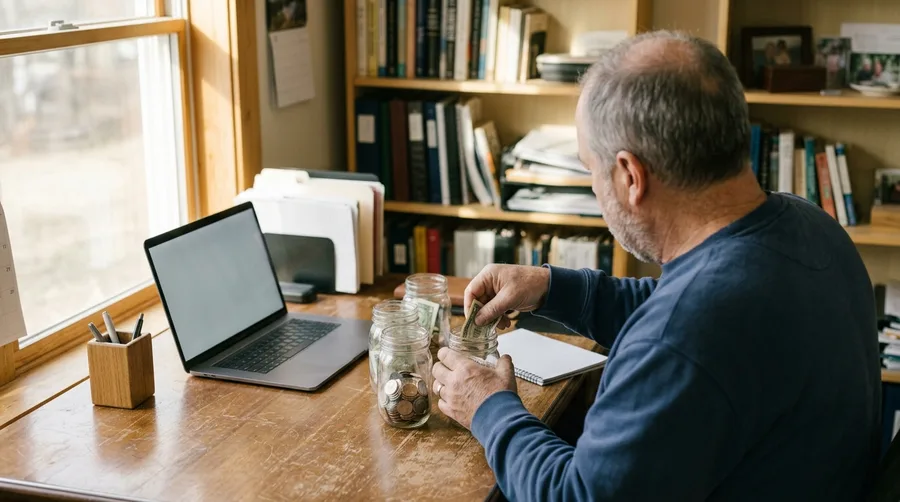
You do not need a complicated spreadsheet with forty different categories to get your spending under control, and it is completely normal if the standard methods have failed you before.
We use a straightforward three-bucket system divided into fixed bills, debt minimums, and flexible spending, with separate bank accounts to keep the mental noise completely out of daily choices.
Set up your automated transfers on payday so that $1,500 for fixed costs and $400 for debt minimums move instantly before you ever see them, leaving the rest safely behind for groceries and life.
The Three-Bucket System
7. Avoiding Common Lifestyle Inflation Traps
A common pitfall is upgrading your car or apartment the second you get a modest raise.
Most of us fall into this trap without even noticing it happen.
income goes up, baseline expenses match it immediately, and your savings rate stays flat.
You end up working harder and earning more, yet somehow your bank account looks exactly the same at the end of every month.
The fix is routing half of every raise directly into your retirement account before it ever hits your checking account balance.
If you get a raise that adds $200 to your monthly paycheck, set an automatic transfer for $100 to move on the exact same day.
You cannot spend money you never saw.
This simple barrier protects your future self from your present impulses without requiring constant daily discipline.
It feels annoying for two paychecks, and then you completely forget it is happening.
This week: look at your last pay stub, calculate half of your most recent raise, and set up the automated transfer right now.
Lifestyle Inflation vs. Conscious Saving
The Trap
- Upgrading cars immediately
- Expanding apartment size
- Absorbing raises into spending
The Fix
- Routing half of raises to savings
- Keeping fixed costs stable
- Automating transfers on payday
8. Knowing When to Consult a Professional
I sat at my kitchen table for three straight hours trying to figure out whether to clear my remaining car loan or push that cash into retirement, and honestly, I was just spinning my wheels.
Sometimes your specific tax bracket and debt mix need a trained eye instead of another online calculator.
Run your numbers against a fee-only fiduciary if you feel stuck between conflicting priorities, because a single consultation can save you thousands in avoidable penalties.
9. Reviewing Your Portfolio Once a Year
Set a calendar reminder for your birthday or tax season to check your asset allocation once a year.
Most people do far too much tinkering with their investments, checking balances weekly and reacting to every minor market dip, which usually ends up costing them in fees and missed gains.
When you finally open the dashboard, you only need to look at three specific things: your total annual savings rate, the expense ratios or account fees you are paying, and whether your risk tolerance matches your current age and timeline.
I used to log in every single month convinced I needed to optimize something, until I realized my constant adjusting was just anxiety disguised as strategy and my portfolio actually grew better the months I ignored it.
Leave the rest of your investments entirely alone so you do not tinker yourself into lower returns, and close the tab as soon as you have checked those three numbers.
10. Starting Small With Just Twenty-Five Dollars
People think investing requires thousands of dollars upfront to even bother opening an account.
That belief keeps half of us frozen on the sidelines for years because $5,000 feels completely out of reach when rent just went up again.
The mechanism that actually builds a balance over time is simple repetition, not a massive opening deposit.
Even $25 a month, moved automatically into a low-cost index fund that tracks the whole market, does more than $0 a month you keep meaning to invest once things settle down.
Consistency beats lump-sum perfection every single time.
Build the habit muscle first with whatever small chunk you can spare without panicking, then scale the amount when your paycheck finally allows it.
11. Maximizing Your Employer Retirement Match
Allocate at least enough to capture your full employer match.
Leaving that money on the table is turning down free compensation.
Check your HR portal this week to verify your contribution percentage is set correctly.
12. Overcoming Scarcity Mindset About Money
Do you feel like there will never be enough money no matter how much you actually earn on payday?
Sound familiar?
That constant sense of panic keeps you trapped in high-stress financial loops where every single expense feels like a crisis waiting to happen.
What I believe now is that tracking creates awareness, and awareness replaces that daily panic with a concrete plan you can actually manage.
Take fifteen minutes this weekend to list your accounts and balances without a single drop of judgment, starting with just $500 or whatever you have right now.
Your First Year Roadmap
13. Targeting High Interest Debt First
I spent months throwing extra cash at a low interest car loan while a credit card carrying a 21 percent interest rate bled me dry every single month.
Pay off any balance sitting above 20 percent APR before you chase aggressive investments, because no index fund reliably beats a guaranteed 21 percent return on eliminated debt.
Knock out the smallest balances first for quick psychological wins, and set up your auto payments today so that high interest debt starts shrinking by tomorrow morning.
14. Scaling Back When Life Gets Expensive
Drop your savings rate temporarily if medical bills or childcare strain your monthly cash flow.
You do not need to quit entirely and zero out your progress just because an unexpected $400 expense landed on your desk.
Lower the amount from $300 a month down to $25 until the storm passes so your habit stays alive.
I did this for six months when my car repairs spiked, and keeping that tiny $25 transfer running kept me from walking away from the whole system.
15. Building Consistency Through Small Habits
You probably feel like you are already too far behind for tiny habits to matter.
It is easy to look at retirement accounts online and feel completely defeated by how far away the finish line looks.
The truth is that compounding does not care about dramatic gestures or overnight windfalls. It relies on a very boring mechanism where small amounts, say $25 or $50 automatically moved each week, accumulate quietly over years of your life. When you automate those transfers, you completely remove willpower and emotion from the equation, letting steady repetition do the heavy lifting while you focus on living.
If you can only manage ten dollars a week right now, start there.
That tiny amount beats the zero dollars you keep meaning to invest next month.
The trade-off is that it feels painfully slow at first. Your balance will barely budge for the first year, and you will wonder if it is even worth the trouble.
I spent years waiting for a larger paycheck before I started taking this seriously, which just meant wasting time I won't get back.
Give yourself permission to be imperfect, open your banking app today, and set up one recurring transfer for whatever you can comfortably spare.
Frequently Asked Questions
Is it too late to start investing at 40?
It is never too late. Starting at 40 gives you two decades of compounding growth, which is plenty of time to build a solid foundation if you stay consistent with your monthly savings rate.
How much should I have in my emergency fund?
Aim for one month of bare expenses first, then gradually build toward three to six months. This cushion prevents unexpected car repairs or medical bills from turning into high-interest debt.
Should I pay off debt or save for retirement first?
Capture your employer retirement match first because it is free money. Then direct extra funds toward any high-interest debt carrying rates above 10 percent before scaling up investments.
Is it okay to pause my retirement contributions for a while?
Yes, if you face a genuine life disruption like a job loss or major medical expense. Pause temporarily, handle the immediate pressure, and resume your automated transfers as soon as stable.
What I'd Do First
Pick one move from this list and set it up before you close your browser today.
Your future self will thank you for starting with a single small step.