Everyone else your age appears to have it handled, and you are quietly certain you do not. Here is the fact that closes the gap: comparison is not a plan, and the only balance sheet that changes your 70s is yours.
Yours reads $95,000 in a 401(k), $18,000 in a Roth IRA, $12,000 in a taxable brokerage, $4,200 in an HSA and $3,000 in cash. Take-home is $5,600, essentials are $3,200, and about $600 a month is genuinely free. That $600 feels too small to move a retirement number.
It is not, because there are 25 years between now and 70. Moving the 401(k) from 3% to 6% costs $205 from take-home and collects $102.50 in employer money. Two hundred fifty a month fills a $9,000 reserve in about two and a half years. A $100 Roth transfer and the $280 car payment, redirected when the loan ends, ask for no new budgeting at all.
Ten boring moves, ordered by what they cost and what they protect, are what change the math by 70. The first question is not which investment wins. It is which move goes first while the cash reserve is still thin.
What follows covers the start order when the reserve is under $9,000, the monthly cost of each move, and the 90-day sequence: capture the match, build the reserve, automate the first $100 Roth, then postpone the rest and review on your next birthday.
Quick Tips Before You Start
Automate on payday
Set every transfer for the morning your paycheck lands, not the end of the month.
Cash before investing
Get the employer match first, then the $9,000 reserve, then everything else.
Leave the funds alone
A low-cost target-date or broad index fund beats tinkering every single year.
One review date a year
Pick your birthday and do all the checkups on that one day, not monthly.
Small counts
$50 a month automated for 25 years is $15,000 of contributions plus growth.
1. Full Employer 401(k) Match
I sat down to check mine once and found I had been leaving $102.50 a month on the table for years because 3% felt like the responsible number. It is not. At $82,000 of salary, the employer pays 50 cents on every dollar you put in, up to 6%. Three percent skips half of it.
So here is the smallest version of this move. If $205 a month out of your take-home is more than you can stand right now, go to 4% this paycheck. That costs about $68 and still pulls in employer money on every dollar. The match is not all-or-nothing; it is paid per dollar, which means the partial version beats waiting for a perfect month that never comes.
The full step from 3% to 6% adds $205 to the $95,000 already in the 401(k) and brings $102.50 of employer money with it. That is roughly a third of the $600 you have free each month, and it is the highest return available to you before a single dollar goes into a taxable account. Both your money and theirs then sit invested for the 25 years to 70.
Check the fund menu once. You want a low-cost target-date fund or a broad index fund, not a stack of choices you will never touch again. Then leave it alone and let the payroll deduction do the work.
If cash is genuinely tight, scale to 4% and raise it a point at your next raise. You are still capturing free money, and you have not quit.
💡 Tip: Log in to your 401(k) portal and change the contribution percentage today. It takes about three minutes and applies to your next paycheck.
| Move | Monthly cash or change | What compounds by 70 | Best first move for |
|---|---|---|---|
| Full 401(k) match | +$205 from take-home | +$102.50/month employer money for 25 years | Anyone with an employer match |
| $9,000 cash reserve | $250/month for 24 months | Stops forced selling and new card debt | Thin cash reserve |
| 1% annual escalator | ~$68/month per point, from raises | Two points over two raises | Savers with yearly raises |
| Automated Roth IRA | $100/month | $30,000 of contributions plus growth | No workplace Roth option |
| Car payment redirect | $280/month at payoff | 22.5 years of redirected payments | Soon-ending installment loans |
| Invested HSA | $50/month by payroll | Longest tax-free runway available | Low medical costs, reserve full |
| Recurring-bill audit | $40/month found | ~$480/year sent to the Roth | Tight monthly cash |
| Annual rebalancing | $0 | Keeps the mix aligned to 70 | Hands-off savers |
| Social Security plan | $0 | Covers ~$2,450 of the $4,800 target | Within 15 years of claiming |
| Yearly income check | $0, one page | One adjustment a year instead of a new plan | Everyone, every birthday |
2. A Nine-Thousand-Dollar Cash Reserve
The car needs $2,100 of work and the savings account says $3,000, so it goes on the card and now the month has a payment in it. That is the mistake, and it is almost never a discipline problem. It is a buffer problem.
Three months of $3,200 essentials is $9,600; round it to $9,000 and call that the target. You are starting at $3,000, so $250 a month gets you there in about 24 months. Keep it in a separate savings account, not the checking account, so it is awkward to raid and obvious when it is full.
This buys no return. It buys time, which is what keeps a repair from turning into a credit-card balance or a forced sale of investments at the worst moment. That is why it comes before extra investing, while the match already runs on its own.
⚠️ COMMON MISTAKE
Don't invest the reserve
A cash reserve earns little on purpose. Its job is to be there on the Tuesday the water heater dies, not to grow. Investing it means selling at the worst possible moment.
3. An Annual One-Percent Escalator
The belief is that saving more means feeling poorer this month, so the increase keeps getting postponed to a raise you have not received yet. The fix is to commit the raise before it arrives, not the paycheck you are living on now.
Set the rule once: every annual raise, the 401(k) goes up one percentage point. Start at 6% after the match and the reserve are handled, and two raises take you to 8%. At $82,000 of salary, one point is about $68 a month, and a $2,500 raise covers it with room left over.
If a full point feels steep, take half. Redirect half the raise to the 401(k) and let the other half show up in your checking account, so the raise still feels like a raise. The percentage is not sacred; the automatic bump is.
This depends on getting raises. If you do not, the same idea works with the $280 car payment when that loan retires in 30 months, because the cash flow already exists and only the destination changes. Either way, each $68 that goes in early has the full run to 70 to compound, which a dollar added at 60 does not.
Which move to do right now, soon, or later
- Capture the full 6% employer match — Costs $205 from take-home and returns $102.50 in employer money. Do this before anything else.
- Fund the $9,000 cash reserve at $250/month — Runs alongside the match and finishes in 24 months.
- Set the 1% annual escalator rule — Costs nothing today; it triggers on your next raise.
- Automate $100/month to a Roth IRA — Start after the reserve hits $9,000, or split to $50 in the meantime.
- Add $50/month by payroll to the HSA — Only once the reserve is full and you keep $2,000 of the HSA in cash.
- Invest the brokerage balance more aggressively — The taxable account is $12,000. Do not stretch it while the reserve is thin.
- Borrow from the 401(k) for a repair — This is exactly what the $9,000 reserve exists to prevent.
Order assumes no pension and no other cash reserve.
4. Automated Roth IRA Contributions
Automate $100 a month from each paycheck into a low-cost Roth IRA fund, and set the transfer for payday so the money leaves before there is anything to spend it on. A Roth IRA is a retirement account you fund with money that has already been taxed, so qualified withdrawals in retirement come out tax-free. The $100 is the smallest new line item in the plan and the one that asks the least of you, because a target-date or broad index fund inside the account does the investing on its own schedule, not yours.
Over 25 years, $100 a month is $30,000 of your own contributions plus whatever growth the fund earns, which no one can promise and some years will be negative. If the $9,000 cash reserve is not yet funded, send $50 now and move to $100 when it is. Check first whether your workplace offers a Roth option, since payroll is simpler than a separate account.
Then leave it alone. The whole point of automating on payday is that you never see the $100 sitting in checking, deciding whether this is a good week to invest.
💡 Tip: If $100 strains the budget while the reserve is filling, start at $50 and bump to $100 when the reserve crosses $9,000.
Four Ways This Plan Quietly Falls Apart
5. Redirect the Car Payment at Payoff
Set the car payment to redirect the month the loan ends. Right now $280 a month goes out with 30 months left on the loan, and the day that balance hits zero, that $280 should go to the Roth IRA first and to the taxable brokerage after that, automated for the same day of the month the car payment used to come out. The reason to build the $9,000 cash reserve first is timing: the loan runs another two and a half years, so the reserve has room to fill before the payment is freed.
The quiet failure here is what happens if you do nothing. A payment that vanishes into checking gets spent, and a payment replaced by a new car loan keeps you in the same place.
Redirecting the existing cash flow instead means no new budget decision, ever.
On a straight contribution count, $280 a month from month 30 to age 70 is 22 and a half years of deposits, somewhere north of $75,000 of your own money in before any growth, and growth on top of that depends on markets nobody can forecast.
That is the difference between a car payment and a retirement contribution: same amount, same day, different destination.
This one suits anyone staring at an installment loan with a visible end date, because the hardest part of saving is usually finding the slack, and here the slack already exists.
The trade-off is that you are committing the money before you know what the next car will cost. If the plan is to replace the sedan at 200,000 miles, price that now and carve out a separate car fund rather than letting the redirect eat the whole $280 and then borrowing again.
A car loan is not the enemy. A car loan you pay for the rest of your life is.
6. A Retirement Account in the HSA
Fifty dollars a month through payroll is the smallest contribution in this whole plan, and the only one that has to clear two checks before it starts: the $9,000 cash reserve fully funded, and a real look at your medical costs. The $4,200 already sitting in the work HSA is not doing much right now, and with no payroll contribution going in, you are passing up the one account where deposits can go in pre-tax, grow untaxed, and come out tax-free for qualified medical costs. That triple treatment is why it gets called the best retirement account most people ignore. For the specific contribution and investment rules that make the HSA work, see HSA retirement account rules.
The order matters more than the amount. Once the reserve is built, $50 a month by payroll is painless, and it has 25 years to compound before 70. Keep $2,000 in cash inside the HSA for current medical costs and invest the remaining $2,200 only after that reserve is done, so a medical bill never forces you to sell at a bad moment. Save the receipts for anything you pay out of pocket, because you can reimburse yourself years later. This step belongs in front of a tax professional or your plan's own HSA documents, not a blog – the qualified-expense rules and payroll limits are specific enough that a free fifteen minutes with a CPA is cheaper than a mistake.
HSA at 70 – What It Becomes
💵 The $50 a month
Grows to roughly $40,000 in 25 years at 7%
📈 What it covers
About 17 months of the $2,350 monthly gap
🔁 Receipt strategy
Pay cash now, reimburse yourself tax-free anytime later
🚧 No deadline
No rule forces you to reimburse in the same year
🧾 First move
Open a receipt folder today – one email address works
⏭️ Skip this if
Your plan charges a monthly HSA fee over 0.5%
The catch
Projected growth is not guaranteed – a bad decade changes the $40,000, and you still need the $9,000 reserve first.
7. A Yearly Recurring-Bill Audit
You stop paying for things you forgot you owned. That is the whole move, and it costs one afternoon a year rather than a changed life.
Pick one month, the same one each year, and write down every recurring charge that leaves your account on a schedule: phone, internet, home and auto insurance, and the subscriptions you signed up for in a weak moment and never cancelled. Two of those calls usually do it. So does one subscription you cancel without thinking twice. The target is $40 a month, about $480 a year, and that number is a floor, not a fantasy, because most people are carrying a few charges they would not re-buy today if the bill appeared in front of them.
when you knock $40 off a bill, set the $40 to go to the Roth IRA automatically, not back into checking where it will quietly become groceries. This is the difference between an audit that saves money once and one that saves it for the remaining decades. The $40 is found in spending that already exists, so it does not compete with the $600 that is already committed.
This suits the saver who feels like there is nothing left to redirect. If your bills are already lean and your subscriptions are already cancelled, this is not your move, and skipping it is not a failure. It is just true that there is nothing here to find.
Where the $40 Found by the Audit Should Land
Do this with it
- Automate $40 to the Roth IRA on payday
- Treat it as permanent, not one-time
- Repeat the audit every 12 months
- Recheck insurance at the same time
Not this
- Leave it in checking to be absorbed
- Spend it as a reward for the effort
- Cancel and re-subscribe three months later
- Skip the audit because bills feel small
8. An Annual Rebalancing Checkup
You will not have to watch the market to keep this on track. One date a year, the same one every time, is enough, and the date on your birthday is as good as any. The fear is that staying invested means vigilance. It does not.
On that date, look at the three accounts together: the 401(k), the Roth IRA, and the taxable brokerage. First, confirm the mix still leans the way a 25-year timeline wants. Then, before you sell anything, use the next $50 or $100 going in to nudge the mix back where it belongs. New contributions rebalance for free; trades cost you money and attention.
Check one more thing: that the low-cost fund you chose still matches a plan to stop full-time work at 70. If you have never had a plan and cannot tell, ask the 401(k) provider for one before you touch anything. Hands-off savers get the most from this, and the whole check takes under an hour.
9. A Social Security Claiming Plan
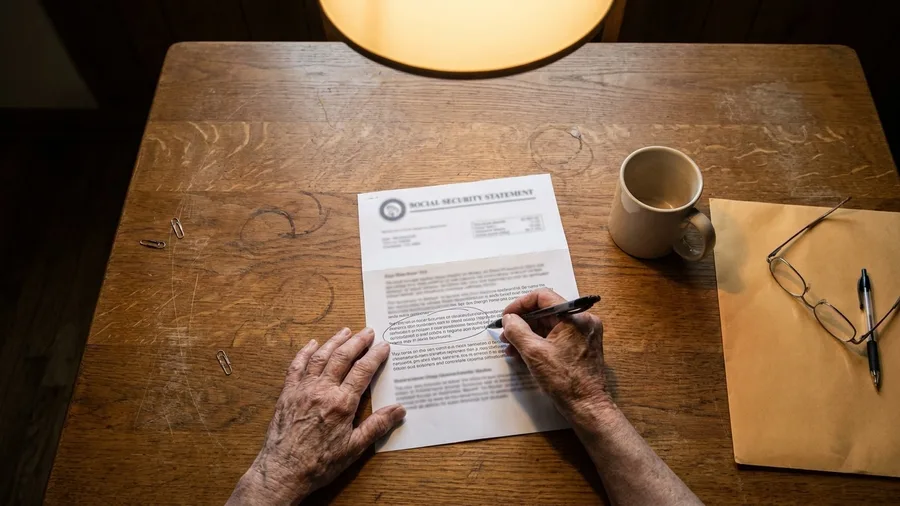
The thought that stops most people cold is that claiming the wrong year will quietly cost them five figures, and that they should already know which year is right. Here is what I found when I sat down with my own statement: the official estimate at 70 was $2,450 a month, the same figure this plan runs on, and the difference between claiming at 62 and at 70 was larger than I expected.
That number matters because of the target. A comfortable $4,800 a month in today's dollars leaves the portfolio covering about $2,350 once Social Security's $2,450 is counted. Social Security is covering half the bill, so the claiming decision is half the plan. The statement or the official calculator will show you your own estimate at each age, which is the only figure worth planning around.
The years before you claim are the ones that need a plan. If you stop work at 70 and claim then, there is no gap. If you stop earlier, you bridge the difference from the cash reserve, part-time work, or the taxable brokerage, and that bridge needs to be sized before you claim, not after.
This matters most within 15 years of claiming. If your health or your family history argues for claiming earlier, run that same official comparison anyway. Let the calculator answer the question, not a rule of thumb you heard at a barbecue.
Does the plan actually reach $4,800 a month?
Illustrative saver, age 45, $82,000 salary, 25 years to 70. Returns are not guaranteed.
Assumes 25 years of consistent contributions and a low-cost diversified fund. Markets go down in some years.
10. A Yearly Retirement Income Check
Write the whole picture on one page once a year: the 401(k), the Roth IRA, the taxable account, the HSA, and the official Social Security estimate pulled straight from your statement at ssa.gov. Set those against the $4,800 monthly target in today's dollars, and you find out in ten minutes whether the small automatic moves are doing what you think.
The Social Security estimate does most of the lifting here. At $2,450 a month at 70, it covers about half the target, which leaves the portfolio needing to produce roughly $2,350 a month. That single subtraction is the number the whole plan hangs on, and it is why the claiming decision has to be settled before this page is worth filling in.
One page, three columns. Account balances on the left, monthly contributions in the middle, the official Social Security figure on the right, and a bottom line that reads: portfolio must cover $2,350.
That bottom line is the only number you are actually checking. If the projected income clears it, the moves are enough and the year's job is to leave them alone. If it comes up short, the fix is one adjustment, not a rebuild.
Two levers exist for a shortfall, and both are already in the plan. Raise the 401(k) escalator by a single percentage point at the next raise, or send the $280 car payment to the Roth IRA the month the loan clears instead of waiting. Pick one. Making both at once is how a plan stops feeling manageable and starts getting skipped.
The timing matters more than the arithmetic. Do this on your birthday, the same date every year, so the page becomes a record rather than a scramble. Five birthdays from now you will have five pages, and the line you care about is the direction the bottom number is moving, not any single year's figure.
One adjustment a year is the entire discipline. A plan rebuilt every month never gets tested long enough to know whether it works.
If the gap is large enough that neither lever closes it, that is the point to take the page to a fee-only fiduciary who charges by the hour and does not sell products, rather than guessing at a bigger number on your own.
Frequently Asked Questions
Is $600 a month actually enough to make a difference by 70?
It is enough to change the math, not to promise a number. This plan uses about $205 for the match, $250 for the cash reserve, $100 for the Roth and $50 for the HSA — most of the $600 — and each amount compounds for 25 years. What the balance ends up being depends on returns nobody can guarantee. The point is that every dollar of the $600 has an assigned destination instead of drifting.
Should I build the $9,000 reserve before or after the 401(k) match?
Match first, even with a thin reserve. The employer's 50 cents per dollar on your $205 contribution is free money that does not accumulate while you wait. The reserve comes second and takes about 24 months at $250 a month. The one exception is a genuine emergency on the horizon — then split the $600 between the two until the reserve has a few thousand in it.
Do I need a financial advisor for any of this?
For most of these moves, no. The one place it is worth a conversation is Social Security claiming age combined with your tax situation, because that depends on numbers only you have. A fee-only fiduciary or a CPA can run that comparison once. Make sure the person is fee-only, meaning they are paid by you and not by commissions on what they sell you.
Is it worth putting money in a Roth IRA if I already have a 401(k)?
Yes, once the match is captured and the $9,000 reserve is funded. The Roth is funded with money you have already paid tax on, and qualified withdrawals in retirement come out tax-free. It also gives you a second pot of money with different tax treatment, which gives you more options at 70. If your workplace 401(k) has a Roth option, check that first, because payroll deduction is easier to automate.
What if I have no annual raise to hang the escalator on?
Then skip the escalator and use the car-payment redirect as your increase instead. When the $280 loan ends in 30 months, that cash flow gets redirected automatically. The escalator is just a mechanism for raising your savings rate without a budget decision. If no raise comes, the loan payoff is the substitute.
How often should I review all of this?
Once a year, on one date — your birthday is the easiest to remember. Do the bill audit, the rebalancing check, the Social Security comparison and the income check in the same sitting. Reviewing monthly invites tinkering, and tinkering is what turns a working plan into a worse one.
Capture the match, fill the reserve, send the first $100 — then wait
The verdict is plain: these ten are one ordered system, not ten equal tips, and the first three are the match, the $9,000 reserve, then an automated Roth.
Next 90 days: raise the 401(k) from 3% to 6% for $205 out of pocket and $102.50 in employer money, open a separate savings account with a $250 automatic transfer toward the $9,000, and once the reserve is funded automate $100 a month to the Roth. If cash is tight, postpone the HSA payroll amount and the taxable brokerage, keep the match and the $250, and hold the Roth at $50 until the reserve fills.
On your next birthday, one sitting: bump the escalator, rebalance across the accounts, pull the official Social Security estimate and refresh the one-page income gap.
So the $600 that felt too small now has an order to it, and the $125,000 already working in the 401(k), Roth and taxable has somewhere to go. That quiet certainty about being behind turns out to be a head start you can set up this week.
Do the three-minute version today
Open your 401(k) portal, change the contribution to 6%, and set the $250 transfer to a separate savings account. Two settings, and the 25-year clock starts running.