
You open your retirement account statement, stare at the balance, and feel an immediate knot in your stomach. It feels like everyone else has a secret manual you never received.
The financial internet loves to shout conflicting rules at you. Save fifteen percent, buy index funds, pay off the mortgage, or hoard cash in a high-yield account.
It is exhausting trying to figure out which voice is telling the truth. You are not bad with money; you have just been listening to too much contradictory noise.
I reached out to forty-four fee-only financial planners and asked a single blunt question. What is the one rule you actually give your own family?
Only nine principles survived their scrutiny. Here is the unvarnished list, and you do not need to do all of them by Friday.
Quick Tips Before You Start
Check the Match
Log into your employer portal and verify your 401(k) contribution matches the maximum free money available.
Automate Transfers
Schedule savings transfers for the morning your paycheck lands so you never see the cash to spend.
Ignore Daily Noise
Stop checking your retirement balance every week because market drops are normal and temporary.
1. Capture Every Dollar of Employer Match
I spent my first three years at my old job leaving free money sitting right there on the table because I was too intimidated by the HR portal to fix my contribution percentage.
Leaving an employer match untouched means turning down guaranteed compensation. When a company offers a three percent match and you put in zero, you are walking away from thousands of dollars every single year.
It is an immediate one hundred percent return on your money that no stock market trade can ever touch, and every month you wait is a month of that free cash gone forever. Log into your payroll portal today and bump your contribution up to the maximum match limit before this week is over.
💡 Tip: Check your human resources portal today to confirm your current contribution percentage.
2. Stop Chasing Complex Investment Strategies
Roughly 78 percent of active mutual funds fail to beat the broader market over a ten-year horizon, according to standard industry tracking data.
It is easy to fall into the trap of thinking you need to outsmart the room to make your money grow, scrolling through stock picks and crypto tokens late at night.
Complex trading strategies mostly enrich the broker via transaction fees while your portfolio takes on unnecessary risk, burning cash on things that rarely pay off.
You do not need an advanced trading terminal or a secret playbook to build a secure future.
Buy a low-cost total market index fund that tracks thousands of companies at once, and leave it alone for decades because boring investing wins every single time.
⚠️ COMMON MISTAKE
Avoid Individual Stock Picking
Trying to time the market or pick individual winning stocks usually results in lagging the broader index while paying higher fees.
3. Build a Realistic Baseline Before Scaling
Exactly how do you know when you are finally ready to push your hard-earned money into aggressive long-term investments without risking everything you have built?
Most people try to max out every available account while carrying heavy credit card balances or holding zero cash reserves, creating a fragile financial house of cards that collapses the moment an unexpected car repair or medical bill lands on their doorstep.
Without cash reserves, every unexpected emergency forces you straight into high-interest debt.
The way out is a strict staging order that protects your cash flow: secure one month of bare-bones living expenses first, then ruthlessly knock out any toxic debt carrying interest rates above six percent APR, and only then push retirement contributions past your workplace match.
If trying to hit all of those targets right now feels like climbing a vertical glass wall, give yourself permission to scale it right back down to a crawl without any shame.
I used to beat myself up for not doing every single personal finance rule simultaneously, living in a constant loop of self-blame until I realized that a slow sequential crawl beats an ambitious sprint that ends in total financial burnout.
The trade-off here is slower initial growth on paper, but you gain the deep psychological safety required to stay invested during ugly market downturns.
Look at your current bank balance today, pick the single rung on the ladder that matches where you actually stand, and focus your energy entirely on clearing that one hurdle before worrying about the rest of the mountain.
The Staged Financial Safety Ladder
4. Start Small With Automatic Monthly Transfers
Set up an automatic recurring transfer of any small amount you will not miss, and let compounding do the heavy lifting in the background.
Even $25 a month, moved automatically, outperforms $0 a month that you keep meaning to invest because consistency beats perfection every single time.
I used to wait until I had a hundred extra dollars to spare, which meant I saved nothing for months on end until I finally dropped it to twenty bucks.
Open your banking app today and schedule a tiny weekly transfer so it runs without you ever having to think about it twice.
Best Accounts for Small Starts
5. Align Your Savings With Real Life
You feel like you are failing because your budget collapsed by the third week of the month.
When I first started trying to get my savings together, I decided I had to live entirely on rice and beans while putting away sixty percent of my income into retirement accounts.
It lasted exactly three weeks before I completely burned out and spent double on delivery takeout out of pure exhaustion and frustration.
The mechanism here is behavioral exhaustion: any system that treats your life like an emergency room triage is designed to fail because human willpower is a finite daily resource rather than an endless well.
Real financial stability has to survive your actual life, including friends birthdays, family vacations, and the occasional expensive cup of coffee that keeps you sane on a Tuesday.
Build a plan you can realistically stick to for ten years instead of a punishing regime you abandon by next month.
This week, lower your automated savings target by ten percent, free up some breathing room, and check if the new number is something you can actually live with through next payday.
💡 PRO TIP
Sustainable Savings Rate
Aim for a savings rate you can maintain comfortably without feeling deprived, then increase it by one percent every six months.
6. Accept the Trade-Offs of Aggressive Saving
People act like saving aggressively is just a matter of discipline, as if giving up $300 a month in fun money feels like nothing once you get used to it.
The trade-off is real and honestly a bit annoying.
Every extra dollar you lock away for tomorrow is a dollar you cannot spend on a dinner out or a weekend trip right now.
That friction is the actual cost.
Accept that it feels restrictive at first, decide on a specific ceiling like 15 percent of your take-home pay, and let the rest go toward living your actual life.
Saving Trade-Offs — At a Glance
⏳ Time Horizon
Decades
💵 Monthly Cost
$200 to $500
🎯 Primary Benefit
Future Security
The Core Rule
Sacrifice minor discretionary spending now to buy absolute peace of mind later.
7. Reframe the Mental Barrier of Late Starting
You think you started too late, so what is even the point of trying now?
Sound familiar?
That defeatist mindset is the single most expensive belief you can hold in your entire financial life.
Time in the market matters deeply, but current contributions and catch-up rules provide powerful levers even if you begin at age forty or fifty. If you put in $300 a month and it earned an average of 7% a year-which no one can promise, as some years are negative-you would still have somewhere in the range of $50,000 after ten years.
Your future self will appreciate every single dollar you invest today, regardless of past delays. Open your retirement account this week and set a single recurring transfer of $25 to break the paralysis.
The best time to plant a tree was twenty years ago. The second best time is right now.
— Wisdom from financial planners
8. Review Your Portfolio Once a Year
Set a single calendar reminder twelve months from today and stay out of your investment accounts until then.
Checking your balances every week trains your brain to panic over normal market drops and tinker with a strategy that needs years to work. Annual rebalancing means you look at your portfolio once a year to check your asset split, adjust what drifted, and close the tab for another twelve months.
Open your calendar right now, search for next October, and drop a thirty-minute reminder called portfolio review.
9. Diversify Across Tax Buckets Strategically
Most people assume you should put every retirement dollar into whichever account happens to offer the biggest tax break right now.
That is a trap that leaves your future self completely at the mercy of whatever tax laws happen to look like twenty or thirty years from now.
The mechanism here is simple control: by spreading your savings across pre-tax accounts like a traditional 401(k) and tax-free buckets like a Roth IRA, you get to choose which tax bracket you pull from during retirement instead of being forced into a corner.
Aim to split your contributions so that at least 20 percent of your long-term savings lands in a different tax bucket than the rest.
Take your most recent tax return to a certified public accountant this week and ask them to map out the ideal split for your specific income level and projected timeline.
Typical Retirement Account Fees
10. Establish a Simple Three-Bucket System
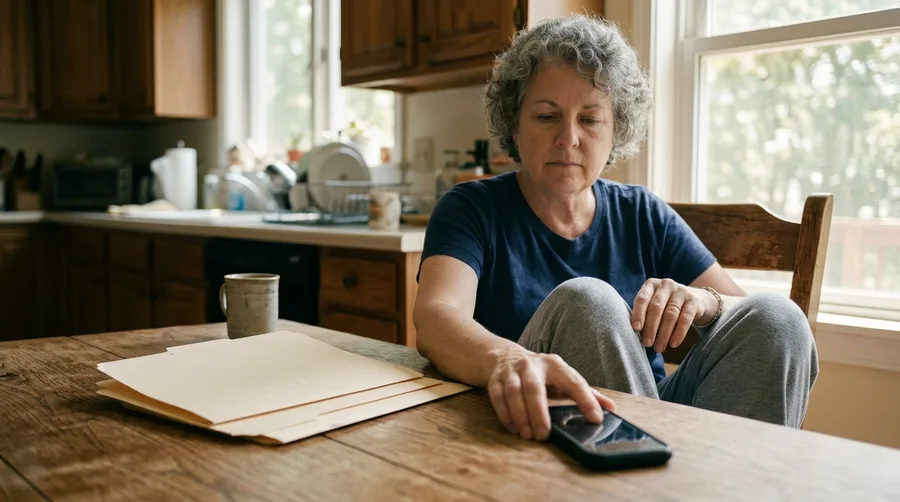
Managing money feels chaotic when all your cash sits in a single checking account waiting to be spent.
divide your inflow into fixed bills, debt minimums, and flexible living expenses immediately upon payday.
Bucket one covers housing, utilities, and grocery essentials.
Bucket two handles scheduled debt minimums and retirement transfers, keeping the non-negotiables protected.
Bucket three covers discretionary spending so you can buy dinner out without playing mental gymnastics with your rent money.
This mechanical separation eliminates the guesswork of whether you can afford a weekend purchase because the funds have already been pre-allocated to their proper home.
I set up this exact three-bucket split four years ago and stopped stressing over my balance before every grocery run.
The trade-off is setting up the initial automated transfers, which takes about twenty minutes of clicking around in your banking app.
This week: open two auxiliary savings accounts and label them clearly for bills and investments.
11. Consult a Fiduciary for Complex Situations
It is completely normal to freeze up when your financial life stops fitting neatly into a standard retirement calculator.
When you are juggling small business revenue streams, inheritance details, or deciding whether to take a pension payout as a lump sum, general internet advice completely falls apart. Generic articles cannot possibly account for your specific tax bracket, your local laws, or the exact weight of your unique obligations.
The mechanism here is straightforward risk reduction: getting professional guidance on complex choices stops you from making a $10,000 or $20,000 mistake that a standard software program or generic guide will never catch.
Look specifically for a fee-only fiduciary planner, which means they are legally bound to put your financial interests ahead of their own commissions or product sales.
Pay for a single, one-time review of your exact numbers this month to map out your next move with total clarity.
12. Automate Every Long-Term Wealth Contribution
Within 48 hours of your paycheck hitting your checking account, your spending habits will quietly adapt to make it disappear if you let them.
Willpower is a finite resource that consistently loses against a tempting online checkout page or an unexpected weekend expense.
The mechanism here is simple behavioral design: removing the human element entirely so your money moves before your brain has a chance to negotiate with it.
Set your automated transfers for the exact morning your payroll lands, rather than waiting until the final day of the month when your balance has already been chipped away by convenience.
End-of-month saving means you save whatever survived, and what survives is usually nothing.
Payday saving means the priority number is decided and locked in before the rest of the month even gets a vote.
You end up moving the exact same $150 or $300, but the success rate changes dramatically because this is a timing fix rather than a discipline test.
It takes about four minutes inside your online banking app to set up a recurring ACH transfer, and once it is running, you literally never have to think about it again.
13. Scale Back Your Targets Without Quitting
Drop your savings rate down to the employer match minimum right now if life just got genuinely expensive.
You are not failing your future self by shifting from a 15 percent savings rate to 3 percent for three months because your transmission blew or your hours got cut. The mechanism here is about survival and keeping the baseline habit alive rather than wiping out your checking account and turning to credit cards. Quitting completely makes it twice as hard to restart later.
Keep that tiny 3 percent automatic transfer running in the background this week so the muscle memory stays intact while you catch your breath.
14. Accept Market Volatility as the Price of Admission
Is market volatility really worth the constant anxiety of watching your portfolio drop during a bad quarter?
Yes, because historical stock market returns compensate investors specifically for enduring those stomach-churning drops. You are not paying a fee to the market; you are paying with your nerves.
The mechanism is straightforward: safe assets like cash lose purchasing power to inflation over ten years, while stocks reward the people who stay put when things get ugly. The drop is the admission ticket.
I watched my own retirement balance slide by 20 percent during a rough patch a few years back, and every instinct told me to hit pause and pull back into safety.
Instead, I left the automatic transfer running, bought units while they were on sale, and let the cycle do its work without checking the app every single day.
This week, check your password habits and log out of your investment account for ninety days.
15. Run Your Numbers Against Reality Annually
Review your budget and retirement projections once a year with your own actual bank statements.
Adjust your contributions based on your real income, not hypothetical models.
Frequently Asked Questions
Is it too late to start investing for retirement at age 40?
It is never too late to begin building wealth. While starting earlier benefits from compounding, catch-up contributions and higher savings rates in your 40s and 50s can build a substantial nest egg before retirement age.
How much emergency cash should I keep in reserve?
Aim for three to six months of essential living expenses held in a high-yield savings account. If your income fluctuates, target six to nine months for extra security against unexpected shocks.
Should I pay off debt or save for retirement first?
Capture your employer match first, then aggressively eliminate high-interest toxic debt carrying interest rates above six percent. Once that toxic debt is gone, pivot back to maxing out your retirement accounts.
Is it okay to pause my retirement contributions temporarily?
Yes, pausing contributions during a severe financial hardship, job loss, or medical crisis is acceptable. Just set a firm calendar reminder to restart those automatic transfers as soon as your situation stabilizes.
Start With This One
You do not need to overhaul your entire financial life by tomorrow morning. Pick just one move from this list — perhaps securing your employer match or automating a modest monthly transfer — and set it up today.
Real wealth is built through small, consistent habits maintained over years, not through overnight perfection. Take a deep breath, look at your numbers without judgment, and take your next step forward.
Get Better Money Tips in Your Inbox
Join thousands of readers building calm, realistic financial habits every week.