You think you need to hand in a dramatic resignation letter and jump straight into the void to change your life.
As a former corporate marketing director making $125,000 annually, I felt that exact panic and stayed in a high-stress career years longer than I should have.
Quitting cold turkey creates immediate terror, but a 24-month gradual taper replaces that fear with structured execution.
By breaking the exit into four six-month stages, you can systematically bridge corporate life and independent consulting while protecting your savings.
Decide how to scale back your hours, budget for medical shifts, and execute the final step to zero income with complete financial security.
Quick Tips Before You Start
Four Stages
Divide your transition into four distinct six-month blocks.
Twelve Months
Save a full year of living expenses before dropping your first hours.
Bill Rate
Set your independent consulting fee at seventy-five dollars an hour.
Tax Shifts
Pivot from traditional to Roth retirement accounts as income drops.
1. Employer pushback vanished with a structured runway
Staring at your manager across a desk while you prepare to ask for reduced hours feels like stepping onto a ledge without a harness. When I sat down to pitch my departure from a $125,000 corporate role, my chest was tight because I expected immediate panic or a flat rejection. You are not the first person to worry that asking for less will get you shown the door.
The trick is walking in with a blueprint instead of a vague request. I presented a structured 24-month exit plan that completely disarmed my boss, mapping out a concrete knowledge-transfer schedule in month one to cover every key operational responsibility. We secured a written agreement for part-time hours alongside a $75 hourly consulting contract that kept me afloat.
Before you sign anything or tell your team, run your specific numbers against a fee-only fiduciary or a CPA to make sure your tax withholding and cash flow can handle the shift. It protects you from surprises.
| Phase | Primary Income Source | Monthly Work Hours | Monthly Savings Rate |
|---|---|---|---|
| Months 1-6 | Corporate Salary ($125k) | 40 hours/week | 35% |
| Months 7-12 | Part-Time & Consulting ($60k) | 25 hours/week | 15% |
| Months 13-18 | Boutique Clients ($25k) | 12 hours/week | 5% |
| Months 19-24 | Full Independence ($0) | 0 hours/week | 0% (Drawing Buffer) |
Transition Jargon Decoded
2. Health insurance costs doubled faster than hours dropped
Stepping away from full-time employment feels terrifying, but you do not have to guess at the financial fallout. Dropping your hours instantly exposes the stark reality of losing corporate benefit subsidies, and the sticker shock on medical coverage hits faster than you expect.
When I lost my employer plan, I compared group premiums directly to ACA bronze and silver tier policies and found out-of-pocket costs doubled overnight. My simple system to handle this shock is mapping every independent policy by its out-of-pocket maximum first, then pairing it with a health savings account to offset higher deductibles.
Marketplace Plan Checklist
3. Lifestyle inflation disguised itself as sanity treats
Higher fixed medical costs collide directly with newfound free time that immediately distorts everyday discretionary spending. I remember sitting on my back porch on a random Tuesday afternoon during my first month of reduced hours, staring at a stack of takeout menus because my schedule suddenly had empty spaces where frantic meetings used to live.
Having more hours in the day quietly triggered higher spending on convenience and leisure before I even noticed the pattern. That extra time feels like a reward, so your brain reaches for little comforts to fill the silence.
Tracked incidental expenses like coffee runs and takeout during those first few weeks, and the total shocked my system.
When you stop going into a high-stress office every single day, you lose the free perks that quietly subsidized your habits, from the office coffee bar to the catered lunches. I had to audit my subscription services immediately to replace those corporate fringe benefits with actual line items in my own spreadsheet.
Established a strict monthly fun money allowance separate from the $4,200 monthly core living expenses so I could breathe without blowing the budget.
If you do not put a firm fence around your daytime spending right now, the freedom of a tapered schedule will drain your emergency runway faster than the actual reduction in work hours. Start this month by capping your daytime discretionary spending at a hard $150 limit, and treat every extra coffee as a conscious choice rather than a default habit.
The Sanity Treat Audit
Assumes casual spending habits during newly freed weekday afternoons.
Based on actual spending logs from transition month three.
4. Tax brackets were far more forgiving during the middle transition
Controlling discretionary spending opens the door to looking at broader structural changes, like how a falling salary alters your tax reality. Stepping down income tiers from $125,000 to $60,000 completely changes what you owe the government.
Even a tiny shift, like moving just $50 a month into a tax-advantaged account during a lower earning year, starts building a different kind of cushion. You do not need to convert tens of thousands of dollars on day one.
I calculated my marginal tax rate changes between my full-time salary and my part-time earnings, realizing the gap was an opportunity. That lower bracket meant I could execute strategic Roth IRA conversions cheaply without taking a massive tax hit.
You also have to adjust your quarterly estimated tax payments for any freelance consulting revenue coming in. Setting aside a percentage immediately stops tax season from turning into an expensive emergency.
Consistency over amount always wins when you are rewriting your tax strategy from scratch.
💡 PRO TIP
Exploit Your Income Drop
Lower earnings years are the exact window to move traditional retirement funds into Roth accounts at a fraction of your previous tax rate.
5. Freelance clients paid notoriously slower than corporate payroll
Forty-five days is an eternity when you are used to bi-weekly direct deposit hitting your checking account like clockwork.
The most common mistake when stepping away from a corporate salary is assuming that billing $75 an hour means having access to that money on Friday afternoon.
Corporate payroll runs on rails, but independent clients run on accounts payable departments that process invoices whenever they feel like it.
I watched my checking account dip dangerously close to zero during my third month of consulting simply because my first three invoices were caught in net-45 payment terms while my $4,200 monthly core living expenses kept marching on.
To fix that cash flow whiplash, I stopped taking projects without a fifty percent upfront deposit and built a dedicated two-month operating buffer completely separate from my main emergency fund to absorb the lag between sending an invoice and seeing the cash.
Client Invoicing Realities
6. My professional identity crisis hit hardest at month nine
Dropping my corporate title eroded my confidence long before my bank account ever felt the pinch of a smaller paycheck.
It is completely okay to feel unmoored and to do less of the heavy networking right now while your brain adjusts to the quiet. Redefining your personal worth entirely independent of corporate affiliation takes actual time and permission to stumble.
I found relief by connecting with peers who successfully executed similar lifestyle downgrades and establishing a simple daily routine to replace structured office hours.
7. Retirement contributions required a complete structural rewrite
People assume retirement contributions must stop entirely the moment you step away from a full-time corporate paycheck.
That myth cost me months of unnecessary hesitation before I calculated the exact loss of my employer matching funds as my annual salary dropped to $25,000.
Stopping traditional employer 401k plans forced a complete structural rewrite, shifting my priority to self-directed brokerage and individual retirement accounts where automated monthly transfers remove emotional decision-making.
Reviewing this transition twice a year means checking three specific metrics: my taxable income bracket, the volume of leftover cash flow redirected from lower expenses, and my ongoing pace of strategic Roth IRA conversions.
Retirement Saving Realities
8. Grocery bills spiked because I cooked with premium ingredients
Lock in a weekly grocery ceiling before your extra free time turns the kitchen into a hobby project that quietly drains your cash flow.
When I dropped my corporate hours down to part-time, my newly acquired afternoons suddenly filled with slow braises, artisanal flour experiments, and specialty market runs that felt like self-care after years of desk work.
That shift cost me dearly because I stopped treating food as fuel and started treating it as a creative outlet, pushing my weekly food spending from a tidy baseline right past $250 without me noticing until I checked the bank statement.
I was buying imported cheeses and heritage meats because I finally had the hours to cook them, completely forgetting that my reduced income could not sustain a gourmet lifestyle disguised as a stress-relief hobby.
To stop the bleeding, I set up a rigid automated weekly transfer of $125 into a separate grocery debit card and refused to step foot in specialty shops where every ingredient came with an artisanal markup.
I started batch-cooking simple staples on Sundays using basic supermarket runs, which removed the daily impulse to grab specialty items just because I had the time to prepare them.
You have to automate your food boundaries because cooking at home only saves money if you do not replace restaurant tabs with high-end grocery baskets.
Keeping your food costs aligned with lower earnings means accepting that your kitchen is a place to feed yourself affordably, not a boutique test kitchen.
9. Networking took twice as long without water cooler access
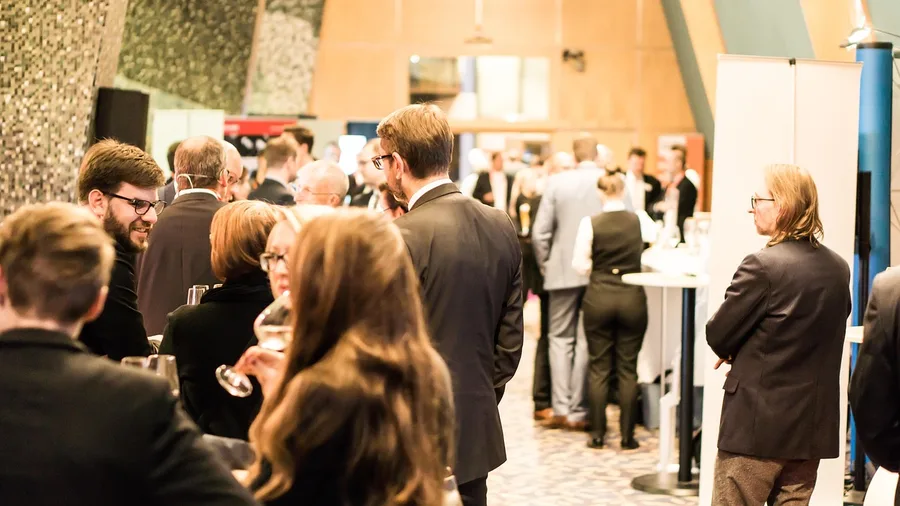
People assume that leaving a corporate job means your professional network stays intact automatically through LinkedIn messages and casual check-ins.
That belief falls apart the moment you realize how much of your career momentum relied entirely on casual water cooler chats and automatic daily interactions that vanished the day you handed in your reduced hours notice.
Building a reliable pipeline for independent consulting at a $75 hourly rate required deliberate, exhausting daily outreach completely outside corporate walls where nobody knew my old title.
I had to force myself into local industry meetups and digital co-working spaces, spending hours making small talk that felt entirely unproductive compared to my old structured office days.
I reached out to former colleagues who had already made the leap into independent contracting, treating business development like a mandatory part-time job by locking in five hours weekly strictly for networking calls and coffee catch-ups.
The trade-off is that networking without a corporate badge is lonely, deeply humbling, and takes twice as long to yield results, but it is the only way to replace a fading payroll with steady client revenue.
10. Emergency fund rules changed once income became variable
A standard six-month cushion felt entirely too risky, pushing the required target to a full 12 months of living expenses.
Calculated 12 months of bare-minimum survival expenses based on the $4,200 monthly core living expenses.
Kept the runway in a high-yield savings account earning baseline interest and ring-fenced the cash so it cannot be touched for investments or travel.
11. Spousal financial alignment saved the entire experiment
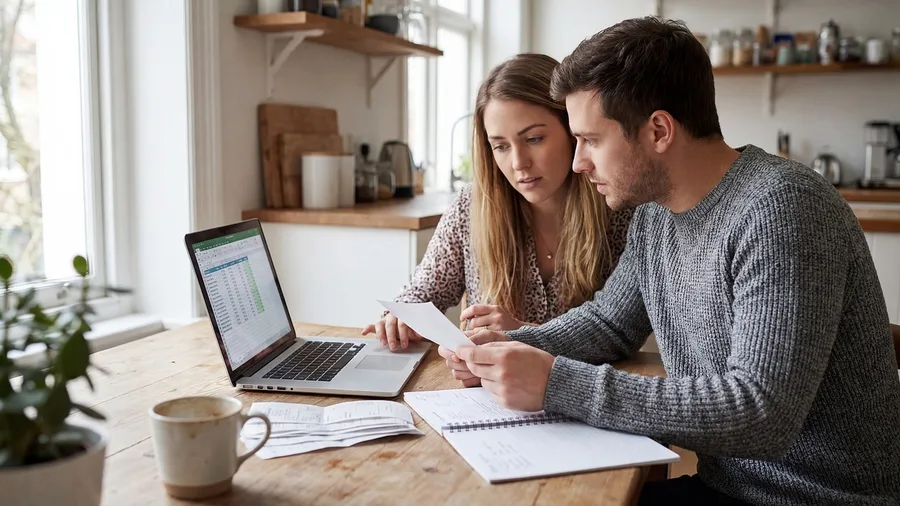
Transparently reviewing the shared burn rate prevented resentment during income drops from $125,000 down to $0.
Drafted a joint expense reduction ledger before giving notice.
Agreed on shared financial boundaries and emergency trigger words, and scheduled monthly financial check-ins to review actual versus projected spend.
If your partner is white-knuckling the budget while you enjoy your new freedom, the plan will implode by month six.
12. The final cut to zero income felt anticlimactic
Because the runway was so gradual across four six-month stages, walking away permanently was financially and emotionally anticlimactic.
Verified that side consulting revenue fully covers baseline living costs.
Confirmed all debt obligations are minimized or eliminated and celebrated the milestone without inflating lifestyle expenses.
When the drop is gradual enough, freedom does not feel like falling off a cliff.
Frequently Asked Questions
How much cash do I need before starting a phased career exit?
Aim for a minimum of 12 months of bare living expenses stored in a high-yield savings account before reducing your full-time hours.
What hourly rate should I charge when transitioning to freelance consulting?
A common benchmark is taking your previous full-time hourly equivalent and adjusting upward to account for self-employment taxes and lost benefits, such as $75 an hour.
How do I handle health insurance when leaving a full-time corporate job?
Compare marketplace bronze and silver tier plans during open enrollment, factor in your annual out-of-pocket maximums, and utilize health savings accounts to manage higher deductibles.
Why is a 24-month taper better than quitting cold turkey?
Gradual reduction allows you to test your cash flow assumptions, adjust lifestyle spending, and build consulting pipelines without financial panic.
Evaluating the True Cost of Phasing Out
Phasing out over twenty-four months takes immense patience, but it replaces career terror with mathematical certainty.
Before you tell your boss anything, verify that your twelve-month emergency fund is fully ring-fenced and untouchable.
You do not need to leap into the void to reclaim your time; you just need a spreadsheet and a willingness to step down slowly.
Ready to map your own two-year taper?
Review your monthly core living expenses today and calculate your twelve-month runway target before scheduling that conversation.