I spent my first year of retirement obsessing over portfolio yields while ignoring the quiet monthly bleed from our oversized property and outdated insurance policies.
It is easy to assume a seven-figure nest egg makes you permanently immune to cash crunches. In reality, core principal rarely drains from ordinary living costs; it erodes through rapid vehicle depreciation, bloated fixed overhead, and ongoing financial fees that siphon money automatically every thirty days.
Plugging structural balance-sheet leaks protects wealth far better than taking bigger market risks.
Here are eleven specific capital drains affluent retirees actively eliminate to keep their principal compounding, starting with the heaviest asset liabilities you can tackle first.
Quick Tips Before You Start
Audit Last Quarter
Print your last three months of bank statements to flag recurring charges.
Target Big Assets First
Depreciating vehicles and oversized square footage cause the largest balance sheet damage.
Check Fund Expense Ratios
Swap actively managed mutual funds charging over 0.50% for low-cost index options.
Use Schedule Flexibility
Book travel during shoulder seasons to secure luxury lodgings at half the cost.
Heavy Asset and Property Drains
Major physical assets can quietly become your portfolio's heaviest liability in retirement. Large vehicles, surplus real estate, and fixed vacation deeds generate zero productive yield while demanding non-negotiable monthly cash upkeep.
Protecting your principal starts with pruning these capital traps.
1. New Luxury Vehicles Lose Too Much Upfront Value
Twenty percent of a brand-new luxury vehicle's purchase price vanishes within twelve months, deepening into a 60% value drop over the first five years.
When reviewing transportation outlays, evaluate certified pre-owned vehicles aged two to three years instead of showroom inventory. That specific audit checkpoint bypasses the upfront depreciation cliff while keeping factory warranty coverage and reliable performance intact. You get identical driving utility without sacrificing capital to immediate valuation destruction.
Holding that pre-owned car across an eight-to-ten-year operating cycle preserves hundreds of thousands in compounding principal over retirement. That freed cash remains actively deployed in income-generating investments rather than sinking into pavement.
💡 Tip: Check certified pre-owned inventories right after new lease returns flood dealerships each autumn.
2. Oversized Family Homes Trap Cash in Maintenance
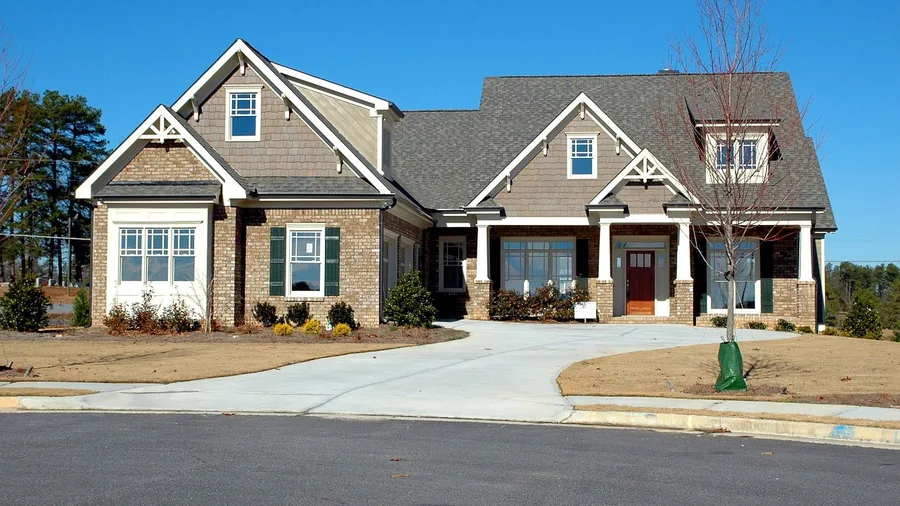
Why hold onto a sprawling four-bedroom house when the children moved out over a decade ago and your retirement savings can technically cover the utility bills and property taxes?
While a depreciating luxury vehicle bleeds capital on the road, an oversized stationary home quietly inflicts even greater ongoing damage on your cash reserves. Routine carrying costs – local property taxes, structural maintenance, climate control, and insurance policies – reliably consume between 1% and 3% of the total property value every single year.
Unused square footage produces zero yield.
On an $800,000 property, that annual overhead pulls anywhere from $8,000 to $24,000 straight out of your checking account. That substantial equity sits trapped in empty hallways and unused rooms rather than generating quarterly yield, turning what should be a peaceful sanctuary into an ongoing operational liability that constantly demands fresh cash for contractors and repairs.
Downsizing to a modern, right-sized single-story home frees up that trapped equity. Those liberated funds can immediately shift into dependable fixed-income ladders or dividend-paying portfolios that generate predictable cash distributions every quarter.
You do not need to downsize overnight.
Give yourself explicit permission to scale back the transition without abandoning the goal. If an immediate move feels overwhelming, start simply by shutting down climate control in vacant guest wings, trimming redundant landscaping contracts, and quietly exploring smaller neighborhoods to see what a lighter, lower-friction footprint looks like.
Eliminating surplus rooms permanently removes hefty landscaping bills, major repair liabilities, and bloated property tax drag from your monthly routine, keeping your retirement principal liquid, productive, and safely compounding.
Home Equity Allocation Comparison
The 100/0 Housing Asset Split — prescribing capital efficiency in retirement
3. Timeshares Lock Capital into Endless Annual Fees
You do not have to sacrifice family vacations or premium resort stays to protect your retirement portfolio from unnecessary long-term financial commitments.
While trimming primary housing costs stops local maintenance drains, vacation clubs present a far more rigid balance-sheet trap. These deeds carry zero secondary resale value – often forcing owners to pay exit transfer firms to abandon them – while demanding mandatory annual maintenance fees averaging $1,000 to $1,500 alongside uncapped special assessments for structural repairs.
Booking boutique hotels and private rentals on demand delivers identical luxury without lifelong contract liabilities. You preserve complete scheduling flexibility and protect travel liquidity by paying only for trips you actually take.
💡 Tip: Book luxury vacation rentals directly off-season rather than signing long-term resort point packages.
4. Whole Life Insurance Carries Unnecessary Overhead Costs
Many retirees believe a permanent life insurance policy is an essential safety net they must keep forever. In truth, once your accumulated assets cover your living expenses, you are self-insured and the death benefit becomes redundant.
I spent an afternoon reviewing a legacy whole life contract that was draining $4,600 every year in mandatory premiums. Between internal mortality charges, heavy administration overhead, and layers of agent commissions, the cash value grew at an anemic rate compared to what standard broad-market index funds typically deliver over decades.
Trapped cash value inside an insurance wrapper costs real money.
Surrendering an unneeded policy or moving the balance through a tax-free 1035 exchange frees up that stagnant capital for your own retirement. Before signing anything, consult a fee-only fiduciary to check for steep early surrender penalties or unexpected income tax consequences, making sure the exit does not trigger a surprise bill.
Funneling that former premium cash directly into your standard brokerage holdings stops the administrative bleed. You keep the liquidity on your own balance sheet instead of subsidizing an insurance company's overhead.
💡 PRO TIP
Self-Insurance Milestone Check
Once your accumulated investments and guaranteed income streams exceed your total retirement liabilities, paying high annual premiums for permanent death benefits is simply an unnecessary balance-sheet drag.
Lifestyle and Recurring Consumption Leaks
Daily spending habits rarely break a retirement plan on a single Tuesday. Instead, recurring premiums, duplicate services, and automated subscriptions steadily erode liquid purchasing power.
Pruning these expenses preserves discretionary travel funds without impacting your quality of life.
5. Premium Brand Labels Add Cost Without Extra Value
It feels reassuring to reach for familiar name-brand packaging on routine grocery runs. Decades of advertising train us to assume that paying extra for a recognizable household logo guarantees cleaner surfaces or better medicine.
In reality, everyday brand-name staples, cleaning solutions, and pantry goods carry a 20% to 30% price markup over store-brand alternatives with chemically identical formulas. Paying that premium on non-durable consumer goods creates an ongoing cash flow leak across thirty years of retirement without delivering any extra practical value.
Preserving principal requires purchasing efficiency instead of status signaling.
Start a simple thirty-day challenge on your next trip to the store by replacing name-brand over-the-counter medications, basic dry goods, and home cleaning supplies with private labels. Comparing the active ingredient labels on generic pain relievers or staple foods proves you get identical baseline performance while pocketing immediate savings on every receipt.
Shaving $30 off your weekly shopping basket keeps more than $1,500 in your pocket every year. That money stays deployed in your portfolio rather than disappearing into grocery company marketing budgets.
6. Unmonitored Subscriptions Silently Drain Monthly Cash Flow
Audit and cancel recurring digital subscriptions that bill your accounts without your active attention. Streaming platforms, fitness applications, cloud storage tiers, and online newspapers thrive on automated charges you simply forget to monitor.
Manual cancellations take an annoying afternoon of clicking.
The minor inconvenience of resubscribing on a month-to-month basis when you actually want to watch a specific show is worth the effort. Running a bi-annual review of your bank statements catches hundreds of dollars in forgotten micro-transactions, keeping your core cash reserves strictly dedicated to services you actively use and genuinely enjoy.
💡 Tip: Set calendar reminders to cancel trial subscriptions the moment you sign up.
Vacation Booking Strategy
Peak Season Packages
- Fixed holiday travel dates with 2x airfare markup
- Third-party tour agent booking surcharges
- Crowded venues, long lines, and packed resorts
- Rigid non-refundable cancellation penalties
Shoulder Season Freedom
- Flexible weekday departures at standard pricing
- Direct resort booking for complimentary room upgrades
- Relaxed cultural touring with zero crowds
- Half the total travel expenditure for luxury stays
7. Peak Season Travel Packages Waste Retiree Schedule Flexibility
I once spent $4,800 on a July package tour across northern Italy, only to discover that the exact same boutique hotel room and rail pass dropped to $2,150 by late September.
The common trap after leaving the workforce is sticking to old holiday schedules out of pure habit. Peak summer dates and holiday weeks easily double the cost of long-haul flights, resort suites, and rental cars. You end up paying thousands in calendar markups simply to stand in packed lines and deal with overworked resort staff.
Calendar flexibility cuts that overhead instantly.
Pre-packaged third-party tours charge huge booking fees for ordinary logistics that take twenty minutes to arrange on your own. Reserving rooms directly with properties during shoulder months like May or October cuts trip expenses in half while providing room upgrades and loyalty perks. You get quiet museums and attentive restaurant service at baseline rates.
Check your upcoming travel plans this afternoon, cancel high-markup package tours, and rebook directly during off-peak dates.
8. Extended Retail Warranties Duplicate Protections You Already Have
Decline the store protection plan the next time a cashier or checkout screen prompts you for an extra $75 on a new appliance.
Point-of-sale service contracts carry notoriously low claim payouts and pages of fine-print exclusions that make reimbursement a headache. Most major credit cards already add an extra year of complimentary warranty coverage automatically when you charge the purchase. Paying for a separate retail policy buys coverage you already own.
Keep your money in your liquid cash reserves to self-insure small repairs, reserving insurance payouts strictly for catastrophic risks.
💡 Tip: Review your primary credit card guide to benefits to confirm built-in purchase protection limits.
High-Fee Active Funds — At a Glance
💸 Active Expense Ratio
0.50% – 1.00%
📊 Broad Index Ratio
0.03% – 0.10%
⏳ 20-Yr Fee Drag
Up to 15% Principal
🛡️ Fiduciary Review
Annual Check
The Index Advantage
Shifting from a 0.85% active fee to a 0.05% broad market index preserves thousands in annual compounding yield.
Financial Services and Transaction Traps
The financial services industry is full of high-margin products designed to extract recurring tolls from substantial account balances. Retaining your wealth requires stripping out unnecessary intermediaries, promotional credit schemes, and speculative trades.
Keep your investment core simple, transparent, and low-cost.
9. High-Fee Active Funds Drag Down Long-Term Yields
A 0.75% difference in annual fund fees looks harmless on a monthly statement, but over a 20-year retirement on a $1,000,000 portfolio, that gap consumes well over $150,000 in capital.
Actively managed mutual funds routinely carry expense ratios from 0.50% to 1.00%, while broad index funds track whole markets for 0.03% to 0.10%. That internal management fee is deducted daily from your asset base, reducing gross dividend compounding and shrinking your total returns whether the manager outperforms the market or not.
Every fraction of a percent drains long-term principal.
Set up your portfolio to run on low-cost broad-market index funds and index exchange-traded funds, which charge baseline fractions of a percent. Direct your brokerage platform to automatically reinvest all quarterly dividend yields, and leave the core allocation untouched. This automated structure eliminates unnecessary management friction and extends the safe operational runway of your liquid principal.
Download the prospectus sheets for your primary funds this afternoon, or have a fee-only fiduciary audit your holdings, to strip out high internal expense ratios for good.
🛡️ Four Steps to Prune Portfolio Drag
Download Fund Prospectuses
Locate the exact expense ratio for every mutual fund and ETF held in your accounts.
Flag Active Management Fees
Identify any holding carrying an annual expense ratio higher than 0.20%.
Map Low-Cost Equivalents
Select broad-market passive index funds charging 0.03% to 0.10% in the same asset class.
Execute Tax-Smart Rebalancing
Rebalance inside retirement accounts first to eliminate fees without generating capital gains taxes.
10. Store Credit Financing Creates Needless High-Interest Debt
Stop financing major retail purchases at store checkout counters, even when a retailer offers zero percent promotional financing for twelve, eighteen, or twenty-four months on household goods.
While eliminating fund management fees preserves your investment returns, retail financing introduces an immediate threat to your monthly cash reserves. These retailer contracts frequently carry deferred-interest clauses. If you leave even ten dollars unpaid when the promotional term expires, the lender retroactively calculates interest above 25% APR on the entire original purchase amount.
Deferred interest turns minor oversights into expensive debt.
Tracking four or five store financing plans, separate online payment portals, and shifting promotional deadlines adds needless administrative friction to your routine. Retirement should simplify your financial life. Juggling conditional terms and grace periods turns basic shopping into ongoing balance-sheet risks that require continuous monitoring just to avoid sudden, retroactive interest charges.
Simplicity protects your cash far better than promotional gimmicks.
You do not have to revamp everything at once; start small by declining the next retail financing pitch on a single $500 home purchase. Paying cash for that one transaction breaks the store-credit habit cleanly. That modest move establishes a reliable boundary that keeps your everyday spending tied directly to actual cash on hand.
Sticking to direct cash allocations or a single rewards credit card cleared in full every billing cycle protects your credit score and insulates your retirement principal from the traps hidden inside retail financing agreements.
Paying cash upfront keeps your core capital unencumbered and secure.
⚠️ COMMON MISTAKE
The Deferred Interest Trap
Never assume zero-percent store financing is harmless free money. Missing the final payoff deadline by a single day often triggers retroactive interest across the entire initial purchase price at rates exceeding 25% APR.
11. Speculative Investment Hype Gambles With Core Retirement Capital
I watched a retired colleague lose $50,000 on speculative cryptocurrency and volatile stock options during their first year living without a steady corporate paycheck.
Retirees lack the multi-decade earning horizon needed to recover from deep drawdowns, making capital stability and predictable real yield the top priority. Implement a simple two-bucket system: allocate your core principal entirely to transparent, liquid index funds and cash reserves, while restricting unvetted private placements or speculative gambles to zero or an absolute negligible fraction.
Reliable compounding in transparent assets preserves your lifetime wealth.
💡 Tip: Keep speculative or experimental investments completely quarantined from your primary retirement distribution accounts.
Top Leaks to Eliminate First
Ranked by total capital impact on multi-decade retirement principal preservation.
Frequently Asked Questions
Should I sell my large family home immediately upon retiring?
Not necessarily in your first month. Give yourself six to twelve months to settle into a retirement routine, evaluate your true square-footage usage, and calculate local property tax savings before listing the property.
Is it safe to cancel a whole life policy if I have had it for decades?
If you are self-insured with sufficient retirement assets, surrendering the policy or rolling the cash value via a 1035 exchange into an annuity can make sense. Review your policy with a fee-only fiduciary first to check for surrender charges or tax implications.
How much does switching to generic store brands actually save over time?
A household spending $800 monthly on groceries can save $160 to $240 per month by switching non-durable goods, cleaning supplies, and pantry dry goods to store brands, totaling nearly $3,000 in annual savings.
What should I do if I currently own an unwanted timeshare?
Stop paying for optional upgrades, contact the resort developer directly to inquire about formal deed-back surrender programs, and avoid upfront-fee timeshare exit scams that overpromise results.
Trim Unnecessary Retirement Overhead in Thirty Days
Preserving lifetime wealth across thirty non-working years comes down to stripping away heavy asset overhead, unneeded retail markups, and excessive management fees before they compound against you. Pull your bank and brokerage statements from the past three months and tag every recurring line item matching these eleven categories.
Pick the single largest structural leak on that list and cancel or renegotiate it this weekend. Stopping your biggest balance-sheet drain first provides the fastest cash-flow win and keeps your principal secure.
Review Your Fund Expense Ratios Today
Open your brokerage portal, locate the fee disclosures on your top holdings, and confirm you are not losing yield to high active management fees.