
Half a million dollars, held honestly, pays somewhere between $17,500 and $22,500 a year before a dollar of it is taxed. The spread is $5,000, and it comes down to the vehicle, not to how clever you are about picking it.
You already know the number that got you here. Four percent of $500,000 is $20,000 a year, $1,667 a month, the figure every retirement piece prints, the reason the math feels finished before it starts.
Quoted four ways, the same half million pays $17,500, $20,000, $20,000 or $22,500, and each figure carries its own catch: a rate that resets, a term that locks, a balance that can fall, a draw that can outlive the money. None of those catches show up in the quoted yield, and fees, tax and inflation have not taken their share yet.
So the highest rate is not the answer. Match the vehicle's term to the date the money is actually spent, and the four stop competing.
By the end you can name what each setup pays a month, name what it quietly risks, and walk into any meeting with the fee question and last year's spending already written down.
The honest range is a five-thousand-dollar spread, and which end of it is right for you depends on your calendar, not on the rate.
Quick Tips Before You Start
Name the date first
Write down the year each big expense lands in before you compare a single yield.
Get the all-in fee in writing
Advisory fee plus fund expense ratios plus platform charges — the advisory fee alone is not the number.
Assume the rate resets
Anything paying today's cash rate pays something else at renewal, so budget for the lower version.
Test the bad year
Ask what the plan looks like after the balance drops 20% — if the answer is 'sell', it's too tight.
Split by horizon, not by mood
Money spent in two years does not belong in anything that can fall 20% before then.
The four scenarios, run honestly
Four ways to hold the same half million, ordered from the shortest commitment to the longest horizon. Each one below is the arithmetic first, then the thing it quietly takes back.
Read them as a menu of trade-offs, not a ranking. The highest first-year cheque is not the best plan, and the lowest one is not the worst — the balance is what matters.
1. Cash pays the most today, the least later
Parking half a million in cash feels safe because the number on the statement never moves. That fear, that if you touch it you will lose it, is worth naming first: nothing here asks you to move a dollar you need next year.
Run the rate: $500,000 earning 4.00% produces $20,000 a year, which is $1,667 landing in the account every month. The statement still reads $500,000 at the end of it. No shares sold, no principal spent, nothing to replace.
That $20,000 is the biggest cheque on the board you can collect without tying the money up. The only setup that pays more needs you to surrender access for a set term to get it.
The catch is that the rate is a rental, renewed each time the account comes up for repricing at whatever the market happens to be offering that month. Renew at 3.00% and the $20,000 becomes $15,000. Renew at 1.50% and it is $7,500. The owner did nothing wrong and nothing changed except the renewal date.
So the balance is intact in name only. It does not shrink while the buying power behind it does, and a cheque of the same size fifteen years from now is the same dollars but not the same money. That gap is the hidden cost of the safest-looking setup.
This is where cash earns its place, though, and it is a real place: money already spoken for. A house deposit, a bill with a known date on it, the bridge between stopping work and the first pension cheque.
The action is to draw the line yourself. List every dollar you will spend inside two to three years, total it, and hold exactly that much in cash. Everything past that line does not belong here.
Write the renewal date on your calendar now. That is the one day the income can move without you touching a thing.
💡 Tip: Keep cash in an account you can reach in one business day — not a CD — if the point of holding it is access.
| Scenario | Assumed yield | Income a year | Income a month | Main risk | Best for |
|---|---|---|---|---|---|
| Cash | 4.00% | $20,000 | $1,667 | Rate resets at renewal | Money needed in 2–3 years |
| Treasury ladder | 4.50% blended | $22,500 | $1,875 | Locked term, early-sale loss | Dated expenses with a known date |
| Dividend portfolio | 3.50% | $17,500 | $1,462 | A bad year can cut ~$100,000 | 10+ year horizon, income can grow |
| 4% draw | 4.00% of balance | $20,000 | $1,667 | Sequence risk in year one | 30-year retirement with flexibility |
2. A Treasury ladder locks the rate, not growth
Four and a half percent across the rungs of a Treasury ladder pays $22,500 a year on $500,000-$1,875 a month, the highest of the four setups – and the reason T-bills, bond funds and CD ladders differ is that a payment that can move against you at every renewal is a payment you can't plan a life around.
You build it in equal amounts maturing one per year, and as each rung comes due you reinvest it at whatever rate the market offers that month. One rung reprices annually instead of the whole balance resetting at once, which is how a known payment gets matched to a known date. A roof, tuition due in four years, the gap years before you claim Social Security – where the amount and the date are both settled and growth isn't the point.
The rate holds only as long as each rung lasts, and full principal comes back only if you hold every rung to term. Sell one early to raise cash and you can take a loss on it. Ladder a slab today rather than waiting for a better rate, because the rungs you buy now are the ones already maturing when you need them.
💡 PRO TIP
One sentence that settles most of it
Match the term of the money to the term of the need — then the only question left is the fee.
3. Dividends pay less but can raise the payout
There's a specific unease that comes with watching a stock portfolio fall while you're counting on it for income: the feeling that you should sell now, before it gets worse, and just take the certainty. That instinct is not wrong. It's just early, and the difference between a ten-year horizon and a two-year one decides whether it applies at all.
A Treasury ladder pins a payment down and caps it. When the money isn't needed for a decade, a payment that grows matters more than one that's merely fixed, because a flat cheque keeps shrinking in what it buys, and locked rungs can't stretch.
Dividends start lower. At a 3.50% yield, $500,000 pays $17,500 a year, $1,462 a month – roughly $2,500 less than cash and $5,000 less than the ladder. And it isn't a contract: company boards declare dividends and can cut or suspend them, so that figure is a current rate, not a promise.
Here's the bad year in plain numbers. A rough market takes about $100,000 off the balance, $500,000 down to roughly $400,000, while the income is still expected to arrive. The holder has to keep collecting through the drop instead of selling into it, which is the whole test and the whole cost.
So it's fine to do less than the full $500,000. Move a quarter of it into diversified dividend payers and leave the rest parked where you can sleep. A ten-year-plus horizon is what this asks for, in exchange for a payment that has historically been raised over time and principal that has grown.
💡 Tip: Judge a dividend portfolio on the income it paid through 2008–09, not on last year's yield.
⚠️ COMMON MISTAKE
Comparing gross yields is the classic error
A 4.50% ladder and a 4.50% dividend fund are not the same 4.50%. One is contractually paid and returns principal at maturity; the other can be cut and can fall 20% in a year. Compare the net after tax, after fees, and after a bad-year test — never the headline rate.
4. A 4% draw pays $20,000 with sequence risk
The belief worth retiring is that 4% is a number you set and forget, a rate you can pull off the shelf in any market. The percentage isn't the machine that kills a plan. The year the money started does the killing.
Sell a slice of a $500,000 portfolio at 4% and the first year hands you $20,000, or about $1,667 arriving in the account each month. Nothing pays out a coupon here; you create the cheque by selling, unlike dividend income. Now imagine a collapsed first year: a 20% drop leaves $400,000, and that same $20,000 withdrawal is suddenly 5% of the pot. And you sold the shares to fund it at the bottom, so they are gone at the price you never wanted.
The identical 20% tumble arrives in a different order in year twelve. By then a decade of growth has built a larger base, so the withdrawal is a smaller bite and the shares sold are the ones you didn't need. Averages hide this completely. The order of returns is what determines the outcome, and it matters more than the yield.
That is where a professional earns the fee, because judging whether your mix survives a bad first year needs numbers nobody has but you. Sit down with a fee-only fiduciary who will model a real crash in years one, two and three against your actual spending. Ask what happens if the first two years are negative and you still need $20,000 each. Skip the planner who says don't worry about it.
The 4% Draw — At a Glance
💵 Starting draw
$20,000 / yr
📆 Monthly
$1,667
📉 After a 20% first-year drop
$400,000 balance
🔁 New withdrawal rate
5.0%
⏳ Designed for
~30 years
🛡️ Guaranteed by
Nobody
The flexibility test
If you cannot skip or shrink a withdrawal in a bad year, plan the draw closer to 3%.
What quietly eats the income
Three drags hit all four setups and none of them show up in the quoted yield: fees, taxes, and inflation.
Skip them and the comparison is fiction. The best-paying scenario can lose to the worst-paying one once these are subtracted.
5. A 1% fee takes $5,000 before you spend
The fee is the one bill you agree to in a meeting and pay every year without seeing an invoice. Our $500,000 quote at 4% delivers $20,000 gross. A 1% all-in charge takes $5,000 of it. One quarter of the income is gone before you spend anything, roughly three months of the monthly cheque.
I've sat across from advisors and learned to ask for the all-in number, not the advisory line. Fund expense ratios, trading costs, platform and custody charges, all in. At 0.25% the same strategy is $1,250, and the gap is $3,750 a year that compounds on the whole $500,000 with no change to a single investment decision.
6. Taxes land differently on each scenario
It depends on two things no article or advisor can know for you: the bracket and state you live in, and the kind of account holding the money. Get one wrong and you misjudge the whole payout.
The mistake is comparing rough yields. A cash interest payment, a qualified dividend check, a long-term capital gain and a withdrawal from a traditional IRA are four different tax events. Eighteen thousand gross can leave you very unequal net amounts depending on which bucket the money came from.
Before you compare yields, settle which account holds the $500,000, because that single choice can weigh more than which vehicle you pick. And once this is your main income, nobody automatically withholds for you. You may need quarterly estimated payments, and Form 1040-ES is how you send them. Publication 550 spells out what counts as what.
No honest article gives you a rate. Not $20,000, not any of them, because the gross quote is not the take-home. The real figure comes from one conversation about your situation, and you should ask a CPA to run that before you touch anything. A good accountant can mean $1,000 to $3,000 in a single tax year.
💡 Tip: Ask a CPA one question first: 'Which account should this money come out of first?' It's cheaper than restructuring later.
7. Inflation turns a fixed $20,000 into a pay cut
A relative showed me her savings statement the year she retired, and the interest line was the same number it had been when she first opened the account. She read it as stability. What she was actually looking at was a cheque that would buy less every single year it arrived.
Run the arithmetic forward. If prices rise about 3% a year, the buying power of a fixed $20,000 is cut in half in roughly 24 years, so the same cheque that covers a full year of expenses now covers about what $10,000 covers today. Even the best first-year figure of the four is the high-water mark of the whole plan: $1,667 a month is worth about $1,240 in today's money after ten years and roughly $920 after twenty.
You have only two levers. Hold some growth assets so the payment can be raised as prices climb, or raise the withdrawal on purpose and accept that the principal will not last as long. And remember these figures leave Social Security out entirely; it adjusts for inflation, and it is the piece of retirement income that does.
The Income Drags in Numbers
Four figures that decide what actually reaches your account
Inflation assumption of 3% is illustrative, not a forecast.
Choosing the setup that fits
The four scenarios stop competing once you stop asking which pays most and start asking which dollar is spent when.
Two moves turn four quoted yields into one decision: split by horizon, then check the result against real spending.
8. Split the $500,000 by when you need it
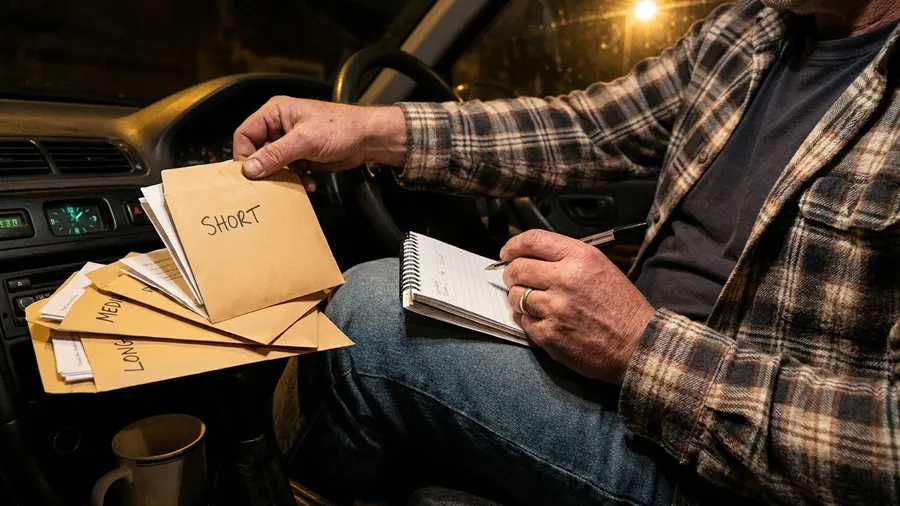
Stop trying to pick the one right vehicle. Divide the balance by the date each dollar is actually needed.
$19,500 a year, or $1,625 a month, arriving from three directions at once.
Now look at where that total sits. It falls below the $22,500 the ladder alone would throw off, and sits well above the $17,500 the dividend portfolio pays. That gap is not a mistake. It is the price of the certainty the cash and the ladder buy, and you pay it in yield.
The logic holding the whole thing together is simple to state and easy to break: the dollars spent in two years should never depend on the stock market, and the dollars spent in twenty should never sit in a savings account losing ground to prices. Match the money's term to the need's term.
Which brings the honest downside. No single vehicle handles every risk at once. Cash gets eaten by rising prices, dividends get cut when markets fall, and a ladder runs out of reach when the horizon stretches long enough. You are giving up the top yield on purpose because no one has told you yet what the next two years will cost.
The maintenance bills an afternoon a year. Rebalance once, and the only question is which bucket is short.
After a good market year, skim the growth bucket to refill cash. After a bad one, move cash back into growth and let a down market recover. Skip that step and the buckets drift; the careful date-matching quietly stops being true without a single statement showing the change.
It is more paperwork than a single 4% draw. It is also the version you can sleep on in a year when the market falls 20% and the roof still needs replacing.
All-In on One Vehicle vs. Split by Horizon
All-in on one
- Highest single first-year yield (ladder: $22,500)
- One rate or one market decides everything
- No liquidity if a big bill lands early
- Simplest to run, hardest to fix
Split by horizon
- Blended $19,500 a year, $1,625 a month
- Dated money never touches the market
- Growth money can be left alone to compound
- Needs one rebalancing pass a year
9. Check the income against your real spending
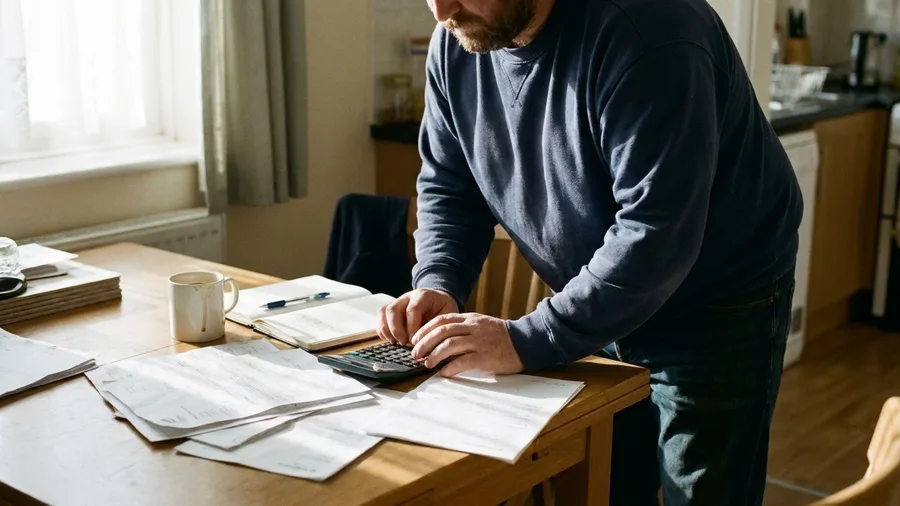
Total last year's real spending from your bank and card statements, then subtract Social Security and any pension.
That leftover is the gap the $500,000 has to cover, and it is the only figure that decides anything. Across the four vehicles the income runs $1,462 to $1,875 a month, before tax — $17,500 to $22,500 a year. A split lands at $1,625.
Start small: pull one month of statements, not the whole year. Even that tells you whether the gap is closer to $1,500 or $3,000 — and that one comparison does more than any yield table.
💡 Tip: If the money sits mostly in a traditional IRA, settle the account structure with a tax adviser before comparing any yields.
Is Your Setup Ready? Score It
Two or more fails: fix the cash bucket and the fee before choosing anything else.
Frequently Asked Questions
Is $20,000 a year a realistic income from $500,000?
Yes, at today's rates — roughly $1,667 a month before tax, and that figure is in the middle of the four scenarios shown. What it is not is guaranteed. Cash rates reset, dividends can be cut, and a 4% draw depends on markets cooperating. Treat $17,500 to $22,500 as the honest range, then plan your spending against the low end.
Should I take the highest yield available?
Only if you can live without the money for the term that yield requires. The ladder's 4.50% pays the most because it locks your cash up; the cash account's 4.00% pays less because it doesn't. The right answer is almost always a split, not one winner.
How much should I keep in cash versus invested?
Fund the cash bucket with everything you will spend in the next two to three years — that is the money that must not fall 20% before you need it. Everything beyond five years can be invested for growth. Rebalance once a year so the buckets don't drift.
What will I actually keep after tax?
It depends on which account holds the money, your bracket, and your state — which is why no single number is quoted here. Cash interest, qualified dividends, long-term capital gains and IRA withdrawals are taxed on different rules. Ask a CPA which account should fund the first dollars of income; it can move the net by thousands a year.
Can I just take 4% a year and stop worrying?
You can use 4% as a spending guide, but it is not a promise from any institution. A 20% drop in year one leaves $400,000 supporting the same $20,000, which is now a 5% withdrawal — that is the sequence risk. If you can skip or shrink a withdrawal in a bad year, 4% is workable. If not, start closer to 3%.
Does $500,000 plus Social Security cover retirement?
For a lot of households, the $17,500 to $22,500 from the portfolio plus Social Security does the job — but only your actual spending number can answer it. Add up last year's real expenses, subtract the Social Security cheque, and see what gap remains. If the gap is bigger than the portfolio can pay, the fix is spending or work, not a higher-yielding fund.
Which of the four $500,000 setups fits your clock
The verdict runs on dates. Money you need within two years belongs in cash at 4.00%, $20,000 a year and $1,667 a month, unlocked whenever, with the rate reset as the price of that access. Over ten years, a Treasury ladder if the date is known, at $22,500 a year and $1,875 a month with principal back at maturity, or the dividend portfolio at $17,500 and $1,462 a month if the pot is meant to grow and can absorb a $100,000 year. Drawn on for thirty years, the 4% draw fits, $20,000 a year with room to skip or shrink a withdrawal when a year turns bad.
The $20,000 that pulled you in is real and it exists. It is also one year-one figure from one of four vehicles, before the $5,000 fee, the tax bill and 3% inflation have taken their share.
Before you choose anything, write down last year's actual spending and the date each dollar is needed, and get the all-in fee in writing. Those two pages decide more than any yield table. The money does not need a better rate. It needs a date on every dollar and the arithmetic done straight against the spending it has to cover, starting with the four percent you walked in with and what it quietly leaves out.