I thought an $850,000 balance in my 401(k) meant I was done working forever, but trusting the math alone is a massive miscalculation you can easily avoid.
Standing at my retirement party at age 62 holding a slice of sheet cake, four decades of employment felt permanently behind me. Eleven months later, I signed a contract to return to my industry for twenty hours a week.
The logic of a safe withdrawal rate cannot account for the physical panic of spending without earning, or how fast your professional identity vanishes.
Reviewing these thirteen blind spots separates the financial daydream from daily reality. Quitting your career is a messy shift where plugging cash leaks and finding daily purpose often makes part-time work the perfect lifeline.
Quick Tips Before You Start
Test the Budget
Live on your projected withdrawal amount for three months before quitting.
Price the Premium
Pull exact ACA healthcare quotes instead of estimating the cost.
Keep the Network
Maintain one active professional contact just in case you pivot back.
The Money Surprises
The math changes the minute the paychecks stop.
I walked out the door with a plan to spend exactly $4,500 a month. It took less than half a year to blow that entirely, and the leaks came from places I never budgeted for.
0. Free Time Is Surprisingly Expensive to Fill
If your checking account is draining faster now than it did while you were working full-time, you are not failing at retirement. You just gained forty extra hours a week to fill.
I budgeted exactly $4,500 for monthly expenses, assuming dropping the daily commute and the dry cleaning would automatically shrink my outflow. But a financial plan built for the weekend completely fails when every single day operates like a Saturday. Occasional Sunday golf rounds quietly turned into Tuesday morning tee times, paired with museum trips and restaurant lunches.
By month six, my actual expenses averaged $5,800.
You cannot willpower your way out of a suddenly empty calendar. You have to take the decision out of your hands by automating a strict weekly allowance into a separate checking account.
Set your bank app to transfer a fixed amount every Monday morning for leisure spending, and leave your main debit card in a desk drawer. When the transfer runs dry on Thursday, you find free entertainment, stopping those cheap hobbies from snowballing into massive monthly line items.
The $5,800 Reality — At a Glance
🎯 Target Budget
$4,500/month
📈 Actual Spend
$5,800/month
⛳ Biggest Leak
Tuesday golf rounds
🔒 The Fix
Strict weekly cash
0. Pre-Medicare Health Insurance Premiums Are Brutal
That daily spending creep from trying to fill my empty afternoons just piled onto a much deeper panic hitting my bank account every month. Walking away from my desk at 62 meant abandoning the company benefits package a full 36 months before I could qualify for government coverage.
The cheapest open-market medical policy I could find ran me $850.
Handing over twenty percent of my planned $4,500 limit before buying groceries destroyed the fantasy that living costs plummet without a commute. Spend just five minutes pricing a policy on your state exchange today. Finding that one real number early prevents a massive financial shock later.
⚠️ COMMON MISTAKE
The COBRA Trap
Do not assume COBRA will cover you cheaply for eighteen months. It charges the full premium plus an administrative fee, often costing double your active employee rate.
0. Watching the Portfolio Balance Drop Is Terrifying
The standard retirement advice assumes that once you hit your target balance, the math takes over and you are perfectly secure. The spreadsheet, however, does not have a nervous system. Paying those brutal healthcare premiums directly out of a stagnant account triggered a visceral anxiety I never anticipated.
The shift from earner to pure spender feels completely unnatural.
For four decades, my entire identity was built on accumulating assets. That $850,000 balance represented total safety while I was adding to it every two weeks, but selling shares to fund that first month broke a forty-year habit. Turning on the withdrawal tap felt exactly like watching a timer count down to zero.
A four percent safe withdrawal rate makes perfect logical sense on paper. That logic completely evaporates when a deeply red market day coincides with a massive $5,800 monthly cash drain.
Selling off shares while the market is down locks in those losses permanently. If you do not stop the bleeding immediately early in retirement, the mathematical damage compounds against your portfolio for the rest of your life.
The Phase Shift
Accumulation Phase
- Market dips are buying opportunities
- Paychecks cover daily living
- Balance represents future security
Withdrawal Phase
- Market dips directly threaten longevity
- Portfolio must fund daily living
- Balance represents a ticking clock
0. Inflation Makes a Fixed Income Feel Fragile
Watching my nest egg shrink was terrifying enough, but seeing my standard weekly grocery run creep from $140 to $165 made the math feel impossible. During my career, I simply worked through price hikes, knowing a three percent annual merit raise or a spring bonus would eventually wash them out.
A fixed withdrawal limit cannot defend against surging gas bills.
That lack of earning power directly threatened my longevity plan. You do not have to perfectly inflation-proof your portfolio today. Finding a small side income lets you stop trying to out-invest the economy.
The Psychological Void
The money stress was only half the battle.
The other half was waking up on a Wednesday morning and realizing nobody on earth needed me to be anywhere. The psychological void of retirement is rarely discussed, but it is deeply destabilizing.
0. Your Professional Identity Evaporates Overnight
Once the financial anxiety of losing a regular paycheck settled into a familiar hum, a much deeper void opened up on my suddenly blank daily calendar.
On my last Friday at the office, I was still a middle manager making decisions that materially affected a business. I had an entire department waiting on my budget approvals, tapping me for institutional knowledge, and looking directly at me when a client crisis blew up at four in the afternoon.
That title provided a massive scaffolding for my own self-worth.
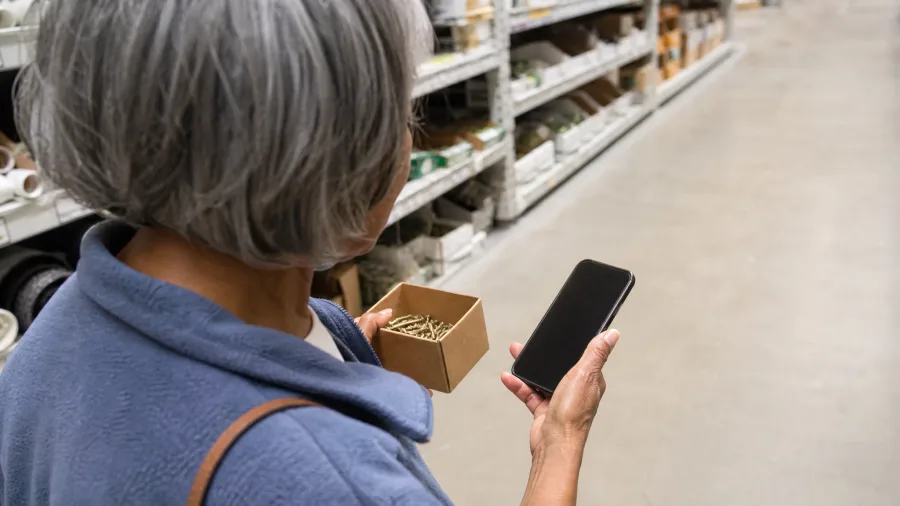
Then Monday morning arrived, and that entire operating structure vanished without a sound. By month four, the transition was complete. I went from being the person holding the answers to just another 62-year-old guy standing in line at the hardware store at ten in the morning on a Wednesday, buying a $14 box of wood screws just to kill an hour.
The starkest realization hit a few weeks later. I texted a former colleague about a major industry shift that would have upended our quarter, expecting our usual rapid-fire strategic analysis.
I got a simple thumbs-up reaction two full days later. It made it painfully clear that I was officially outside their daily orbit, and my specialized expertise was no longer relevant to their world.
You spend forty years pouring your energy into building up a professional identity, assuming you will be incredibly relieved to finally put that heavy coat down. Nobody prepares you for the absolute silence of not being needed.
It all vanishes completely on day one.
The Identity Trap
0. The Endless Vacation Gets Boring by Month Three
Sixty days is exactly how long it takes for a permanently empty calendar to lose its appeal. Without a department needing my input every morning, ignoring the alarm clock stopped feeling like a victory.
Taking a short trip only feels incredible because it interrupts a grueling professional routine. When that interruption becomes your permanent baseline, the total absence of structure turns suffocating. By the third month, taking a book out to the patio stopped feeling like an escape and morphed into a tedious daily obligation.
An existence built entirely around relaxing generates zero forward momentum.
To regain that sense of accomplishment, you have to manufacture your own friction using a simple three-zone calendar system. I divide my week into distinct buckets. Two mornings are dedicated to focused consulting work, two afternoons go toward physical projects, and the remaining hours are strictly protected for actual relaxation.
You have to earn your downtime for it to feel valuable again. Grouping those demanding tasks into dedicated weekly windows gives the schedule its contrast back, making a Saturday actually feel like a Saturday.
Best For
0. You and Your Spouse Displace Each Other
Map out separate physical zones in your house before your first week of permanent downtime turns into a turf war. You have to actively rebuild your logistical boundaries from scratch for a twenty-four-hour reality.
For three decades, our marriage operated smoothly around a massive structural pillar: I vanished at eight in the morning and did not reappear until six at night. When my creeping boredom drove me to suddenly tear apart the kitchen pantry on a random Thursday, it shattered a daytime ecosystem my wife had perfected without me.
We literally negotiated separate daylight territories just to preserve our sanity.
⏳ The 11-Month Arc of Un-Retiring
Month 1-2
The honeymoon phase feels like a long, well-earned vacation.
Month 3-5
The budget starts bleeding from excessive weekday hobbies.
Month 6-8
The psychological void sets in as social isolation becomes obvious.
Month 9-10
Financial anxiety peaks, prompting the search for consulting work.
Month 11
Signing the part-time contract restores balance and cash flow.
0. Weekday Social Isolation Is Very Real
The mistake we make is assuming our friends will be available.
After my wife and I negotiated our separate daylight zones to stop driving each other crazy, I naturally went looking for companionship outside the house to fill the gap. That is when I learned the hard way that the social network of adulthood is inextricably tied to the Monday-through-Friday corporate calendar.
A Tuesday afternoon at two o'clock is incredibly quiet when you are the only one not working in your neighborhood, and the silence gets heavy fast when you have nowhere to be.
Every former peer I used to grab lunch with was either logged onto a mandatory video call, fighting fires in a budget meeting, or sitting at a desk. I actively tried to find people my exact age who were also retired and looking to fill a Wednesday afternoon. That search yielded almost zero results.
Most sixty-two-year-olds are still heavily invested in the daily grind.
Having absolute freedom over my calendar meant absolutely nothing when there was simply no one around to share those wide open daylight hours with, leaving me sitting alone on the porch.
The common error is thinking you are retiring into a ready-made community of leisure, when you are actually dropping out of the rigid schedule that dictates all adult socialization.
You are suddenly living on a timeline completely disconnected from your peers. Returning to part-time consulting for twenty hours a week fixed this isolation instantly. If you plan to leave early, you have to actively build a weekday network of other retirees long before you hand in your final notice.
💡 PRO TIP
Find the Weekday Crew
Look for volunteer organizations or civic boards that specifically meet on weekday mornings. This immediately filters for people who are on your exact schedule.
0. Your Mental Sharpness Starts to Fade
That absolute isolation I just mentioned quickly translated into a sluggishness I could physically feel.
For decades, my mind thrived on tension – untangling a vendor dispute at 9 AM, forecasting a department's $1.2 million quarterly spend by lunch, and mediating a staff turf war before heading home. By month five, the heaviest mental lifting I did was figuring out whether to hit the pharmacy before or after the hardware store.
An unused brain simply goes soft. If you are mapping out your own exit date, talk to a transition coach or therapist to plan exactly how you will replace that daily cognitive load, because crosswords are not enough.
The Reality of Going Back
Getting back in is a completely different game.
Deciding to return to the workforce was a massive relief, but it required completely abandoning the senior status I retired with. The pivot back is about cash flow and purpose, not climbing.
0. Re-Entering the Workforce Takes Extreme Humility
Going back to work means checking your former title at the door. That combination of cognitive rust and a bleeding savings account pushed me to pitch for contracts, where I quickly discovered my past authority carried zero weight.
Pitching my services meant sitting across from hiring managers who were fifteen years younger than me. Less than a year out of the game was somehow long enough for the corporate software suite to change and the industry acronyms to mutate. I felt completely out of touch in the exact sector where I used to approve the annual budgets.
The ego hit is massive.
The trap is believing your previous senior rank entitles you to immediate respect in a new arrangement. You have to trade that pride for practicality, accepting a lone-wolf role with no direct reports just to secure the twenty hours a week you actually want. You step down a tier so you can control your time.
New belief: the paycheck and the schedule matter more than the prestige. Update your resume this afternoon to highlight specific project executions rather than the sheer number of people you used to manage.
0. Part-Time Consulting Requires Unpaid Hustle
Staring at my first signed contract for twenty hours of weekly project work, I thought the hardest part of re-entry was over. I had swallowed my pride, landed the gig, and secured what looked like the perfect half-speed version of my old career, safely replacing the income I was burning.
The math on the page lied to me again.
The agreement only paid for the time I spent actively fixing a client's problem. It completely ignored the Tuesday mornings I burned drafting custom proposals, the Wednesday afternoons spent chasing down late payments, and the administrative headache of setting up my own tax withholding.
You are not just the consultant anymore. You are the marketing department, the billing clerk, the IT support desk, and the lead generator all at once.
That gap between the hours you actually bill and the unbilled hours you spend maintaining the practice shatters the illusion of a breezy half-time job. A part-time schedule still demands a full-time commitment to logistics.
This is why you must audit your actual time after the first ninety days of consulting. Track every single minute you spend on the business that does not generate an invoice. You need to measure three specific things: proposal writing time, bookkeeping hours, and the unpaid energy spent networking for your next contract before the current one ends.
Put a dollar value on that administrative drag. If you are regularly working thirty-five hours just to bill for your contracted twenty, your hourly rate is too low or your intake process is broken.
Run the real numbers and adjust your fee to compensate.
0. Working Because You Want to Changes Everything
Going back to work can feel like admitting defeat, but you haven't failed. Yes, managing contracts means eating some unbilled hours, but re-entering the workforce on your own terms changes everything.
Bringing in $3,500 every four weeks patched the hole between my actual $5,800 monthly burn rate and what the portfolio could safely generate. Because my survival no longer rested on a permanent salary, the familiar dread of office politics evaporated. Knowing I could afford it, I simply walked away from a messy proposal in month two.
Earning your own keep replaces corporate dependence with absolute personal agency.
0. Delaying Social Security Becomes a Huge Relief
A $5,800 monthly outflow makes you consider terrible math. Before that new consulting check plugged the structural hole in my timeline, I was weeks away from claiming Social Security at 62 just to protect my 401(k).
That panic move locks in a permanently reduced payout for life.
Now, bringing in $3,500 a month acts as a bridge. It lets my investments recover and allows my benefits to grow untouched. Because the math on claiming depends entirely on your health and household, sit down with a fee-only planner to check your specific dates. Earning just enough to wait transforms early retirement from a countdown into a sustainable runway.
Frequently Asked Questions
Is it normal to feel depressed after retiring?
Yes, it is incredibly common. Losing the daily structure and social network of a career creates a psychological void that takes real effort to rebuild.
Should I work part-time in early retirement?
For many people, it is the safest move. It provides a financial bridge before Medicare and Social Security kick in, while offering much-needed daily purpose.
How much does ACA healthcare actually cost?
It depends heavily on your state and income level, but unsubsidized premiums for a couple in their early sixties can easily exceed $1,500 a month.
Is un-retiring considered a failure?
Not at all. It is a strategic pivot. Adjusting your plan when the math or the mindset isn't working is exactly what smart financial planning looks like.
Pivot Before You Panic
Un-retiring is never a failure of your original plan. It is a necessary pivot to bridge the gap between a spreadsheet and actual life.
Before handing in that final notice, calculate more than just what pays the bills. You have to figure out exactly what will demand your attention on a random Tuesday morning.
That guy eating sheet cake at 62 thought his contributing days were over, but he just needed to renegotiate the terms. Assuming the $850,000 balance meant I was completely done was the mistake; returning to work on my own schedule became the ultimate fix.
Review Your Health Premium First
Before you set a retirement date, scroll back up and run the math on your exact ACA coverage costs — it changes the entire timeline.