Can you date in your seventies or eighties without risking the home and savings you spent a lifetime building? Yes, but only if you discard the idea that late-life romance works like dating in your twenties.
I re-entered the dating scene at 75 after 48 years of marriage, holding a mortgage-free $420,000 home, a $650,000 retirement portfolio, and survivor pension benefits that young love never has to manage. Guarding those accumulated assets and family promises took learning the hard way.
Companionship after 70 requires hardening your legal and financial boundaries before opening your front door or sharing living expenses.
Setting those clear limits first is what keeps late-life love a genuine joy rather than a threat to your hard-earned independence.
Quick Tips Before You Start
Audit Pension Rules
Confirm survivor benefit and corporate pension clauses before ever discussing legal marriage.
Keep Separate Keys
Maintain separate primary residences to avoid accidental tenancy claims or blended estate conflicts.
Isolate Dining Out
Fund an isolated monthly entertainment envelope to keep social spending capped at $350.
Update Health Proxies
Confirm advance directives give visitation rights while leaving medical decisions to designated family.
Legal and Estate Protection
Late-life partnerships carry serious legal implications for your existing assets. When you have decades of accumulated property, survivor pensions, and adult heirs, romantic decisions can unintentionally trigger irreversible losses.
Establishing legal boundaries upfront prevents probate battles, tax penalties, and lost retirement checks.
1. Remarriage Can Threaten Survivor Benefits and Pensions
Pull your original pension paperwork out of the filing cabinet before you entertain any conversation about a legal wedding.
My own monthly income depends on two foundational sources: a Social Security survivor benefit and structured distributions from my $650,000 retirement portfolio. While federal rules allow you to retain Social Security survivor benefits if you remarry after age 60, private corporate pensions and military Survivor Benefit Plans frequently terminate payments the day you remarry.
Signing a marriage certificate can extinguish that income forever.
The trade-off is balancing traditional romantic symbols against your financial security. You might want the social recognition of formal marriage, but staying legal domestic partners is what keeps those critical monthly funds flowing. Forfeiting hundreds of dollars each month simply to hold a marriage license forces your retirement portfolio to work harder than it reasonably should.
Remaining unmarried allows you to build a shared daily life with someone new while keeping the survivor income that your late spouse spent decades working to provide.
Dig into the exact plan documents or schedule a brief phone call with your former employer's benefits department. You need to see the precise forfeiture clauses in writing before you take any next steps, because no romantic gesture is worth sacrificing the baseline monthly revenue that keeps your household solvent and independent.
Have this honest financial conversation before wedding rings or shared legal vows are ever discussed, so expectations remain grounded in the reality of your existing retirement cash flow.
Protect your income baseline first.
💡 Tip: Call your pension plan administrator to request written confirmation of their remarriage forfeiture rules.
2. Cohabitation Without a Contract Creates Estate Chaos
You do not have to choose between opening your home to someone you love and protecting the inheritance you promised to your children decades ago.
Safeguarding your monthly survivor income is only the first step; moving a partner into your house introduces significant real estate vulnerabilities. I hold sole ownership of a $420,000 mortgage-free home intended entirely for my heirs. Without formal paperwork, simply handing someone a front door key can grant legal tenancy rights that stall probate.
Living together informally invites expensive probate disputes.
I paid $4,200 for an estate planning update to construct a binding cohabitation agreement alongside a revocable trust. The contract states plainly that no equity or title transfers to my partner, and it establishes a strict 60-day move-out window if I die first. This single document protects my family from painful eviction proceedings.
Schedule time with an estate attorney to draft these terms before moving a single moving box into your house, making certain both your family and your partner have absolute legal clarity.
Estate Protection Hierarchy for Late-Life Dating
Order of legal safeguards before sharing living space
3. Separate Accounts Prevent Quiet Financial Creep
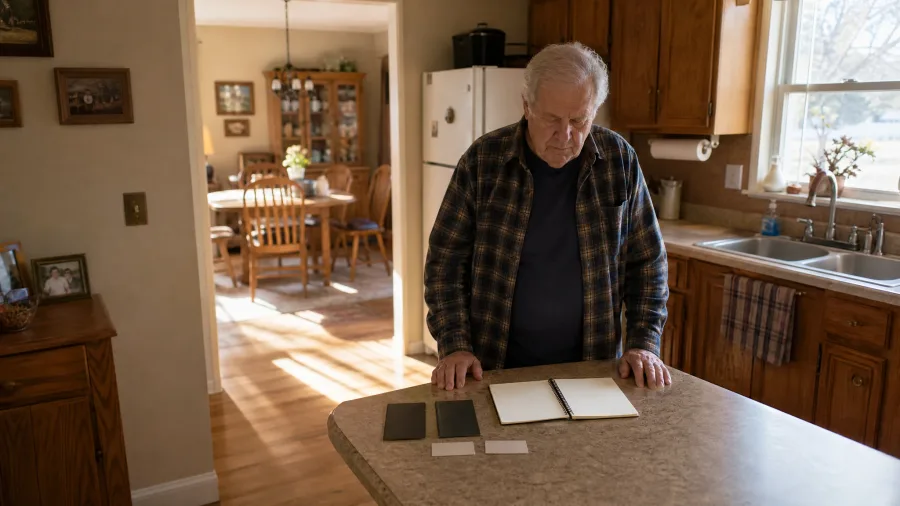
It feels ungenerous to look at a partner you care about and insist on keeping your bank accounts completely walled off from each other.
Once your real estate and property terms are locked down, daily living expenses become the next hazard. Commingling your primary checking account exposes your liquid savings to your partner's old tax liens, unpaid consumer debts, or sudden legal judgments. Adding them as an authorized user on your credit card creates joint liability that risks your credit score.
Shared banking creates quiet liabilities you never anticipated.
Remove the guesswork by setting up an automated three-account system. Keep your individual primary accounts completely separate, and open an isolated joint checking account dedicated solely to shared household costs. Set up an automatic monthly transfer where each of you deposits an equal amount, like $250 each, to pay for groceries, utilities, and casual dinners out together.
When the shared account runs dry, you stop spending until next month. This automated boundary shields your main cash balances from subsidizing someone else's lifestyle without requiring awkward budget arguments.
⚠️ COMMON MISTAKE
Avoid Adding Authorized Users on Credit Cards
Adding a new partner as an authorized card user makes you legally liable for their spending without giving you recourse to recover the funds.
4. Updated Healthcare Proxies Must Precede New Attachments
Ten minutes in an emergency room will prove how fast romance gives way to statutory paperwork. Doctors look strictly to legal next-of-kin or designated healthcare agents, meaning unlisted partners and adult children holding power of attorney will inevitably clash over bedside decisions and critical treatment plans.
You do not have to hand over total medical control.
Keep clinical authority and financial powers of attorney squarely with your adult children so your assets and care remain protected. Then, simply update your advance directives to explicitly grant your partner hospital visitation rights, giving them access to your side without complicating your medical decisions.
💡 Tip: Provide copies of your updated medical proxy directly to your primary hospital network and your children.
Everyday Spending and Lifestyle Dynamics
Daily dating dynamics can quietly drain fixed retirement budgets. Income disparities, dinner bills, and emotional generosity often collide if clear expectations are not set early.
Managing day-to-day spending boundaries ensures romance fits comfortably within your monthly retirement cash flow.
5. Income Disparities Dictate Lifestyle Rather Than Generosity
I noticed early on that picking up every $120 dinner tab quietly eroded my peace of mind. It is tempting to subsidize luxury vacations and fine dining when a partner has a smaller pension, but funding another adult strains monthly withdrawals and creates silent resentment between you.
Dating well means living at the smaller budget.
I established a firm $350 monthly budget specifically for dates, dinners, and entertainment. We now choose modest local trips and casual dining that fit that dollar cap, or split travel expenses proportionally so both of us remain completely comfortable without overextending our fixed retirement income.
Unequal Incomes — Operational Guardrails
📍 Venue Selection Rule
Set by whoever has the lower fixed income
🧾 Check-Drop Protocol
Request separate tabs before ordering
🍳 High-Ticket Workaround
Substitute home-cooked meals for $200 nights
🔒 Account Firewall
Never link payment apps or open joint cards
The Red Line
If covering extra outings forces unscheduled retirement account distributions, shift to free local activities immediately.
6. Late-Life Romance Scams Target Loneliness and Wealth
Establish a zero-dollar transfer policy before sending your first message on any dating platform. Romance swindlers move fast, manufacturing deep emotional intimacy over two or three weeks to set the stage for an urgent emergency.
Any rapid declaration of devotion followed by a plea for bank wires, prepaid gift cards, or private investment capital is a calculated swindle. These operations rely on fabricated crises to siphon away thousands of dollars in liquid savings before adult children or bank fraud departments can intervene to halt the transaction.
Sent funds cannot be retrieved once a wire clears.
I follow a strict, non-negotiable rule: no electronic bank transfers, no gift cards, and zero dollars for business ventures pitched by romantic interests. When an emergency request appears, enforce an immediate 48-hour waiting period and walk through the exact story with your trusted financial advisor, CPA, or adult child.
Getting that objective third-party review breaks the emotional pressure immediately, keeping your retirement nest egg safe from irreversible damage before a scammer can manipulate your good intentions.
🛡️ Steps to Screen Financial Requests from a New Partner
Pause Immediately
Institute an absolute 48-hour hold on any financial request or emergency bailout pitch.
Consult a Third Party
Review the details with your fee-only fiduciary advisor or your designated adult child.
Enforce Cash Boundaries
Decline the monetary transfer while offering non-financial emotional support instead.
Document and Evaluate
End the connection immediately if guilt tactics or repeated money demands continue.
7. Unspoken Taboos Around Bill-Splitting Ruin Early Dates
The mistake most older daters make is relying on old dating customs from fifty years ago. Silence creates awkward friction the second the check hits the table. My standard rule is simple: whoever invites the other on the first outing pays the tab, and we split costs down the middle from date two onward. A quick sentence before ordering makes expectations clear and keeps everyone relaxed.
Keeping things affordable protects my $350 monthly entertainment budget. Free museum afternoons, municipal park concerts, and casual coffee walks let us enjoy getting acquainted without straining either person's wallet.
💡 Tip: Suggest free museum afternoons or municipal park concerts for second dates to keep spending low.
8. Long-Term Care Realities Outweigh Romantic Impulses
Most people assume entering a late-life relationship means agreeing to step in as an unpaid, full-time nurse whenever health fails. That romantic assumption is dangerous, and confusing emotional affection with lifetime medical underwriting can easily destroy your hard-won financial security.
When you date in your seventies or eighties, the statistical likelihood that one partner will face cognitive decline or severe physical disability is very high. Stepping in as an untrained caregiver puts your own health on the line, while paying for private home health aides at $30 an hour rapidly drains your retirement savings.
Companionship does not mean absorbing someone else's nursing costs.
To keep affection from turning into financial vulnerability, I put a three-pillar care system in place early on. First, we review coverage by checking if each partner holds a private long-term care insurance policy or sufficient individual funds. Second, we establish clear Medicaid asset boundaries so private assets are never exposed to spend-down rules for a partner's institutional stay.
Third, we formally agree that each partner's biological adult children remain the primary legal and logistical managers if skilled nursing or assisted living becomes necessary.
It sounds blunt until you realize private memory care easily tops $8,500 every single month. By distinguishing between personal caregiving and emotional support upfront, you prevent catastrophic surprises, protect your nest egg, and preserve the relationship as a source of joy rather than physical exhaustion.
Have that hard conversation within the first six months.
Documenting those boundaries protects your retirement assets so you can remain a loving companion at the bedside instead of a drained, unpaid custodian.
Family Harmony and Legacy Boundaries
Your new relationship does not exist in a vacuum. Adult children often worry about parental financial safety and their inheritance, while extended family requests can strain new bonds.
Transparent communication and formal legal contracts protect family harmony and preserve your personal autonomy.
9. Adult Children Expect Full Transparency About Estate Changes
Schedule a dedicated family meeting before your new relationship progresses toward serious milestones, and lay your estate paperwork openly on the kitchen table for your heirs to see.
Adult children rarely object to late-life companionship on its own, but they frequently harbor deep anxiety about romance scams, financial exploitation, and the sudden loss of family inheritances. Walking them through your legal records directly proves that your existing will, revocable trust, and primary beneficiary designations on every bank and brokerage account remain entirely unaltered.
Open paperwork stops family suspicion before it ever starts.
Turn this into a routine annual check-in to inspect three specific estate anchors together. First, confirm that the deed to the $420,000 mortgage-free home stays solely in your family trust. Second, show that your $650,000 investment portfolio still names them on all transfer-on-death forms. Third, confirm that durable powers of attorney remain strictly in their hands.
Introduce your partner in low-pressure social settings like casual Sunday lunches for several months before discussing any shared living arrangements, keeping family harmony intact while demonstrating that their inheritance remains fully protected.
Estate Communication: Transparent vs Concealed
Healthy Transparency
- Shares trust structure and beneficiary names with adult children
- Maintains separate property deeds and financial accounts
- Executes a formal cohabitation agreement before moving in
- Introduces partner gradually in neutral social settings
Risky Secrecy
- Hides relationship milestones from family members
- Allows informal move-ins without written tenancy terms
- Commingles primary bank accounts or credit lines
- Leaves healthcare proxies outdated during health crises
10. Prenuptials and Cohabitation Pacts Are Acts of Love
People assume asking for a legal agreement at eighty kills the romance. In reality, putting clear boundaries on paper is the kindest thing you can do for your partner and your kids.
You do not have to rewrite your entire estate in a single afternoon, but starting with a basic cohabitation pact creates clean operational clarity. That simple document should include plain clauses waiving any claims on survivor pensions, personal savings, and residential property equity.
I spent $4,200 updating my revocable trust and drafting agreements with separate, independent attorneys for each of us. That cost was not an act of suspicion; it bought total peace in probate court.
💡 PRO TIP
Retain Separate Attorneys for Cohabitation Pacts
For a cohabitation or prenuptial agreement to remain unassailable in probate court, both partners must hire independent, separate legal counsel.
11. Gifting and Lending to a Partner's Family Strains Bonds
The most protective answer you can give your relationship is to keep your checkbook closed.
Co-signing a mortgage, backing private student loans, or offering thousands in emergency cash creates permanent financial exposure you cannot absorb on a fixed income. Moving substantial sums outside biological lines complicates annual gift tax planning and depletes the nest egg you spent forty years building for your own heirs.
Money lent across family lines rarely returns without bitterness.
Establish an explicit rule that each partner handles their own family requests using their own private funds. If an extraordinary situation tempts you to help, schedule an hour with a fee-only financial planner or tax professional to see the exact long-term damage to your monthly draw before signing anything.
Saying no to outside financial bailouts keeps your daily relationship light and genuine. Protecting your retirement from secondary entanglements means your time together stays focused entirely on companionship, shared meals, and mutual respect rather than family disputes.
12. Maintaining Financial Independence Preserves Personal Dignity
Every evening, I turn the key in the front door of my mortgage-free $420,000 home, and that quiet sense of total ownership provides more security and peace than any whirlwind late-life romance ever could.
Deciding on a Living Apart Together arrangement was the specific move that saved us from domestic friction and legal confusion. We spend three evenings a week together, enjoy dinners out, and take road trips, but each of us returns to our own residence without merging utility bills, household chores, or real estate deeds.
Separate front doors preserve mutual respect.
Protect your accounts with the same discipline. Keep your primary credit cards in your own name, retain sole ownership of investment accounts, and direct all retirement distributions to your personal bank. I deposit my monthly Social Security survivor benefit privately, funding shared meals and outings strictly from my dedicated $350 monthly entertainment allowance.
Hold onto your existing social calendar and personal routines with equal care. Maintaining your regular coffee groups, solo hobbies, and family visits prevents you from becoming entirely reliant on one person for your daily happiness.
Independence is not coldness; it is clarity.
If a new romantic interest bristles at your boundaries or pushes to combine households, take that reaction as an immediate signal to step back and reevaluate.
Companionship after seventy or eighty brings immense joy, but only when your financial foundation remains completely undisturbed. A healthy relationship enriches your retirement with shared laughter and genuine affection, while preserving the legal independence, private assets, and hard-won personal dignity you spent an entire lifetime building from scratch.
Frequently Asked Questions
Will I lose my Social Security survivor benefit if I remarry after 60?
Under Social Security rules, remarrying after age 60 generally does not terminate your survivor benefits. However, private employer pensions and military survivor benefits often carry strict remarriage forfeiture clauses, making it essential to audit your plan paperwork first.
What is Living Apart Together (LAT) and why is it popular at 80?
Living Apart Together is an arrangement where committed couples maintain completely separate primary households. It offers companionship and shared activities without the legal tenancy, estate blending, and healthcare liability risks of moving in together.
How much does a late-life cohabitation agreement usually cost?
A thorough cohabitation agreement drafted by an estate planning attorney typically costs between $2,000 and $4,500. It is an investment that protects home equity and prevents expensive probate litigation for your biological heirs.
Should my new partner have power of attorney over my finances?
In almost all late-life relationships, your durable financial and medical powers of attorney should remain with your trusted adult children or a licensed fiduciary, rather than a new romantic partner.
Schedule Your Independent Estate Review Before Dating
Sustaining a fulfilling relationship at 80 means keeping romantic affection completely separate from legal and financial entanglement. My second chapter succeeded after 48 years of marriage because my property, survivor income, and estate distributions were legally secured before sharing life with a partner.
Schedule an independent estate planning review this month to update your trusts, beneficiary designations, and healthcare proxies before introducing someone new to your living space. Taking that step settles how you date in your seventies and eighties safely: by locking down your home and savings first, you leave yourself entirely free to enjoy the companionship.
Audit Your Estate Plan Today
Review your beneficiary designations and pension clauses right now to protect your assets before starting your next relationship.