The average American expects to live until 79, but many will live well into their 90s, making your retirement horizon potentially 30+ years.
That is a significant stretch of time, and it means the old idea of a short, golden retirement no longer applies. You are not just planning for a few years of rest; you are designing a full third act of your life, financially and personally.
This long view changes everything. It means asking a dozen questions now that feel uncomfortable, instead of waiting until the answers create bigger problems. You can build a retirement that fits your life and your numbers.
This guide walks you through the honest questions you need to ask yourself, with practical advice on how to approach each one. You do not have to tackle them all at once, but facing them now will give you clearer options and real peace of mind.
Quick Tips Before You Start
Gather Your Statements
Collect bank, brokerage, pension, and Social Security statements to see your current numbers.
Set a Review Date
Schedule a monthly check-in to revisit your progress and adjust your plans.
Talk to Family
Open lines of communication early about future plans, expectations, and needs.
Be Honest With Yourself
Answer these questions with your true feelings and numbers, not wishful thinking.
1. Your Actual Income Needs
Retirement brings a big shift in how money comes in, and often not a drop in how much goes out.
Many people find their initial spending in retirement actually matches or even exceeds their working years, especially if they have travel or big hobby plans. It's the trade-off of exchanging a steady, predictable paycheck for more personal freedom.
To make that freedom financially stable, you need to clearly separate your essential living expenses from your discretionary spending. Rent or mortgage payments, utilities, groceries, and basic transportation are your absolute essentials. Travel, dining out, and new hobbies are wonderful, but they are discretionary.
List all your potential income sources: your Social Security benefits, any pensions you're entitled to, and income from investment portfolios like a 401(k), IRA, or brokerage account. Don't forget any part-time work you might plan to do, even just a few hours a week.
Then, assess the stability of each. Social Security is generally stable, but investment income can fluctuate with market conditions. Knowing these numbers, even a rough estimate like a projected $4,000 a month from all sources, helps you understand how much flexibility your income streams offer against your non-negotiable needs.
2. Managing Healthcare Expenses
The cost of healthcare in retirement can feel overwhelming, a looming unknown that stops many people from even starting their plans.
It is a major expense, but it becomes manageable once you understand the pieces. Even just learning the basics of Medicare Parts A, B, and D is a huge first step.
Part A covers hospital stays, Part B covers doctor visits and outpatient care, and Part D covers prescription drugs. Beyond those, you'll need to choose between a Medigap policy, which supplements original Medicare, or a Medicare Advantage plan, an all-in-one private insurance option.
Do not overlook out-of-pocket costs. Deductibles, co-pays, and prescription drug expenses can add up quickly, even with coverage. Many couples find these unexpected costs can be a significant drain on their retirement funds, sometimes reaching $6,000 to $10,000 annually.
Finally, think about long-term care. Medicare does not cover extended nursing home stays or in-home care, and these can run $5,000 to $10,000 a month for skilled care. This can be one of the largest and most overlooked expenses in retirement planning. Start by researching long-term care insurance or simply understanding what self-funding options you might have available.
3. Debt Burden in Retirement
I have seen firsthand how much debt can erode the peace of mind retirement is supposed to bring. The dream of a comfortable retirement quickly fades when a $1,500 mortgage payment or a high-interest credit card bill arrives each month.
Consider paying off your mortgage before or early in retirement. Having that significant monthly payment gone frees up a large portion of your income, giving you more flexibility and less stress with a fixed budget.
If paying it off completely isn't feasible before you stop working, aim to reduce the principal as much as possible. Even cutting a $200,000 balance down to $50,000 before you retire can make a huge difference in your monthly payments.
Credit card debt and personal loans, often with interest rates of 18-25% or more, are particularly damaging on a fixed income. They eat into your limited funds, making it harder to cover daily essentials or enjoy discretionary spending. These are often the first debts you should target for repayment.
Develop a realistic debt reduction strategy. This might mean the debt snowball method, paying off the smallest balances first for psychological wins, or the debt avalanche method, tackling the highest interest rates first to save more money over time. Pick a method and stick to it.
The goal is not just to reduce debt, but to free up your cash flow. Every dollar freed from a debt payment is a dollar that can go towards living your life on your terms, whether that's a new hobby or a trip. This is a crucial step towards true financial independence in your later years.
Retirement Debt Priorities
🏠 Mortgage Target
Principal under 10% of fixed retirement income
💳 High-APR Cutoff
Eliminate all debt >15% APR before retiring
💰 Cash Flow Gain
Aim for $1,000+ monthly for spending flexibility
Why this matters
Reduces financial stress and stabilizes your fixed retirement income against unexpected costs.
4. Sufficient Emergency Funds
When my own water heater burst, the $1,200 bill was a punch to the gut.
That's exactly what an emergency fund is for in retirement: those unexpected thousands that can derail everything. Aim for three to six months of your essential living expenses saved up.
These funds should sit in a high-yield savings account, separate from your daily money. This keeps the cash liquid and earning a small return, protecting your investments. You're building a cushion for things like a sudden $5,000 furnace replacement or unexpected medical costs, which protects your long-term plans from getting raided.
5. Your Honest Retirement Budget
It's easy to feel anxious about a retirement budget, worried it means restrictions.
But the truth is, a realistic budget gives you control and clarity, letting you check in on your choices. Start by listing your current spending: housing, food, transportation, but also fun things like hobbies and travel.
Your spending will likely fluctuate; expect more on travel in the first five years, then a quieter routine. Use a simple spreadsheet or budgeting app to track where your money actually goes. This isn't about deprivation, but about making conscious choices and adjusting as life changes.
💡 PRO TIP
Build a "Trial Run" Budget
For six months before you retire, live on your projected retirement income. This reveals spending gaps and helps you adjust while you still have your working income.
6. Purposeful Daily Life
Start planning what will fill your days now, not on your last day of work.
Retirement brings immense freedom, but also a void if not planned for. Your work has likely defined a big part of your identity and schedule for decades.
Begin exploring new hobbies, volunteer opportunities, or skills you want to learn. These activities provide mental stimulation, structure, and social interaction, replacing what work offered. Start now: a purposeful daily life makes sure retirement is full of meaning, not empty time.
7. Home Suitability for Aging
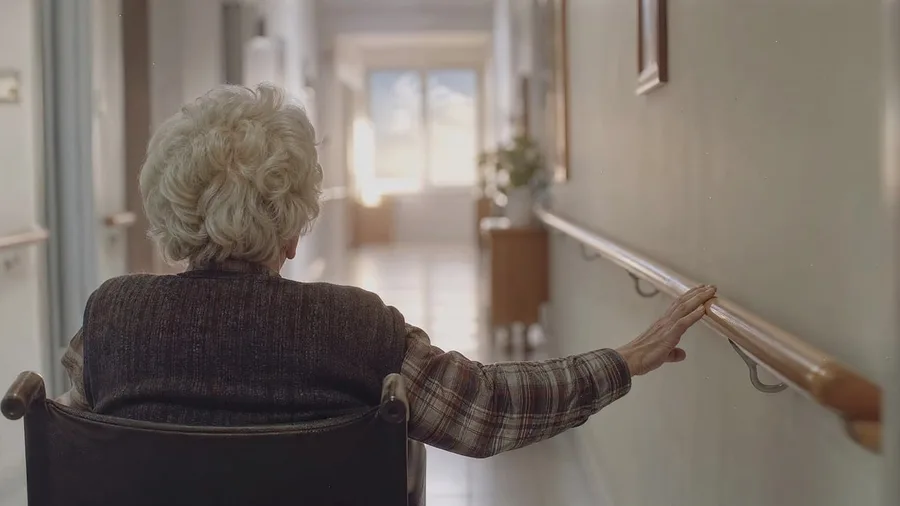
Many assume their current home will comfortably serve them through retirement. This is a common mistake; homes can become less practical as you age. Consider physical needs that change over time, like navigating stairs or managing a large yard.
Assess your home's accessibility, maintenance burden, and how close you are to services and family. Are doctors, grocery stores, or public transport within easy reach? Think about options: downsizing, relocating, or making modifications like grab bars or a first-floor living setup. Property taxes and utility costs can be a significant drain, potentially $300-$500 each month, so a smaller, more energy-efficient place might offer real financial relief.
Retirement Living — Key Costs
8. Maintaining Social Connections
It's a common and very valid concern. The workplace often provides a built-in social circle, and leaving it can feel like stepping into a vacuum.
The real shift here is from passive connections to actively creating your social life. You'll need to make a conscious effort to stay connected with former colleagues, and actively seek new friendships.
Community involvement is a powerful antidote to isolation. Join a club, a volunteer group, or a social organization that aligns with your interests. Committing to one or two new activities a week can provide regular interaction and a shared sense of purpose.
Don't overlook family relationships either. Regular visits, phone calls, or virtual gatherings with children, grandchildren, and siblings are incredibly important.
Your social well-being in retirement isn't automatic; it needs an active, thoughtful plan.
9. Working Part-Time
For many, completely stopping work feels less like a dream and more like a void. Instead, consider part-time work as a flexible system to ease into retirement while maintaining a sense of purpose.
Beyond supplementing your income to cover discretionary spending or unexpected costs, working a few hours a week offers valuable benefits. It keeps your mind engaged, provides consistent social interaction, and helps maintain a daily structure that many people miss once their full-time careers end.
Look for truly flexible options, like consulting in your old field, pursuing a passion project that brings in some cash, or taking a few shifts at a local library or non-profit. The goal is to find something that enriches your life without adding stress.
Understand how earning income can affect your Social Security benefits. If you claim benefits before your full retirement age, there's an annual earnings limit – for example, around $22,320 in 2024. Going over this temporarily reduces your benefit payments until you reach full retirement age, so factor that into your planning.
Your retirement, your rhythm.
Part-Time Work vs. Full Retirement
Working Part-Time
- Adds to income, extends savings life
- Maintains social connections and purpose
- Keeps skills sharp, provides routine
- Allows for gradual transition
- Can help cover unexpected costs
Full Retirement
- 100% leisure, but can lead to boredom
- No regular work income beyond benefits
- Requires strong self-discipline for structure
- Sudden shift can be jarring
- Social circles may shrink without effort
10. Family Discussion & Expectations
It can feel incredibly awkward to bring up money or future care, but making these conversations a regular, planned event works like an automation. It sets clear expectations upfront, stopping assumptions from building into bigger emotional problems later. This proactive clarity prevents misunderstandings and resentment from piling up.
Consider caregiving: do your adult children expect to help you, or do you assume you'll be providing childcare for grandchildren several days a week? These potential roles carry a lot of unspoken weight and can lead to friction if not discussed.
Then there are financial expectations. Many adult children might assume an inheritance of $50,000 or more, or expect continued financial support, while your own retirement budget plans differently. Having a plain talk about these figures and intentions now saves countless arguments later.
These aren't easy conversations to start.
But setting a recurring 'family check-in' for important life changes, maybe once a quarter or just once a year, makes it part of the normal rhythm. This isn't about one big, scary meeting where everything is decided, but a series of open talks.
Start with just one topic, like what kind of involvement you hope to have with grandkids, or if you're able to help with a child's rent for the next year. This scheduled, honest approach protects relationships, making sure everyone hears the plan directly, rather than guessing. It's an investment in family peace.
It's better to start small than to avoid it entirely.
⚠️ COMMON MISTAKE
Assuming Family Knows
Many retirees assume their adult children know their wishes or plans. This often leads to awkward conversations or conflicts when critical decisions arise without prior discussion.
11. Up-to-Date Estate Plan
The myth is that any old will is good enough. But an up-to-date estate plan gives you permission to truly relax about your legacy, knowing your wishes are legally recorded and will be followed. It brings clarity for your family later.
You need a will, a power of attorney for finances, and advance directives for healthcare. Critically, check beneficiaries on accounts like your 401(k) and life insurance: one forgotten policy can accidentally reroute $50,000 or more to the wrong person.
Don't forget digital assets, like online accounts. If tackling it all feels overwhelming, start small: just review your beneficiaries on investment accounts this week. You don't have to overhaul everything at once.
Estate Planning Scenarios
Based on a typical estate value of $800,000
12. Contingency for Setbacks
I learned from watching friends that even the best-laid plans need a backup. No one can predict the future, so asking, "What is my contingency plan if things go wrong?" is smart planning for your retirement years.
Start by reassessing your investment risk tolerance. As you near and enter retirement, you typically shift to a more conservative portfolio. This protects your capital from market volatility, accepting less growth potential in exchange for more stability.
Consider strategies for unexpected health crises or long-term care needs. This might mean setting aside a dedicated fund of, say, $10,000, or understanding your insurance coverage. Do not wait for a crisis to make these critical decisions.
Build flexibility into your budget. Identify areas where you can cut back, maybe $300 to $500 a month, without severely impacting your quality of life if a major setback occurs.
For personalized guidance on these complex scenarios, a fee-only fiduciary or a Certified Public Accountant (CPA) can provide tailored advice for your specific financial situation.
🔄 Steps to Periodically Review Your Retirement Plan
Quarterly Income Check
Review all income sources against actual spending to ensure you are on track.
Bi-Annual Budget Update
Adjust your budget to reflect changes in spending habits, inflation, or new goals.
Annual Portfolio Rebalance
Reassess your investment risk and rebalance your portfolio to maintain target allocations.
Every 3-5 Years: Estate Review
Consult with an estate planning attorney to update wills, trusts, and beneficiaries.
Ongoing Health Assessment
Regularly review your health insurance coverage and long-term care needs.
Frequently Asked Questions
How much money do I need to retire comfortably?
Comfort is subjective, but a common guideline is to aim for 80% of your pre-retirement income. This varies based on your lifestyle, healthcare costs, and whether your mortgage is paid off. Your own budget is the only real answer.
Can I still make big purchases in retirement?
Yes, but with careful planning. Major purchases like a new car or home renovations should be factored into your retirement budget and funded from designated savings, not through new debt that impacts your fixed income.
When should I start claiming Social Security benefits?
You can claim as early as age 62, but your benefit will be permanently reduced. Waiting until your full retirement age (FRA) increases your payment, and delaying until age 70 maximizes it. The choice depends on your health, other income, and longevity expectations.
What's the 'safe withdrawal rate' in retirement?
A commonly discussed guideline is the '4% rule,' where you withdraw 4% of your portfolio's value in the first year and adjust for inflation annually. This rate is a starting point and depends on market conditions and your investment strategy.
Is it too late to save for retirement if I am 50 or 60?
It is never too late to save. Focus on maximizing catch-up contributions to your 401(k) or IRA if you are 50 or older. Even small, consistent contributions can make a difference over a decade or more, especially when combined with reduced spending.
Preparing for Your Confident Retirement
Retirement is a significant life transition, and it deserves careful, honest planning. The questions here are designed to help you look at your finances and your life with clear eyes, identifying areas of strength and places where you need to build more cushion.
Your next practical step is to pick one question from this list where you feel least prepared. Gather the relevant documents or have that difficult conversation. Starting somewhere, even small, is far more powerful than waiting for the perfect moment.
Ready to Start Planning?
Revisit the questions that resonated most with you. Take action on one item today to build momentum toward your confident retirement.