Yes, a retiree with $1.2 million can legally pay $0 in federal income tax for a year, and no exotic credits or audit bait are involved. The bill is $0 because almost every dollar that funded the year had either already been taxed or never entered the taxable column at all.
Take the concrete case: single, 67, retired at 65, no wages and no pension, spending $62,000 a year. The federal return shows only a sliver of taxable Social Security, a $3,000 traditional IRA withdrawal, and a $10,000 long-term brokerage gain, and the standard deduction erases what is left. That is federal income tax only. State taxes, Medicare premiums, and property taxes are separate bills entirely.
What you really control is the mix. A traditional IRA is untaxed money until you withdraw it, a Roth and your brokerage basis have already been taxed, and cash sits there taxed and quiet. The order you draw from those buckets decides how much enters taxable income in any given year.
By the end you should be able to judge whether your own accounts and spending fit that sequence, see what future tax still sits in a traditional IRA, and know the first thing to check. Copy the order, not the numbers.
The $1.2 million is split by tax treatment
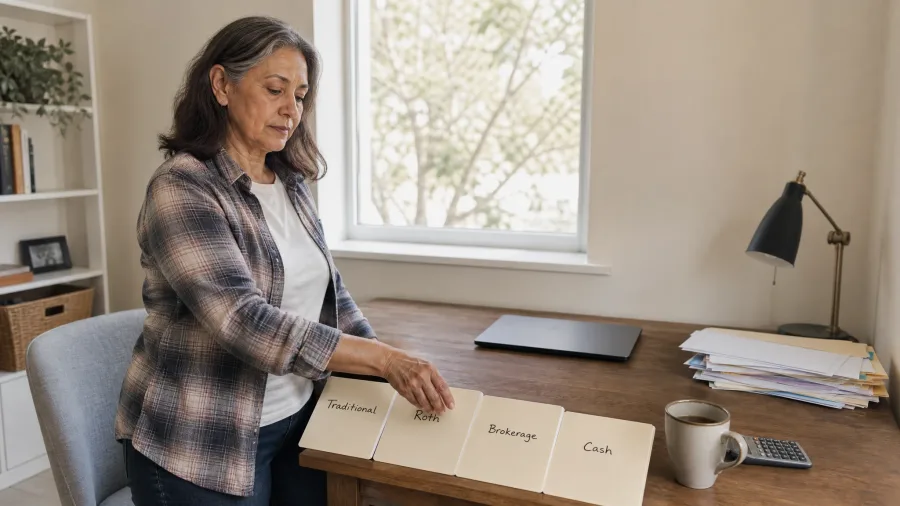
The retiree owns a $1.2 million portfolio, and every dollar in it falls into one of three tax categories. The federal return in this example is built from those categories, not from a salary.
Here is the split. $500,000 sits in a traditional IRA, which is money that has never been taxed. $350,000 sits in a Roth IRA, which is money that was already taxed before it went in and comes out tax-free. $290,000 sits in a taxable brokerage account with a $200,000 cost basis, meaning the retiree paid $200,000 in over the years and only the growth on top is untaxed. The last $60,000 is cash, which carries no tax at withdrawal because it was already taxed on the way in. Add those four pieces and you get $1.2 million.
That makes the traditional IRA the only big untaxed pool here.
Sell $10,000 of the brokerage holdings and only part of that sale is new taxable income. The $10,000 of basis rides along untaxed, and just the $10,000 long-term gain enters the return. In this portfolio the sale doesn't move the full $20,000 into taxable income – only half of it does. That distinction between basis and gain is why a taxable account pays for spending with so little tax cost when it has been held a long time.
Now consider the income side. This retiree is 67, retired since 65, and has no wages, no pension, no business income. Medicare covers health costs and the mortgage is paid off. Nothing forces income onto the return except withdrawals the retiree chooses, so the account split becomes the lever. The same $62,000 of spending could come almost entirely out of the traditional IRA in one year and be fully taxable. Because the Roth, brokerage basis, and cash exist, this retiree can hold that traditional withdrawal to $3,000.
| Income source | Amount in this example | Taxable portion in this example | Why it matters |
|---|---|---|---|
| Social Security | $30,000 | Only a limited portion, per the IRS worksheet | Keeping other income low holds down the taxable share |
| Traditional IRA withdrawal | $3,000 | $3,000 ordinary income | This is the only pre-tax money pulled this year |
| Brokerage sale | $20,000 | $10,000 long-term gain only | The $10,000 basis is your own money coming back |
| Roth IRA withdrawal | $9,000 | $0 | Already taxed before it went in |
| Cash reserve | $60,000 held | Not taxable until used | A buffer, not an income event |
Spending comes mostly from already-taxed dollars
The $62,000 year is paid from four places, and only two of them add anything to taxable income. Social Security supplies $30,000, a traditional IRA withdrawal supplies $3,000, a brokerage sale supplies $20,000, and a Roth withdrawal supplies $9,000. Add them up and you land at $62,000.
Walk through the tax character of each. The $9,000 from the Roth is after-tax money and enters the return as zero. The $20,000 brokerage sale carries $10,000 of basis that comes back tax-free and $10,000 of long-term gain that is taxable. The traditional IRA draw is $3,000, all of it taxable because it has never been taxed. Social Security is its own puzzle, handled next.
Notice what the retiree does not do: pull a large traditional IRA distribution to cover the shortfall. Spending $62,000 from a $500,000 traditional IRA in a single year would put the full amount into taxable income and change the entire return. Here the traditional money stays parked, and the spending comes from buckets that were already taxed or already paid for.
The $60,000 cash reserve is the safety net, not the funding source. It sits there as a buffer for a surprise year, but this year's $62,000 comes from Social Security, the brokerage sale, the Roth, and the small IRA draw. The discipline is in that list: after-tax money does the heavy lifting, and the untaxed account contributes a sliver.
💡 PRO TIP
The brokerage account is the quiet workhorse
A taxable brokerage sale reports only the gain, not the full withdrawal. If you have a large cost basis, that account can fund years of spending with a fraction of the taxable income a traditional IRA withdrawal would create.
Only a sliver of Social Security is taxable
– in this example only a limited portion of the $30,000 Social Security benefit enters taxable income. The rest stays out of the federal return, and the reason is the size of the other income sitting around it.
Social Security taxability is calculated on a worksheet, not a flat rule. The formula looks at the retiree's other income – here the $3,000 traditional IRA withdrawal and the $10,000 long-term brokerage gain – and determines how much of the $30,000 benefit becomes taxable. Because those other amounts are small, the taxable share of the benefit is small too. The exact calculation comes from the current IRS worksheet; this example doesn't rely on a fixed threshold figure, so any reader should confirm the current formula rather than assume one.
This is where the withdrawal order first pays off.
The taxable share of Social Security is not attached to the $30,000 benefit itself. It is attached to what else shows up beside it. Pull $40,000 from the traditional IRA instead of $3,000 and the other-income figure rises, the taxable portion of Social Security rises with it, and the return changes shape. The retiree's mix keeps the other income low, and the benefit stays mostly out of the tax calculation.
For a reader, that means the Social Security line on the return is downstream of the withdrawal decision. Keep the taxable accounts quiet and the benefit cooperates.
The standard deduction erases the remaining taxable income
On paper: the standard deduction is what actually drops the bill to zero, but the sliver of taxable Social Security has to be small first. Add up what enters the return before any deduction applies. There is the limited taxable portion of the $30,000 Social Security benefit, the $3,000 traditional IRA withdrawal, and the $10,000 long-term brokerage gain. If the taxable Social Security piece sits at a few thousand dollars, that's somewhere around $15,000 to $18,000 of taxable income facing the deduction.
The standard deduction is a flat amount the IRS lets you subtract from taxable income before any tax is calculated. In this example it is large enough to wipe out that entire remaining stack, which is why the federal income tax line lands at $0.
No itemized deductions, no credits, no withholding get it there. It's the deduction doing all the work.
Here's the part that matters more than the mechanics. That $0 depends on the total staying under the line, not on clever tax moves. Stretch the traditional IRA withdrawal from $3,000 to $15,000, and the numbers shift so the taxable stack climbs above the deduction and a bill appears. The exact standard-deduction figure changes with the tax year and filing status, and you don't find it in a third-party article. You pull the current number from the IRS, either the instructions for the return you're filing or the agency's own published guidance, and run your own figures against it.
For the reader, this is the checkpoint. Before you assume your own bill is $0, write down every taxable dollar entering the return and look the deduction amount up at the source. If the stack sits underneath it, the math works the same way for you.
🧾 The order that produced the $0 bill
Spend down to the $62,000 gap
The $9,000 Roth withdrawal is the flex point: $62,000 minus $30,000 Social Security minus $3,000 IRA minus $20,000 brokerage leaves that exact $9,000, pulled from the account with no future tax.
Sell $20,000 of brokerage to free $10,000
Only the gain is income. The $200,000 basis on the $290,000 account means this sale buys $20,000 of spending while reporting $10,000, an effective 50% income rate on the dollars spent.
Hold the IRA draw to $3,000
That is 0.6% of the $500,000 traditional balance. Big enough to look deliberate, small enough to leave room under the deduction once the long-term gain and the taxable slice of Social Security are stacked.
Check it before the year closes
Run the numbers in November, not April. A larger IRA withdrawal taken in January cannot be unwound at filing; a smaller one leaves the $0 intact.
Remember the room runs out at 73
Required minimum distributions start then on the whole $500,000, not the $3,000. Every low-draw year now shrinks the pile that later gets forced into income.
A $0 bill is not a $0 cost
It's federal income tax, and only federal income tax, sitting at zero. The retiree still pays plenty, just not on that one line. State income tax, if the retiree lives in a state that levies one, applies to the same withdrawals by its own rules and its own brackets. Medicare premiums come out of the Social Security check every month before the money ever lands. Property taxes on the paid-off house keep coming, and every purchase at the register carries sales tax.
The zero on the 1040 is a single line item, not a statement about the year's true cost.
Then there's the part that doesn't show up on any bill this year. Of the $1.2 million, $500,000 is still sitting in the traditional IRA, and not one dollar of that has been taxed yet. It is deferred, not forgiven. Every future withdrawal carries ordinary income tax at whatever the brackets say then, and required minimum distributions will eventually force money out whether it's convenient or not. The Roth money has already been taxed. The brokerage basis has already been taxed. Only the traditional IRA carries the IOUs.
Keeping income low to protect the $0 also cost something in flexibility. The drawdown order bent around the tax number, which means less room to pull large sums in a year the retiree might want them. And income counted for tax purposes feeds into Medicare premium calculations, so the same low-income discipline that protects the tax bill can shift what gets paid for coverage. Those two effects need checking against current official rules, not a rule of thumb.
The $0 is a result for one year of a return. It is not an exemption you carry forward.
Where a $0 bill fits, and where it backfires
A $0 bill can work if you have
- Modest spending relative to your portfolio
- A sizable Roth or taxable-basis bucket
- Flexibility to choose which account funds each year
- No large pension or required traditional IRA draw
A $0 bill backfires if you have
- High annual spending that exceeds the standard deduction
- Most of your money in a traditional IRA
- A pension or other fixed taxable income
- Large required withdrawals coming in a few years
Copy the order, not the exact numbers
Only if the structure underneath matches, and most portfolios don't. The order is copyable. The $1.2 million split is not. Start with projecting next year's spending, then pull from brokerage shares with a basis first, then Roth, then cash, and keep the traditional IRA withdrawal small enough that it doesn't drag a bigger tax bill in behind it. Verify whatever you come up with against current IRS rules before you trust it.
That order fits a specific reader: spending in the same range as the $62,000 example, a sizable Roth bucket, taxable brokerage with real basis behind it, flexible withdrawal timing, and no pension or large required traditional IRA draw forcing income into the return.
It fits badly for a reader whose money sits mostly in a traditional IRA. Same for a pension that shows up on the return no matter what, or a spending level that needs six figures a year, or required withdrawals large enough that the traditional IRA empties into taxable income on a schedule. Force a $0 bill in those situations and the tax doesn't disappear. It lands later, in bigger brackets, possibly alongside Medicare premium effects.
The first step is a sheet of paper, not a strategy. List every income source you'll have next year in one column, and in the column beside it write the taxable portion of each, using the current IRS guidance to fill it in. Social Security, IRA withdrawals, brokerage gains, anything else. Once every source and its taxable share is on one page, you can see whether the stack clears the standard deduction or not.
That sheet tells you whether you're built for the order. Skip it and you're guessing at a number that has to be right the first time.
Frequently Asked Questions
Is a $0 federal tax bill on $1.2 million typical?
No. This example relies on modest spending, a large Roth and brokerage basis, and a very small traditional IRA withdrawal. A retiree with high spending or most of the money in a traditional IRA would likely owe federal income tax.
Does a Roth withdrawal count as income?
Qualified Roth withdrawals do not appear as taxable income on the federal return. That is why they are useful for keeping taxable income low. But spending the Roth also reduces the post-tax pool you can draw on in later years.
How much of Social Security is taxable?
It depends on your provisional income, which combines adjusted gross income, tax-exempt interest, and half your Social Security benefit. The exact formula lives in the current IRS worksheet. Low other income usually means a smaller taxable share of the benefit.
Will I owe tax later on the traditional IRA?
Yes. The remaining traditional IRA balance is still untaxed, and withdrawals are ordinary income when they happen. The $0 bill postpones that tax; it does not erase it.
Does this cover state taxes and Medicare premiums?
No. This is federal income tax only. State income tax, Medicare premiums, property tax, and sales tax are separate. A $0 federal bill can coexist with a real state tax bill.
Should I try this on my own?
Start by listing every income source and its taxable portion for next year, then test the result against current IRS guidance. If required withdrawals or a pension are involved, run the numbers with a CPA or a fee-only fiduciary before changing your withdrawal order.
Fill In Your Own Income Sheet Tonight
The verdict is that a $0 federal tax bill is real for this example and conditional on it. Copy the withdrawal order, not the $1.2 million split or the $62,000 of spending, because a different mix produces a different number.
The headline is neither a one-off story nor a loophole here. It is a result: $500,000 of traditional IRA money still carries tax when it comes out, and nothing about this year made that disappear.
So the first move is a one-page income sheet. List every income source and its taxable portion for next year, then test the $0 result against the current IRS standard deduction and the Social Security worksheet.
Do not force a $0 bill if you spend heavily, hold mostly traditional IRA money, draw a pension, or face large required withdrawals. Build that plan with a CPA or a fee-only fiduciary, because forcing zero can push tax into later years or raise your Medicare premiums.
Start with the income sheet
Before you change a single withdrawal, write down every income source and its taxable portion for next year. That one page is where the real plan starts.