The neighbor saved $400 re-pricing her homeowners policy, and a friend says his advisor found money in his. You are looking at the same declarations pages you have had for years, wondering what everyone else knows.
nothing about your coverage has changed on paper since you stopped commuting. The money is not in a new product or a smarter strategy. It is in four inputs entered years ago and never re-entered, plus a roof age and a square footage typed wrong on a page nobody reads.
For a couple of 68 and 70 carrying $6,280 a year in premiums, correcting those is worth $1,295. That is 2 hours 40 minutes, three calls, four quotes and two signatures, about $490 an hour, more than the Part D review or the bank-fee cleanup.
Provided every cut is a price cut, not a coverage cut.
By the end you will know which call goes first, which three numbers to have in hand, which savings to take, and which two to leave alone because they quietly hand the risk back.
Quick Tips Before You Start
Pull the declarations pages
Find the one-page summary for each policy—home, auto, umbrella, life. Not the whole policy, just the declarations.
Measure the house
Check your square footage against the policy. A 200-square-foot error can cost $100 or more a year.
Count the miles
If you drive 6,000 miles a year now but the policy says 15,000, that's a stale input worth fixing.
Write down the roof age
A 19-year-old roof listed as 12 years old is a pricing error in the insurer's favor.
Call your agent first
Before shopping around, give your current agent a chance to correct the record. It's one call.
Where the money is hiding
The leak isn't in the coverage you bought. It's in the inputs that priced it—facts entered once at purchase or last change and never revisited. Insurers don't call to ask if your roof aged or your commute disappeared. They just keep charging you for the life you had.
1. Your policies were priced for a working life
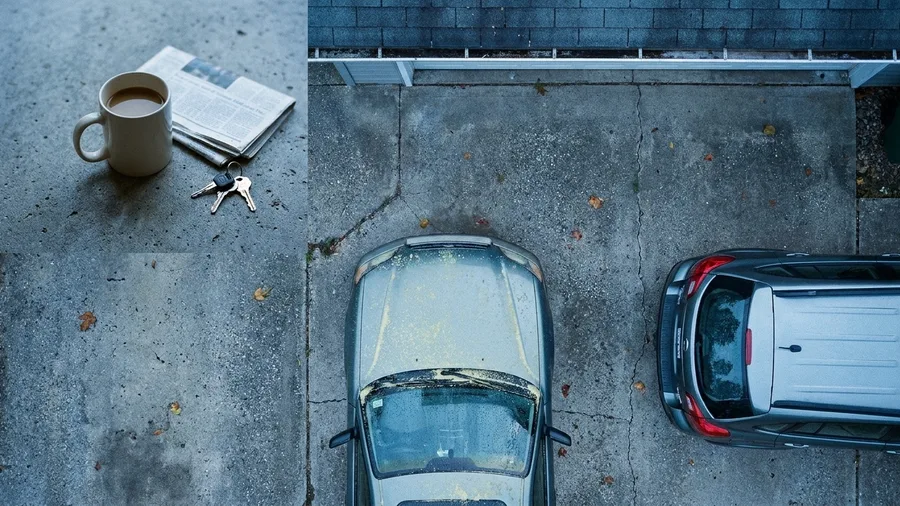
The last time anyone from the insurance company asked about my life, the roof was eight years old and I was still driving to an office every morning.
Four numbers decide what you pay, and all four are entered once: annual mileage, the address where the cars sleep at night, the age of the roof, the dependents named on the policy. No insurer comes back and asks about any of them. A renewal is a fresh rate on the same old answers, so the answers from a working life keep pricing the retired one.
Do one thing this week: pull your home and auto declarations pages and write the four inputs down. For a couple of 68 and 70, two commutes, a mortgage, kids at home and a newer roof became two cars mostly parked in a Midwest driveway, a mortgage paid off, kids gone, and a roof now 19 years old. The coverage was never the problem. The inputs were.
💡 Tip: Before you call anyone, write down the real numbers for all four inputs: miles per year, where the cars sleep, roof age, and who actually depends on your income. That list is your ammunition.
The same policy, two sets of inputs
2. Auto and home hold most of the leak
The popular idea is that the money hides somewhere exotic, in an annuity rider or a product an advisor has to sell you. It doesn't. It sits in the two folders you already own and almost never open.
Add up where the recoverable dollars land for the couple of 68 and 70: $310 from lifting the home deductible to $2,500, $420 from putting the auto policy out to bid, $280 from letting collision go on the 2019 sedan, $190 from fixing a roof age and a square footage typed wrong, $95 from tucking the umbrella under the same roof. That is $1,295, and $1,010 of it – $310 plus $420 plus $280 plus $190, less a little rounding – comes out of home and auto alone. Those are the two policies nearly every retiree already carries, and the two that answer to the four stale inputs. The $1M umbrella gives back just $95 by bundling; the $250,000 term policy gives back nothing at all from the audit.
So if the calendar only holds one free afternoon this month, spend it on those two folders and let the umbrella and the life policy wait for a second sitting.
That is where a real professional earns their keep, because auto pricing swings on your zip code, your claims record and your credit-based insurance score, none of which you can eyeball from the kitchen table. A fee-only fiduciary or an independent agent who writes for several carriers can price the same coverage across four quotes, and your state insurance department can tell you what a fair rate looks like where you park the cars. You bring the numbers – roof age, square footage, annual mileage, garaging address – and they bring the market.
The trade-off is a morning on the phone and one deductible you may or may not want to carry, and $1,010 is the return for that morning. Leave the rest of the file closed for now; it is not going anywhere.
💡 PRO TIP
The declarations page is the whole game
You don't need the full policy to find the money. The declarations page lists every input that drives your premium: roof age, square footage, mileage, deductible, coverage limits. Read it line by line with the house and cars in view.
3. You may be paying for life insurance nobody needs
The worry is understandable: twenty years of premiums paid, and stopping now feels like throwing all of it away. Here is the thing – the decision can wait, and waiting costs you nothing.
Take the policy in the example: $250,000 of term life, $1,180 a year, running until age 72, bought back when a mortgage and two kids at home needed replacing. At 68 and 70 it is still being paid with a few years of term left. The question to run first is not whether it is worth the $1,180 – it is who depends on that income now. Is there a mortgage balance left? Are the children grown and independent? What does the surviving spouse's income look like without it? Answer those three and the decision mostly makes itself.
One caution before anyone picks up the phone to cancel: lapsing is a one-way door. The health that priced this policy at purchase is gone, and a replacement at 68 or 70 gets re-underwritten or refused outright. You cannot buy it back at the old rate.
So the permission slip is this: leave it alone for now. The $1,295 does not depend on touching the life policy, which means a beneficiary and dependents check can happen next month or next spring without costing a single dollar. Keep paying the $1,180 while you look, and let the smaller, reversible decisions come first.
💡 Tip: If you're unsure whether to keep a term policy, talk to a fee-only fiduciary who can look at your whole picture. Don't cancel based on a hunch.
| Money task | Time it took | Saved per year | Saved per hour |
|---|---|---|---|
| Insurance audit | 2 hr 40 min | $1,295 | ≈ $490 |
| Medicare Part D review | 3 hr | $600 | $200 |
| Bank fees and CD ladder | 4 hr | $410 | ≈ $100 |
| Subscriptions and recurring bills | 1 hr | $240 | $240 |
4. Small errors on the declarations page cost real money
Pull the declarations page out of the folder, or find the copy in your online account, and lay it on the kitchen table beside whatever tells you the real numbers. The roof age matters most because the insurer prices the house as if yours was built when the page said. Hold the square footage against your property tax record, the garaging address against where the cars sit overnight, the annual mileage against what you actually drive now that nobody commutes, and the named dependents against who lives there. A newer, larger house on paper than the one standing at the curb is priced accordingly, and correcting a 12-year-old roof listed against a 19-year-old roof, plus 2,400 square feet listed against 2,100, is worth $190 a year all by itself.
Call the agent with the four facts written down. Nobody is coming out to check the driveway, so the page stays wrong until you say otherwise.
Is this the same coverage at a better price, or less coverage for a lower price?
— The filter to run on every dollar in the audit
Why it takes an afternoon, not a month
The reason this audit fits in one sitting is simple: no new policy is required. Every dollar comes from a policy already in force, from a corrected fact or a lower price on the same terms.
No application, no medical questionnaire, no underwriting decision. Nothing in the job can be declined.
5. An audit buys nothing, it re-prices what you own
Four quotes on the table, compared side by side in one sitting, and every dollar of the $1,295 comes back out of a policy that is already in force. Nothing here is a purchase.
The structure is three calls and one sheet of paper. Call one goes to the agent you already have: the roof age and square footage correction, and the deductible move, on the home policy you already carry. Call two is the auto re-shop, because the only way to know what the same coverage costs elsewhere is to ask, and that single call carries the $420. Call three is the umbrella bundle quote, the one that pays $95 for asking.
Four quotes land in front of you, and here is where the sheet earns its keep: write each one down on the same page, in the same format, with the coverage limits and the deductible in their own columns. Compare the columns before you compare the totals, because a quote that undercuts a neighbor on price is not cheaper if the limits underneath it are lower. What you are looking for is an identical set of terms at a smaller number, and that is the only line you take.
That is the whole repeating structure, and you can copy it for any policy year after year: three calls, four quotes, one comparison sheet with the coverage beside the price.
No application sits behind any of it. No medical questionnaire waits in the middle, and no underwriting decision hangs over the result, because the coverage already exists and you are not asking anyone to approve it. That is the reason none of the work can be turned down after you have done it.
Two forms get signed at the end. One covers the corrections, one covers the deductible change, and nothing else is signed. Nothing gets cancelled by accident either, because the household asked for a price and a fact to change, not a policy to end.
The policy keeps running while you work. Every saving takes effect on the one that is already there, so the audit never interrupts your coverage to improve it.
💡 Tip: Keep a copy of every form you sign and the date each correction takes effect. If the next renewal doesn't reflect them, you'll have the paper trail to fix it.
6. The whole job fits in one afternoon
The fear is that a call to an insurer turns into a stack of forms and a week of waiting on hold, and that the afternoon you set aside is gone before the first person picks up the phone. That fear is honest and it is also a little out of date, because none of this job waits on anyone's approval.
Here are the four blocks, and you can time them all on a single afternoon. Twenty-five minutes listing the four policies and the premiums beside them. Forty minutes on the three calls. Forty-five minutes comparing the four quotes you have gathered. Thirty minutes signing the two forms that close it out.
That is 2 hours 40 minutes end to end, and the whole thing starts the moment the declarations pages are in your hand. The corrections apply to the policy itself rather than a new one, so the clock is yours to set.
One block is the one people skip, and it happens to be the 45 minutes that produces the $420 auto saving. Skip it and the single largest line of the total never comes in.
$1,295 across 2 hours 40 minutes works out to roughly $490 an hour. That is the figure to hold in your head when you decide whether the afternoon is worth your time.
💡 Tip: Set a timer for each block. The 25-minute listing is the easiest to stretch into an hour if you let it. Timer on, phone off, pages out.
⏱️ The 2-hour 40-minute audit
List the policies (25 min)
Write down each policy name, premium, and the declarations page details.
Make the calls (40 min)
Call your agent for corrections, then re-shop auto, then get an umbrella bundle quote.
Compare quotes (45 min)
Lay four quotes side by side and check that coverage limits match.
Sign the forms (30 min)
Sign the corrections and deductible change, and file copies for your records.
7. Other money chores pay less for the same hours
Put the afternoon's pay rate next to the other chores on the calendar and the order settles itself.
The Medicare Part D review is the one most retirees do first, because the open enrollment window makes it feel urgent. For the couple of 68 and 70 it takes about three hours of sorting drug lists against plan formularies, and it returns around $600. That is $200 an hour, and it is real money, but it is less than half what the insurance calls pay for the same clock time.
Bank fees and the CD ladder come in worst. Four hours of statements, branch visits or phone trees and moving money between accounts returns about $410, which works out near $100 an hour. Nobody needs to feel bad about skipping it this month.
The subscription cleanup is different again. One hour, $240 recovered, and the reason it is worth doing is not the rate. It is that it can happen in the same week as the insurance calls without displacing them. Cancel the forgotten streaming tier on a Tuesday and make the agent call on a Wednesday.
Insurance is the outlier at roughly $490 an hour. Two hours and 40 minutes returns about $1,300, which is more than the other three chores combined, and it beats every one of them on rate.
The part that does not show up in the arithmetic is what the hours leave behind. The other chores recover money once and the same work waits again next year. The insurance afternoon fixes a roof age and a square footage that would otherwise misprice the policy for as long as it stays wrong. A wrong input does not expire.
So automate the sequencing rather than the willpower. Set a recurring note for the first week of the month after the declarations pages are corrected, with three lines on it: re-check the roof age and square footage against the house, confirm the garaging address still matches the driveway, and log what the premium did at renewal. Ten minutes a year. The calls themselves you only make once.
Price savings vs. protection trade-offs
Price savings (safe to take)
- Correct roof age and square footage
- Re-shop auto with the same limits
- Raise deductible only if you have the cash reserve
- Bundle umbrella for a multi-policy discount
- Drop collision on a car worth under $10k
Protection cuts (think twice)
- Lower liability limits to save premium
- Cancel umbrella without comparing to exposed assets
- Drop collision on a newer car
- Let a term life policy lapse without a dependents check
- Skip the declarations review because it feels tedious
What the savings cost you
Not every dollar in the audit is free. Some of the biggest line items—the $310 deductible move, the $280 collision drop—are trades. They lower your premium by moving risk back onto your own balance sheet.
The question to ask with each one: can I afford the worst case this creates, and is the premium saving worth that risk?
8. What am I giving up to get that premium down?
What does it cost you? A deductible moved from $1,000 to $2,500 puts $310 back in the pocket each year and leaves the household holding $1,500 more of every claim. The coverage is untouched: same limit, same perils, only the first slice of the loss moves from the insurer to you. That makes the $310 a price dollar, not a protection dollar.
The break-even is about five years. Five years of $310 recovered covers one $1,500 claim, so a single bad winter inside that window wipes out the gain. That math decides it. If $2,500 sits in a reserve you do not need to touch, the move works. If the first $2,500 of a claim would go on a card at 20%-plus, the arithmetic flips against you. When I ran the version of this that went wrong, the deductible move looked like free money on the spreadsheet and the repair bill three months later was the part I had not priced.
9. When is cutting coverage on an old car a mistake?
Take the $280 off the 2019 sedan only if you are sure the car still works for you. The collision premium is $280 a year and the car is worth $9,800. A write-off pays at most that $9,800 less the deductible, so you are paying $280 to insure a payout capped near $9,800. Keep collision while a write-off would change what the household drives. Let it go once the car is worth under roughly $10,000 and a reserve can replace it. The $280 then buys less than it costs.
This is the move with a deadline hiding inside it, and the deadline is the car itself. Every year the sedan holds still, the worth of what you are insuring drops while the premium does not keep pace. The number to check is the current private-party value, not the sticker when you bought it. That check takes five minutes on a used-car pricing site.
The same cut on the newer car throws money away. The 2021 SUV stays fully covered, because a total loss there is a five-figure replacement and the annual premium is small against it. Two cars, two answers. One policy cannot take the same decision applied to both.
Liability on the 2019 sedan stays, whatever else moves. The other driver's injury claim and the medical bills do not shrink because the household stopped insuring its own paint. That is the line: cut the repair coverage, never the harm coverage.
Do the check this week, before the next renewal posts. Call the agent for the car's collision figure and the current value. If the value has fallen under $10,000 and the reserve is there, the $280 comes off the same policy the next payment applies to.
⚠️ COMMON MISTAKE
Don't let a savings goal become an underinsurance plan
The fastest way to hit a $1,300 target is to shave liability limits. It's also the fastest way to turn one at-fault accident into a judgment against your house and retirement accounts. A plan that reaches $1,300 by cutting liability has produced a worse year, not a better one.
10. How do I know I'm not quietly underinsuring myself?
There is a tempting arithmetic where you hit the goal by shaving a limit. The quote comes back on a screen and the savings bar sits right at $1,300, and you can feel the afternoon about to pay off. That is the moment the audit turns into a different job, because you have not saved $1,300, you have sold $300,000 of protection for a few hundred dollars and a worse year.
The savings in this audit come from wrong facts and stale prices. A roof typed in as seven years younger comes back at $190 a year, and that is free money off a page error. Removing liability is not free. A judgment against the household follows the $420,000 house, the savings account and the retirement accounts, and $1,000,000 of umbrella coverage runs $310 a year, the cheapest protection on the page.
So the answer to the question in the heading: keep the coverage that answers to a lawsuit. The boundary of the job is home, auto, umbrella and term life. Medicare, Medigap, annuities and long-term care sit outside it, and questions about those belong with the state insurance department or a SHIP counselor, not with a savings estimate.
💡 Tip: The boundary of the audit: home, auto, umbrella and term life only. Medicare, Medigap, annuities and long-term care are outside it. Questions about those go to your state insurance department or a SHIP counselor, not to a savings estimate.
Frequently Asked Questions
Is it too late to re-price my insurance after I've retired?
No—retirement is exactly when the stale inputs are most out of date. Your mileage dropped, your roof aged, your dependents left. The policies were priced for a working life you no longer live. Re-pricing simply updates the record.
How much should I expect to save?
The example household found $1,295 a year, but your number depends on how stale your inputs are and how many policies you carry. The biggest savings usually come from correcting roof age, re-shopping auto, and raising the home deductible—if you have the cash reserve.
Should I drop collision on my older car?
If the car is worth under about $10,000 and you have a reserve to replace it, dropping collision can save real money. If a write-off would change what you drive or force you to finance a replacement, keep it.
Can I cancel my term life insurance to save the premium?
Only after a dependents and beneficiary check. Lapsing is irreversible, and replacing a policy at 68 or 70 means re-underwriting or refusal. In the example, the policy was kept pending that check, and the $1,295 did not depend on touching it.
Where do I start if I only have one hour?
Pull the homeowners and auto declarations pages and correct the roof age, square footage, mileage, and garaging address with your agent. That one call captures $190 plus whatever the corrected mileage and address are worth—often more than any other single move.
The declarations page, the three numbers, and the first call
Run the insurance audit before any other money task this year. The verdict is plain: $1,295 for 2 hours 40 minutes, roughly $490 an hour, and that total only holds because the $300,000 liability limits and the $1M umbrella stayed exactly where they were.
Pull the home and auto declarations pages and check three numbers against the house and cars in the driveway: roof age, square footage, annual mileage. Glance at the garaging address while the page is open.
One call first, to your current agent, the one that carries both the corrections and the deductible change. Write the three numbers down before you dial.
Your neighbor got $400 from one policy. The other $895 is sitting in your own file drawer, still priced for a working life that ended years ago.
Pull one declarations page today
Find your homeowners policy summary and check the roof age and square footage against what you know. One correction call is the start of the $1,295.