Nine hundred dollars. That is one emergency vet bill, and for a household with $10,000 sitting in savings it should be a Tuesday.
So why does the person who just crossed five figures still feel the old flinch when the card reader beeps at the clinic? The round number arrived and the calm did not.
Because the number was never the relief. The relief is the bill, the gap, the move or the work choice it can cover without a new balance or a loan against next month. A milestone that does not retire a specific fear is just a nicer-looking spreadsheet.
For you that fear might be the $1,600 dental crown nobody scheduled, or a $9,900 three-month job gap on a $3,300 monthly budget. Either way, the milestone that changes how life feels is the one that ends that particular worry, not the one that looks impressive in an app.
By the end you should be able to name your next target – $1,000, $10,000, $25,000 or a work-choice level – and point the next dollar at the thing actually keeping you up.
Quick Tips Before You Start
Name the fear
Write down the one money worry that wakes you up before you pick a milestone.
Keep cash separate
Emergency cash belongs in a savings account, not invested with retirement money.
Count months, not dollars
Divide your target by $3,300 — the monthly basics in this article — to see how much time it buys.
Automate the transfer
Move the amount on payday morning so it happens before the month gets a vote.
Expect paper losses
A $100,000 portfolio can drop $18,000 in a bad year without you selling a share.
First Safety Milestones
Before you can talk about investing or quitting a job, you need to stop the small emergencies from becoming debt. The first three rungs — $1,000, $10,000, and zero net worth — are about that shift. They are not about getting rich. They are about moving from reactive to steady.
Each step here retires a different fear. Start with the one you recognise.
1. $1,000 turns a crisis into a receipt
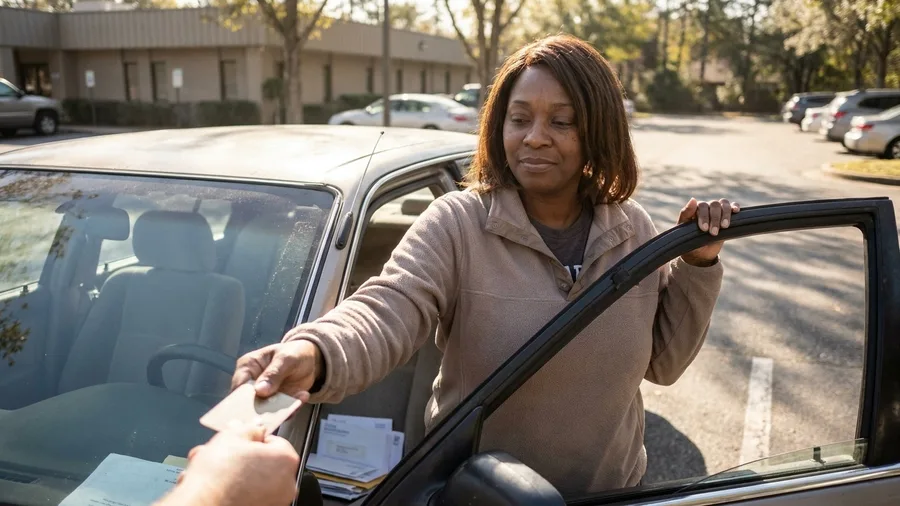
If you have ever flinched at an emergency because there was no money set aside, $1,000 is the number that gets you out of that flinch. It is a starter cash buffer, kept in savings and not invested, and its whole job is to keep an ordinary emergency from turning into new debt.
Picture the bill arriving: $900 for an emergency vet visit, $1,600 for an urgent dental crown, $2,400 for a car transmission repair. Any one of those can be paid from that buffer without reaching for a card balance. You pay it, you feel the sting, and then you rebuild the buffer. The only real change is that you have one fewer panic decision to make.
What makes $1,000 worth starting this month rather than next is that emergencies do not wait for your savings account. A lost paycheck stays uncovered at this level, which is why the next milestone has to measure time and not just the size of a single bill.
💡 Tip: Keep this account at a different bank from your checking account so it is not one tap away.
| Net worth milestone | What it can cover | What it does not fix | Life-feel change |
|---|---|---|---|
| $1,000 | A $900 vet bill or $1,600 dental crown | A lost paycheck | One fewer panic decision |
| $10,000 | A 3-month job gap ($9,900) | Long unemployment or retirement | A short pause |
| $0 | Nothing spendable — but new savings count | A cash cushion | The debt spiral ends |
| $25,000 | A $6,000 move plus a $9,900 gap | Repeated shocks | One real-life reset absorbed |
| $50,000 | Visible retirement progress | Market losses | Investing stops feeling abstract |
| $100,000 | 2.5 years of $39,600 basics ($99,000) | Permanent work freedom | A choice budget |
| $250,000 | 6.3 years of basics ($249,480) | Permanent freedom | Leverage in work negotiations |
| $500,000 | 12.6 years of $39,600 basics ($498,960) | High-cost-city freedom | Freedom only on a low budget |
| $1,000,000 | Career-risk buffer | The $1,800 monthly mortgage | Less trapped by one employer |
2. $10,000 buys a short pause, not freedom
I remember the first month I moved $40 into a savings account and thought, this is not going to do anything. It sat there for three weeks and my brain kept telling me it was a rounding error. Then I had a $210 car repair and did not have to move money from checking to cover it. The $40 did not change the repair. It changed my reaction to it.
The target is worth naming: $10,000. If your monthly basics run around $3,300, that is about three months of expenses. For most people $10,000 is not built in one sitting. It gets built at $25, $50 or $100 a month, moved automatically the day after payday, before the rest of the month gets to make its case.
The three-month gap is $9,900 with the same health premium still due, and that is where ten thousand lands you. A $10,000 cushion minus a $9,900 job gap leaves $100 before any new cost enters the picture. The pause is real, but it is short.
Ten thousand does not buy freedom. Long unemployment is outside the number, retirement is outside the number, and a second setback would arrive before the first one is fully absorbed. What it buys is a pause: three months to find the next paycheck without the phone call to a family member or a new card balance.
This is where the small-start permission matters most. You do not need $10,000 to begin. You need $25 and a standing transfer. The people who reach this number are rarely the ones who saved the most in one month; they are the ones who kept the transfer running when it felt pointless.
Keep the $10,000 in cash. It is not investing money and it is not retirement money. Its whole job is to absorb the short gap so that a lost paycheck does not become a new card balance, and a new card balance does not become the rest of your year. Anyone digging out of a balance instead of building one can see what paying off debt wrong costs in wasted years.
The fear it retires is the short job gap. A long layoff, a medical year, a market crash in retirement savings – those sit outside this number and deserve their own target later. The reader who can look at $10,000 and say, I can cover three months, is already in a different position than the one chasing a round figure without knowing what it covers.
3. Zero net worth ends the debt spiral
A debt of $12,000 against $4,000 in assets is a net worth of minus $8,000, and every $1,000 you put toward the card lifts that figure by $1,000 while cutting the balance by the same amount. The net worth can be negative at the same time that $10,000 sits in savings, which is why the two numbers do not cancel each other.
Zero net worth is a turning point, not a finish line, and it is okay if you are still far from it. Keep the savings account funded even while the debt is being paid down. Moving the buffer into the card to speed the balance feels efficient and leaves you one $900 vet bill away from a new balance.
Zero net worth changes the balance sheet. It does not put a single dollar of spendable cash in your hand. The fear it retires is every new dollar going to old choices. The cash for an actual reset – a move, a job gap – is a separate target, and that is what comes after this one.
💡 Tip: Calculate net worth monthly: total assets minus total debts. Watching that number cross zero is worth more than any round milestone below it.
4. $25,000 absorbs one real-life reset
The number that wakes you at 2 a.m. is not a market crash. It is a lease ending the same month a job does, and you cannot see how both fit into one bank balance. That is the reset a cushion is meant to absorb, and $25,000 is the first rung sized for a real one instead of a single bill.
Run the two costs side by side. The move is $6,000: deposit, movers, and the first month of basics before any paycheck from the new job lands. The job gap is $9,900 at $3,300 a month, the same $250 health premium still due every month. Add them and the reset costs $15,900. A $25,000 cushion pays it and leaves roughly $9,100.
a $1,000 surprise-bill floor, a $9,900 gap bucket, and a $6,000 move-or-setup bucket. When the reset hits, each bill draws from its named bucket. You are not deciding under pressure whether you can afford the movers. The bucket already answered that.
What it does not cover is the honest part. A second move six months later, or another job gap before you rebuild, eats the $9,100 remainder and then some. Repeated shocks are not what this rung handles. Neither are six-figure choices, and neither is retirement money moving visibly, which is a different account and a different question. What $25,000 retires is the fear of one move plus one short gap landing on a loan. The fear of a bad year repeating stays.
If you only have $12,000, start the system anyway with the two buckets you fear most and label them. Half a structure beats a full intention.
The monthly basics bill
Illustrative example. Substitute your own numbers to get your personal time-buying figure.
Options and Trade-offs
Once you have a cash cushion, the next milestones start changing what you can choose, not just what you can survive. That is where the numbers get larger and the trade-offs get more real.
Each rung here retires a specific recurring fear. Before you pick one, ask what it would actually let you do.
5. $50,000 makes retirement saving visible
Open your retirement account statement and look at the line that shows the year's gain or loss, not the balance. If that number has started to move by thousands on its own, you have crossed into a different relationship with the money. That is what $50,000 buys first: the market stops being a rumor and becomes a force acting on your balance.
A $9,000 paper loss in a bad year, with nothing withdrawn, is the part nobody warns you about. The milestone that felt solid suddenly looks fragile, and the reflex is to check the app daily and re-decide something. Contributions still matter more than the round number, because your steady monthly deposit and the market's movement are both moving the total now, and the deposit is the half you control. Learning why the portfolio feels stuck for years can explain what portfolio growth curve is doing while you keep contributing. Keep watching the contribution line, not the daily balance.
Keep emergency cash somewhere else entirely. The $50,000 in retirement is not the cushion for a $9,900 job gap and it is not the $1,000 that covers a $900 vet bill. Pulling retirement money early can carry a penalty and a tax bill, which turns a small emergency into a large one. Before you set the next target, run your own numbers with a fee-only fiduciary, someone who charges you directly and earns no commission on what you buy, because the right split between retirement and cash depends on your tax bracket and your plan's rules.
What this rung retires is investing feeling abstract. What it leaves is market loss, which no balance removes. The next threshold tests what the money can actually buy.
💡 Tip: Automate a small monthly contribution into a low-cost index fund that tracks the whole market. If you want a person to review your allocation, talk to a fee-only fiduciary who does not sell products.
⚠️ COMMON MISTAKE
Do not pay the vet bill from retirement
The $1,000 emergency buffer and the $50,000 retirement balance have completely different jobs. If a $900 vet bill comes from the retirement account, you have turned a small milestone into a tax headache. Use the cash cushion first, then rebuild it.
6. $100,000 buys choices, not independence
Six figures looks like the number that lets a paycheck become optional. It doesn't. At $3,300 a month in basics, $100,000 covers 2.5 years of a stripped-down life – rent, food, transport, the health premium – which is a long time to say no while you look for something else. Twenty-nine months of breathing room is not the same as never working again.
Which is why the most common use of this level is a down payment, and that trade is where the relief lives or dies. Put $50,000 down on a $400,000 house, add about $8,000 in closing costs, and roughly $42,000 stays in the account – but a new $1,800 mortgage now leaves every month. The house converts cash into equity and a recurring bill, while a job search spends the cushion instead of parking it. Neither choice is wrong; each retires one fear and invites another.
one holding the $42,000 left after the closing, flowing to a high-yield savings account, and the other a transfer that fills it back at $250 a month so a second emergency does not restart the count from zero. Then leave it alone – do not check the balance weekly. The fear this retires is a forced move or a search cut short by lack of cash. Permanent work freedom still sits unpaid, so the next rung measures years of basics.
Two ways to use $100,000
How long the money lasts depends entirely on the decision
Illustrative based on an example $400,000 home. Your closing costs and mortgage will differ.
7. $250,000 changes work negotiations
No – it makes saying no possible for a while. Two years of choices is a short leash when a bad manager wants an answer this month, and $250,000 is the first rung where the leash gets long enough to argue with.
Count the runway. At $3,300 a month in basics, $39,600 a year, $250,000 stretches about 6.3 years, roughly $249,480 of expenses. That is long enough to turn down a role that would wreck your health, or to take a pay cut and keep the lights on while you look for something better.
The catch is that the clock is running the whole time. Rent of $1,800 and the $250 health premium do not pause while you are negotiating, so the no is time-bound, not permanent – 6.3 years from now those same costs are still there and the buffer is spent. That is more than double the 2.5 years a $100,000 choice budget buys, which is why this rung is where a bad role can actually be refused rather than just survived.
What each milestone actually buys you
Time and cushion
- $10,000 → covers a 3-month gap ($9,900)
- $25,000 → covers one move plus a gap ($15,900)
- $100,000 → 2.5 years of basics ($99,000)
- $250,000 → 6.3 years of basics ($249,480)
Freedom or choices
- $1,000 → one surprise bill
- $0 → ends the debt spiral
- $50,000 → visible retirement progress
- $1,000,000 → career-risk buffer, mortgage still due
Big Numbers and Limits
The final three rungs are where most people expect the biggest feeling change and often find the smallest one. The numbers are larger, but the recurring costs do not disappear.
Here is what each big number actually covers — and what it does not.
8. $500,000 is freedom only for a budget
Review the $500,000 level against your own budget, not the round number, because half a million is freedom at $39,600 a year and a safety net at anything much higher.
At $3,300 a month, $39,600 annually, $500,000 covers about 12.6 years, roughly $498,960 – freedom, but only on that budget. Add up what you actually spend and divide the number by your own annual figure; the answer tells you whether this is an exit or a cushion.
The second thing to check is the costs that never stop: $1,800 rent and the $250 health premium keep arriving every month, whether or not the portfolio is up. A level that requires low expenses or continued income to work is not a guaranteed retirement – it is a bet that your spending stays where it is.
The third is location. On a low budget in a low-cost town, this number retires the fear of a long work gap. In a high-cost city, the same $500,000 buys a safety net, not an exit, and the check-in should say so plainly.
The $1 million reality check
🏠 Home equity
$350,000
📈 Retirement accounts
$500,000
💵 Taxable savings
$150,000
🏦 Mortgage still due
$1,800/mo
Spendable cash
Home equity is not cash unless you sell or borrow, and retirement money is not all cash either.
9. $1 million still includes a mortgage
A reader sent me the spreadsheet behind his $1 million and asked why he still flinched at the mortgage autopay. It made sense once I saw the breakdown: $350,000 home equity, $500,000 in retirement accounts, $150,000 in taxable savings, and an $1,800 mortgage still due on the first.
Only the taxable piece is money you can spend without a penalty or a sale. Home equity is not spendable unless you sell the house or borrow against it, and retirement money is not all cash, so most of that million is working somewhere other than his checking account.
That is why daily decisions still track the paycheck. The mortgage, the food, the utilities, the transport, the $250 health premium, the phone and internet – they all recur, and none of them check the net worth total before they come due.
What the million did buy him was career risk. He could take a job at a smaller company, or survive a six-month gap, because the balance could absorb it. Being trapped by one employer stopped being the main fear, and that is worth naming as a genuine change.
But the fear left standing is monthly cash flow, and it does not care about the seventh digit. He had been treating the total as a feeling instead of a breakdown of what was actually spendable.
The next step is not a bigger number – it is turning that cash flow question back into a specific target, which is exactly what comes next.
💡 Tip: A fee-only fiduciary or CPA can help you sort spendable assets from retirement money and plan the gap. Worth the one-hour fee before you make a major career or housing move.
💡 PRO TIP
Run the paper-loss drill
Before you chase a bigger number, picture the balance dropping by 18% — a $100,000 portfolio could show an $18,000 paper loss in a bad year without you selling a share. If that number would make you sell, your risk level is wrong for the fear you are trying to retire.
10. The feeling follows the next bill covered
That low-grade worry that the month is one bad surprise from breaking does not go away because the balance hit a round number. It goes away when the specific bill that keeps replaying in your head is one you could pay that same day.
So match the milestone to the fear, then let the figure follow. The surprise-bill fear is the $1,000 target: a $900 emergency vet visit, a $1,600 urgent dental crown, or a $2,400 transmission repair comes out of cash instead of onto a card you then carry. The job-gap fear is the $10,000 target, which covers the $9,900 three-month gap on $3,300 of monthly basics. The move-plus-gap fear is the $25,000 target, because $6,000 for a deposit, movers and first-month basics plus that $9,900 gap is $15,900, leaving roughly $9,100 standing.
every dollar aimed at one fear is a dollar not aimed at another. Build the $10,000 job-gap cushion and the surprise-bill money is sitting in the same pile, earmarked for rent, so a $900 vet bill in month two of a layoff pulls the gap cover down to $9,100 and stretches the pause thinner than the number suggested. The worry does not retire on its own, either. Someone with a fully funded $10,000 who still panics at a $900 vet bill has bought the cushion but not the calm, because the target was funded for the wrong fear.
That is the trade worth making anyway. Choosing one fear to cover buys a real, checkable calm for that fear rather than a vague sense of being behind on all of them. Pick the fear that wakes you, fund its number, and leave the rest for a later paycheck.
The order is not universal. A household renting month to month with a shaky industry should cover the job gap before the vet bill; a household with an old car and a dog should do the reverse. Cover the one that would actually break the month first, and let the figure follow the fear instead of the fear following the figure.
Frequently Asked Questions
How much should I have in my emergency fund?
Start with $1,000 in cash if you have nothing. That covers most surprise bills — a $900 vet visit or a $1,600 dental crown — without adding debt. Then build to three months of basics: for this article's $3,300 monthly budget that is $9,900. Go toward six months only if your income is unstable or you are supporting others.
Should I pay off debt or save first?
Build the $1,000 cushion first, because without it every new expense goes back on a card. After that, put extra money toward the highest-interest debt — credit cards sit around 20% APR, according to Federal Reserve data. Once the debt is gone, redirect that payment into an emergency fund.
Is $100,000 net worth really a milestone if I still have a mortgage?
It changes what you can choose, not whether you can quit. As a job-search budget, $100,000 covers about 2.5 years of $39,600 basics. As a down payment, $50,000 plus $8,000 in closing costs leaves $42,000 and adds a $1,800 monthly mortgage. Neither is permanent freedom, and both are real options.
Why does my net worth drop even when I am saving?
If part of your net worth is invested, a bad market year can erase more than you contribute. A $100,000 portfolio can show an $18,000 paper loss without you selling anything. That is normal and not a reason to change course. Check your balances monthly, not daily, and keep emergency cash out of the market.
Does $1 million mean I can stop working?
Not necessarily. A $1,000,000 net worth that includes $350,000 in home equity and $500,000 in retirement accounts still leaves a $1,800 monthly mortgage due and most retirement money untouchable without penalty. It makes career risk more bearable. For a specific plan, talk to a fee-only fiduciary or CPA.
Which milestone should I chase if I cannot stop worrying about money?
Match the milestone to the fear. If a surprise bill is the worry, aim for $1,000. If a job gap is the worry, aim for $10,000. If a move plus a gap is the worry, aim for $25,000. Round numbers only help when they retire the fear you actually have.
Aim the next dollar at the fear you actually have
The verdict is plain: a milestone changes how life feels when it removes a specific recurring fear or buys time. A round number does not, on its own, and chasing the next zero before that is how people end up at $10,000 still flinching at a $900 vet bill.
So fund your weak spot first. Surprise bills: $1,000. A three-month job gap on $39,600 a year: $10,000. A move plus the first-month basics: $25,000. A work choice: $250,000, where 6.3 years of basics lets a bad role be refused instead of endured.
If the $900 vet bill still stings, the next dollar goes there, not to a prettier round figure. Pick the fear, aim the dollar, let the number follow.
Which fear is loudest for you right now?
Write it down, match it to the milestone in this article, and set the automatic transfer for payday morning. That is the next step, and it is enough.